AL Circle Analysis: 243% US scrap rise, 6Mt European recycling & Germany’s power fix drive aluminium trade
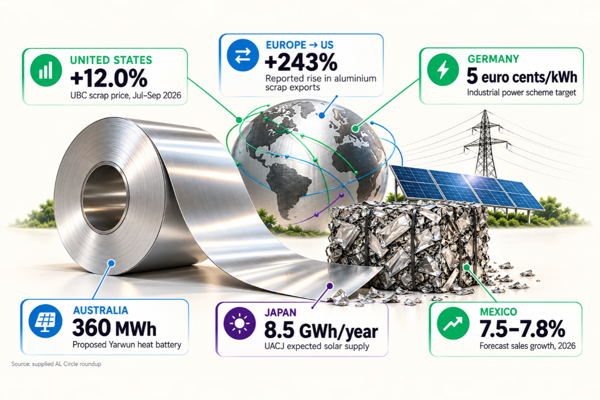
Aluminium’s trade map is no longer drawn by smelters alone. Scrap flows, power contracts, industrial policy and specialist grades now shape who secures metal, at what cost and under whose rules. Ten recent developments across Europe, the US, Australia, Japan and Mexico show how recycling, energy and regulation are becoming the new levers of aluminium competitiveness. They also show where traders, exporters and policymakers may need to adjust. Scrap tug-of-war: the US pull, Europe’s leak and the recycling base at stake The pull starts with price. The US UBC scrap benchmark averaged USD 2,322.89 a tonne in July, USD 2,491.22 in August and USD 2,602.51 in September. That is a 12 per cent climb, and it came after a July that opened at USD 2,464.98 and fell to USD 2,270.76 within two days....
Europe’s 9M 2026 aluminium production jumps to 5.56Mt as smelter restarts gain ground
As the global aluminium supply chain continues to swing between shifts and crunches, how has Europe fared on the production front in the 2026 year-to-date calendar? Substantially well, going by the output figures. Between January and September 2026, the European continent, including Russia, has produced a total of 5.56 million tonnes of primary aluminium, building a significant year-on-year growth chart. The nine-month growth chart Set against the same period of 2025, the first nine months of 2026 show a clear lift in output. From January to September 2026, Europe, including Russia, produced 5.56 million tonnes of primary aluminium, raising the annual growth rate by 5.69 per cent year-on-year (Y-o-Y) over the 5.26 million tonnes produced in 2025. Explore the production, demand and...
Grow with
AL Circle

AL Circle analysis: From cans and NEVs to extrusion, shifting end-use demand reshapes aluminium’s growth story
The aluminium industry is entering the second half of 2026 with demand signals moving in different directions. Beverage cans are finding new consumption opportunities in Brazil, extrusion demand remains resilient in key markets, and aluminium producers are benefiting from firmer prices. At the same time, tariffs and trade-policy uncertainty are adding cost pressure, while automakers and packaging companies are placing greater emphasis on aluminium’s role in lower-carbon products. Demand: New consumption patterns open fresh opportunities Brazil’s beverage can market is maintaining a positive trajectory in 2026, with 16.4 billion cans sold in the first half and full-year growth expected in the low single digits. The more interesting development, however, is the changing beverage mix. Beer...

AL Circle Analysis: Regional output & trade reflect bauxite-alumina supply contrast in aluminium market
If aluminium has a pressure point right now, it sits one step upstream of the metal itself - in alumina. China’s appetite for imported ore remains elevated, alumina markets diverge between regions, and disruptions in Guinea and Australia expose logistics risks. At the same time, tariffs and regional premiums are reshaping the economics of aluminium, making access to competitively priced alumina and metal increasingly dependent on geography, trade routes and policy. Bauxite supply: Sourcing, scrutiny and shifting trade flows Jamaica and Ghana are negotiating a USD 60 million arrangement in which Jamaican bauxite would be refined into alumina at ATALCO’s Gramercy, Louisiana plant before shipping to Ghana’s aluminium industry. Talks, backed by Ghana’s President Mahama, began in March 2026...

India’s alumina trade surplus nearly quadruples to 1.72 Mt in H1 2026 as exports hit 2.5 Mt
India’s alumina trade underwent a sharp shift in the first half of 2026, with exports accelerating to a new high while imports contracted substantially. Data for HS 281820, i.e. aluminium oxide excluding artificial corundum, shows that India exported 2.5 million tonnes in H1 2026, up 51.3 per cent from 1.65 million tonnes in H1 2025. At the same time, imports fell 34.9 per cent year-on-year to 775,362 tonnes from 1.19 million tonnes. The result was a substantial widening of India’s net alumina trade surplus. The country moved from a surplus of about 460,466 tonnes in H1 2025 to 1.72 million tonnes in H1 2026, a nearly fourfold increase. Exports climb to a record level India’s alumina exports have been on a clear upward trajectory since Q2 2024. Quarterly shipments rose from 458,621 tonnes...

Europe’s aluminium extrusion demand set to grow at 2.42% CAGR through 2035 - Which end-use sectors will drive it?
Europe’s aluminium extrusion market is entering a new phase, with demand expected to expand across several key industries. The region accounts for around 10 per cent of global aluminium extrusion usage, making it an important market for producers and suppliers. Electric vehicles, grid investment and construction activity are set to play an important role in shaping demand over the coming years. Aluminium extrusion usage in Europe is forecast to rise from 3.48 million tonnes in 2025 to 3.56 million tonnes in 2026, an increase of 2.30 per cent. By 2035, usage is projected to increase by 27.01 per cent from 2025 levels. The CAGR for 2025-2035 is expected to be approximately 2.42 per cent. For the exact figures and detailed sector-wise outlook, read our updated aluminium extrusion report -...

Germany aluminium extrusion market outlook H2 2026 after imports fall 3.5% as exports rise 1%, & billet premiums double
Germany’s aluminium extrusion trade enters the second half of 2026 on firmer footing than a year ago, even as Europe's extrusion industry works through plant closures, elevated billet premiums and a shift toward low-carbon, value-added output. Quarterly trade data through Q2 2026, along with AL Circle’s recently updated “ The World of Aluminium Extrusions - Industry Forecast to 2035 ” and other reports on Germany’s aluminium extrusion market sizing, point to a market that is stabilising in volume but being rewritten in composition, with automotive lightweighting, EU carbon border rules, and energy-driven capacity rationalisation the dominant forces heading into H2 2026. Germany's Aluminium Extrusion Trade Pulse (Q2 2024-Q2 2026) Germany runs a large, structural trade deficit in basic...

Trump’s 50% auto tariff puts US-Canada trade, aluminium supply chain at risk
The US-Canada trade debate has taken a sharper turn after President Donald Trump warned of raising tariffs on Canadian cars, trucks and automotive parts to 50 per cent from January 1, 2027. The move could have significant implications for the deeply integrated North American automotive supply chain, where cross-border movement of vehicles, components and aluminium-intensive parts is central to production. With Canada preparing retaliatory measures, automakers and suppliers now face greater uncertainty over costs, sourcing and investment decisions. President Donald Trump announced the proposed tariff increase after US-Canada trade negotiations broke down. He also called on companies to manufacture in the US, stating, “Build in the US and there are ZERO TARIFFS.” To know the aluminium...

Canada’s aluminium extrusion imports rise 20% over five years, strengthening the case for protection measures
Canada’s aluminium extrusion market is expected to expand significantly over the coming years. The market was valued at USD 2,747.8 million in 2025 and is projected to reach USD 3,745.4 million by 2030, representing a 6.4 per cent CAGR, according to industry data. Recovery in automotive production, infrastructure investment and resilience in aerospace are expected to support this growth. At the same time, imports remain a significant part of Canada’s aluminium extrusion market. Average annual imports increased from 100,068.18 tonnes in 2016-2020 to 120,266.40 tonnes in 2021-2025, representing a 20.18 per cent increase. Imports peaked at 135,981 tonnes in 2022, before falling to 116,054.48 tonnes in 2024, down 14.7 per cent, and then to 111,376.35 tonnes in 2025, a further 4.0 per cent...

Metal packaging leaders call for clarity, competitiveness and collaboration
Europe’s metal packaging industry is facing mounting pressure from rising costs, regulatory uncertainty, geopolitical tensions, labour shortages and competition from alternative materials. But according to three industry leaders, its biggest challenge may be internal: moving faster, communicating more effectively and acting with greater unity. Iris Arsic reports. Speaking at the Metal Packaging Europe (MPE) conference in Berlin, Paulo Sousa, CEO of Colep Packaging and president of MPE, Seàn Cairns, president of Sonoco Consumer Packaging EMEA & APAC, and Michael Mapes, CEO of Trivium Packaging, argued that metal packaging enters this period from a position of strength. The industry already has proven circularity and strong sustainability credentials. The challenge, they said, is ensuring...

AL Circle Analysis: Inside aluminium’s global recycling reckoning with scrap, solar and smelters
Aluminium’s circular economy is no longer a sustainability side story — it is becoming a contest over who controls scrap, who sets the compliance bar, and who can afford the energy to keep smelting. On one hand, recycled aluminium is being tested, as dross piles up in China, scrap ships out of the US faster than domestic recyclers can replace it, and only a third of the world’s beverage cans actually become cans again. On the other hand, governments are throwing real money at keeping primary production alive, from Canberra’s power-price rescue of an Australian smelter to Chinese capital scouting a new industrial base in Egypt. These indicate that circularity is becoming as much a matter of industrial strategy and geopolitics as of technology. To know the aluminium casting demand forecast...

From 67% to 80%: Crown Holdings steps up its recycled aluminium ambition for beverage cans
What does it take to make an aluminium beverage can more sustainable? The answer is no longer limited to what happens on the production line. For Crown Holdings, it starts with the aluminium entering the plant, continues through energy and water use during manufacturing and extends to what happens to the can after it is used. That wider picture runs through Crown’s 2025 Sustainability Report. As the company reaches the midpoint of its Twentyby30™ programme, the report brings together its progress on emissions, renewable energy, recycled aluminium, lightweighting, water, waste and responsible sourcing, while setting out the next stage of its sustainability ambitions. For the aluminium industry, perhaps the most significant part is the growing focus on the material itself - from increasing...

US aluminium extrusion demand to hit 4.2Mt by 2034: Which end-use sectors will drive demand?
The United States is emerging as one of the most important markets for aluminium extrusions , with demand spread across transportation, building and construction, electrical and electronics, machinery and equipment, consumer durables and other industrial applications. IMARC estimates that the US aluminium extrusion market reached 3.0 million tonnes in 2025 and projects it to reach 4.2 million tonnes by 2034, representing a CAGR of 3.71 per cent between 2026 and 2034. Transportation and building & construction dominate North American aluminium extrusion demand, together accounting for around 65 per cent of total usage. In 2024, transportation was estimated to represent 33 per cent of North American aluminium extrusion consumption, followed by building & construction at 32 per cent ....

420 billion cans, one 20-year-old fix: The Six Sigma Case for can-to-can recycling
New IAI data show that closing the can-to-can loop, not simply collecting more cans, will decide whether the industry produces 207 billion or 685 billion recycled cans by 2050. A Six Sigma study from Kentucky, co-authored nearly two decades ago by Dr Subodh K. Das, offers a strikingly relevant blueprint for treating every unrecycled can as a preventable process defect. Aluminium's most-quoted recycling statistic keeps getting bigger, but a new analysis from the International Aluminium Institute (IAI) suggests that scale alone will not decide how much of that metal comes back as new cans. According to the IAI’s September 2025 factsheet, "Can-to-Can Recycling: Performance, Potential and Pathways," the industry currently puts around 420 billion aluminium beverage cans on the market every...

From $82/t to $66.5/t: Where is Australia’s bauxite market headed in 2026?
Australia produced about 102.4 million tonnes of bauxite in 2025 and exported 44.23 million tonnes, up from 42.6 million tonnes in 2024, making it the world’s second-largest producer. Yet just as Australia’s role as a seaborne bauxite supplier is becoming more strategically important amid uncertainty over Guinea’s exports, its own supply chain has taken a hit. Record rainfall around Weipa in January-February 2026, followed by Tropical Cyclone Narelle in March, disrupted Rio Tinto’s bauxite operations and shipments. The result was a sharp Q1 production setback and a fresh reminder that Australia’s advantage as a reliable alternative supplier is still exposed to extreme weather. Weipa was hit before Narelle even arrived The disruption did not begin with the cyclone. Rio Tinto reported that...

AL Circle Analysis: China’s 64% output, Asia’s 8.47% CAGR mark aluminium extrusion’s growth race
The global aluminium downstream market is being reshaped by three simultaneous forces: rapid extrusion growth in Asia, increasingly defensive trade policies, and rising demand from automotive, renewable energy, packaging and advanced manufacturing . China remains the dominant extrusion powerhouse, but India and Southeast Asia are building their own capacity and demand centres. At the same time, Chinese downstream exports are facing greater scrutiny in Australia and the US, while new applications such as giga-casting and recyclable aluminium packaging are opening fresh demand pools. For traders and investors, the story is increasingly about where aluminium is processed, where it is consumed and how trade barriers are redirecting those flows. Unlock in-depth insights into the extrusion...

AL Circle Analysis: From bauxite to trade, how supply risks are reshaping aluminium competitiveness
The aluminium industry is entering a phase where supply security is being tested across the entire value chain. The latest developments show the pressure beginning with bauxite, moving through logistics and alumina, feeding into aluminium prices and producer earnings, and eventually reshaping international trade. What makes these developments significant is the way they connect. Competition for bauxite is intensifying just as alumina supply is becoming more vulnerable to production and energy disruptions. Producers are benefiting from stronger aluminium prices, but tariffs and changing geopolitical risks are altering where metal flows. Meanwhile, the market is already looking beyond the current tightness towards a potentially more balanced 2027. Bauxite moves from raw material to...

Europe’s aluminium output climbs 4.9% as alumina falls 1.8% in H1 2026: Inside the supply gap and how it is bridged
Europe’s aluminium industry produced more metal in the first half of 2026, but the numbers hide a more complicated story. Primary aluminium output rose 4.9 per cent year on year to 3.648 million tonnes, while metallurgical-grade alumina production fell 1.8 per cent to 2.846 million tonnes. At first glance, the numbers may seem contradictory. If aluminium production is rising, why is alumina production falling? The answer lies in what happened during the first quarter. Alumina production was hit by energy and logistics disruptions linked to the Middle East conflict, while aluminium output benefited from smelter restarts. By Q2, however, alumina production had started to recover. Aluminium grows 4.9 per cent while alumina slips 1.8 per cent Europe, including Russia, produced 3.648 million...

From 1.27Mt to 1.02Mt: How China’s aluminium extrusion export equation changed in 2025
Leading aluminium producer and exporter China has reported a 2025 trade trend where the trade indicator appears on a declining graph. The trade volume, inclusive of all aluminium products, dipped from 6.66 million tonnes in 2024 to 6.13 million tonnes exported in 2025. Out of the 2025 figure, aluminium bars, rods, profiles, pipes and tubes, and tube or pipe fittings accounted for 1.02 million tonnes or 16.64 per cent. Zooming in on the year-to-date figures, China’s export chart has been like this: YTD May 2026 – 408,773 tonnes, up 3.72 per cent Y-o-Y from 394,104 tonnes in YTD May 2025 YTD May 2025 – 394,104 tonnes, down 20.44 per cent Y-o-Y from 495,366 tonnes in YTD May 2024 The drastic dip can also be traced in China’s annual aluminium extrusion export volume, whereby China’s 1.02...

From Hormuz to Washington: How 2Mt of Gulf aluminium puts US imports under pressure and disrupts global supply chains
Aluminium is increasingly getting caught in the fallout from the Middle East conflict. What began as a disruption to two of the region’s critical shipping routes - the Strait of Hormuz and Bab al-Mandab - is now affecting aluminium production, shipments and prices. The pressure is particularly significant for the Gulf, home to some of the world's major aluminium producers, and is beginning to expose the supply risks faced by major importing markets such as the US. Why the Strait of Hormuz matters for aluminium The scale of the aluminium exposure becomes clear from the volume of metal that normally moves through the Strait of Hormuz. The route handles around 5.14 million tonnes of primary aluminium annually, equivalent to approximately 75 per cent of the region’s total production. Hormuz...

