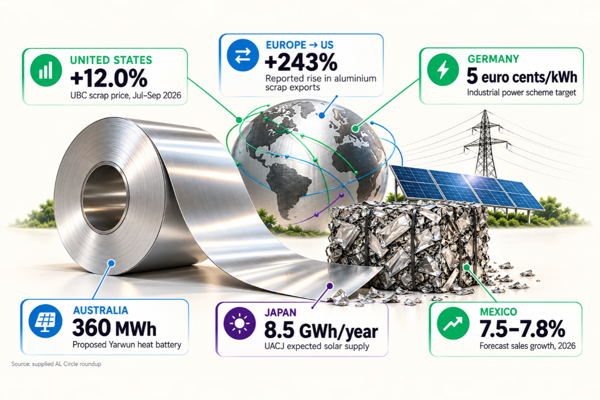
AL Circle Analysis: 243% US scrap rise, 6Mt European recycling & Germany’s power fix drive aluminium trade
Aluminium’s trade map is no longer drawn by smelters alone. Scrap flows, power contracts, industrial policy and specialist grades now shape who secures metal, at what cost and under whose rules. Ten recent developments across Europe, the US, Australia, Japan and Mexico show how recycling, energy and regulation are becoming the new levers of aluminium competitiveness. They also show where traders, exporters and policymakers may need to adjust. Scrap tug-of-war: the US pull, Europe’s leak and the recycling base at stake The pull starts with price. The US UBC scrap benchmark averaged USD 2,322.89 a tonne in July, USD 2,491.22 in August and USD 2,602.51 in September. That is a 12 per cent climb, and it came after a July that opened at USD 2,464.98 and fell to USD 2,270.76 within two days....
Europe’s 9M 2026 aluminium production jumps to 5.56Mt as smelter restarts gain ground
As the global aluminium supply chain continues to swing between shifts and crunches, how has Europe fared on the production front in the 2026 year-to-date calendar? Substantially well, going by the output figures. Between January and September 2026, the European continent, including Russia, has produced a total of 5.56 million tonnes of primary aluminium, building a significant year-on-year growth chart. The nine-month growth chart Set against the same period of 2025, the first nine months of 2026 show a clear lift in output. From January to September 2026, Europe, including Russia, produced 5.56 million tonnes of primary aluminium, raising the annual growth rate by 5.69 per cent year-on-year (Y-o-Y) over the 5.26 million tonnes produced in 2025. Explore the production, demand and...
Grow with
AL Circle
China's 22.87 Mt extrusion market faces a structural shift as 317 GW solar growth counters weak construction demand
The global aluminium extrusion landscape is undergoing a structural transition driven by industrial decarbonisation, global electrification, and the rapid deployment of clean energy infrastructure. Historically anchored by civil engineering and residential real estate, demand for extruded aluminium profiles in China, the world’s dominant manufacturing hub, is decoupling from traditional property sectors. Persistent structural weakness in China’s domestic construction market has slowed the consumption of conventional architectural profiles such as window frames, door sections, and curtain walls. Conversely, advanced industrial applications, specifically solar photovoltaic (PV) racking, battery energy storage systems (BESS), power grid modernisation, and electric vehicles (EVs), have...
AL Circle Analysis: Aluminium’s recycling economics, trade walls and carbon rules converge
The story of the aluminium industry is starting a chapter wherein scrap availability, recycling technology, trade policy, carbon costs and demand growth are becoming increasingly interconnected. From the US and Canada to Europe, India, New Zealand and China, recent developments show that the global aluminium supply chain is being reshaped on several fronts at once. These developments point to a changing aluminium business model: access to metal alone may no longer be enough. Quality of recycled feedstock, domestic processing capacity, carbon intensity, trade exposure and the ability to meet increasingly specific customer requirements could become equally important competitive factors. Join the fourth edition of the webinar “Hedging for recyclers - Become an expert in 6 hours” by Jorge...
Europe holds 10% of global aluminium extrusion demand, supported by Germany’s Constellium, France’s Hydro Extrusions & Italy’s Metra
Across Europe, aluminium extrusion has become closely woven into some of the region’s biggest industrial and construction markets. From automotive and transport to buildings and industrial applications, extruded profiles are finding demand across a wide range of sectors. This is reflected in Europe’s position in the global market: the region accounted for 12 per cent of global aluminium extrusion capacity, making it the second-largest regional contributor after China. At the same time, Europe represented 10 per cent of global aluminium extrusion usage, out of total global usage of 35.35 million tonnes . With production capacity and usage shares relatively close, Europe’s extrusion capacity and consumption are broadly at par. If we break down Europe’s 10 per cent share of global aluminium...
H1 2026 sees more renewable energy than ever: Here’s a region-by-region guide to renewable energy supply in the recent past
In the first half of 2025, humanity generated more electricity from renewables than from coal for the first time ever. What led to it? It was possible only because of two decades of falling solar panel prices, taller wind turbines, and governments finally treating clean power like an economic opportunity instead of a favour to the planet. But the renewable energy scenario cannot be portrayed as a single global story. To get the full picture, one has to connect dozens of regional stories moving at wildly different speeds. Some countries are already powered almost entirely by sun, wind and water. Others are still warming up. Here is a tour of how renewable energy supply looks across the world’s regions right now, and who is actually leading the charge. The global scorecard: Renewable energy...
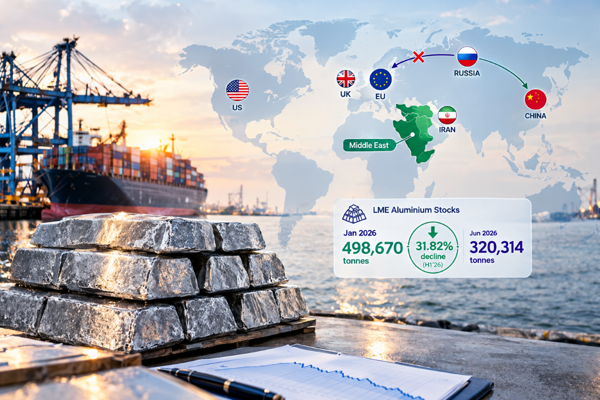
H1’26 LME aluminium stocks dip 31.82%: Russian sanctions & Gulf crisis pack a double blow
As we reflect on the Middle East crisis that commenced on February 28, 2026, and stretched into the second half of the year, it brings to mind the dramatic rise and fall of the London Metal Exchange (LME) aluminium price that reached four-year highs before cooling down. The skyrocketing prices result from the declining inventory levels of the LME aluminium stocks, thereby reporting a month-on-month decline from 498,670 tonnes in January to 320,314 tonnes in June. LME H1 inventory trend: 2026 vs 2025 vs 2024 How has the LME aluminium inventory scenario fared across the January-June period? Here is the six-month cumulative year-on-year comparison among 2026, 2025 and 2024: H1 2026 – 2.48 million tonnes, down 12.88 per cent Y-o-Y H1 2025 – 2.85 million tonnes, down 31.82 per cent Y-o-Y H1...

AL Circle Analysis: Import rise meets demand growth on aluminium extrusion chessboard
Aluminium’s downstream trade network is getting more fragmented as import dependence, changing end-use demand and trade-policy interventions reshape regional markets. From North America and Europe to Asia-Pacific, the aluminium industry is navigating a market where access to supply, competitive pricing, origin and industrial demand are gaining equal traction as overall consumption growth. These developments offer a glimpse into how geopolitical and trade networks could influence aluminium’s downstream expansion. North America: Import flows shift as downstream demand stays strong The North American market provides the clearest starting point for understanding the changing aluminium trade network. US imports of semi-fabricated aluminium products reached 423,000 tonnes in Q1 2026, up 30.56...

AL Circle Analysis: Rising bauxite supply, India’s alumina surplus and US policy reshape the aluminium industry
The bauxite and alumina industry has been busy repositioning itself on several fronts. Companies are expanding mining and smelting capacity, exploring new resource regions and moving towards higher-value products, while governments are stepping in to protect strategically important alumina assets. At the same time, changing trade flows and softer regional premiums are offering a mixed picture for buyers and sellers. The developments point to a common industry response: secure more supply, diversify where it comes from and capture more value from each tonne. Companies are expanding, but not in the same direction Growth plans across the industry show that producers are taking different routes to strengthen their positions. Ashapura Minechem is expanding its Guinea bauxite operations while...

US industrial policy needs to be systematic, not just ad hoc – Part 2
Our current approach can win economic skirmishes, but not the geopolitical conflict. – Part 2 Impact #5 of ad hoc industrial policy: Failing to use all required tools Industrial policy is often caricatured as just tariffs and subsidies. Mis-framed debates that evaluate the merits of tariffs in isolation (inevitably concluding against them) are a dime a dozen. But the industrial policy toolbox is much larger, and industrial policy can only be rightly evaluated as the success or failure of an attempt to deploy a package of tools. This includes tariffs, quotas, local-content rules, stage-differential tariffs, procurement requirements, export controls, investment screening, publicly funded R&D, tax credits, loan guarantees, federal equity stakes, technological standards-setting, workforce...

US industrial policy needs to be systematic, not just ad hoc – Part 1
Our current approach can win economic skirmishes, but not the geopolitical conflict. – Part 1 After decades during which the very concept was taboo and the reality swept under the rug, the US has now rediscovered industrial policy. But this rediscovery remains incomplete, as too much of it is reactive, scattered, and driven by whichever crisis has the attention of the moment. This ad hoc approach can win a few economic skirmishes, but it will not be enough to win Cold War II. Simply scaling up more and more ad hoc policies, the trajectory we are now on, will never produce a coherent strategy. This is because what counts is not the number of policies, their aggregate budget, or even how widespread they are. What counts is whether they fit together, effectively support each other, and serve...

Carbonation curing could extend the field life of red mud-based backfill, new study suggests
Chinese researchers show that a few extra hours of CO2 curing can roughly double the wet-dry service life of red mud–CFB ash–MgO backfill, while keeping leaching of hazardous elements low even after weeks of exposure to alkaline red mud liquor. Red mud remains one of the aluminium industry’s largest unresolved waste streams. Global bauxite residue generation has been running well above 175 million tonnes a year, against roughly 140-155 million tonnes of alumina output, and only a small fraction of that residue, commonly cited at around 2-5 per cent, is currently converted into a saleable by-product. The rest continues to swell tailings dams that, by some industry estimates, already hold more than 4 billion tonnes of accumulated material worldwide. Turning red mud into cemented backfill...

India’s electronics aluminium demand to grow 7.6-9.2 % CAGR: Why aren’t makers benefiting from strong domestic production?
India’s aluminium smelters operate with some of the highest margins in the value chain, at around 10 per cent, but this profitability is not reflected among downstream manufacturers, where margins are closer to 5 per cent. These companies convert the metal into finished products such as heat sinks, enclosures, connectors, frames and other aluminium components for electronics manufacturers, but are finding it increasingly difficult to compete with imports. This matters because India's electronics industry is growing rapidly, creating a much larger market for aluminium components. Electronics production has increased nearly six-fold to around INR 147 billion in 2024-25, from about INR 24.7 billion in 2014-15, while the sector has created around 2.5 million jobs over the past decade. The...

Aluminium extrusion 2035 demand nears 44.22Mt: Industry experts decode next decade drivers
Global aluminium extrusion demand is entering a phase with consumption projected to rise from 35.25 million tonnes in 2025 to 35.93 million tonnes in 2026 and 44.22 million tonnes by 2035, representing a 2.29 per cent CAGR. While building and construction will remain the largest end-use sector and China will continue to dominate the global market, the next decade is expected to bring stronger momentum from transportation, electrical and electronics, industrial applications and emerging markets across Asia. China accounted for 64 per cent of global aluminium extrusion usage in 2025, while the Rest of Asia Pacific (ROAP) represented 10 per cent, North America 8 per cent, Europe 10 per cent, the Middle East and Africa 5 per cent and South America 3 per cent. At the same time, the global...

EU aluminium extrusion trade story: Exports rebound and imports retreat, yet inbound volumes remain higher
The European Union’s aluminium extrusion trade is moving in two distinct, although equally subdued, directions. Exports have remained broadly resilient despite repeated fluctuations, while imports have been declining consistently since reaching a peak in 2022, according to International Trade Administration data. As far as exports are concerned, the volumes have been fluctuating over the years now. After declining for the two consecutive years by total 10.14 per cent from 345,241.74 tonnes to 310,217.09 tonnes in 2020, the exports rose strikingly in the subsequent year and regained higher volume than in 2018 level, coming in at 356,523.94 tonnes in 2021. However, the recovery did not last beyond two years and eventually plunged to as low as 319,840 tonnes as of 2023. They subsequently...

AL Circle Analysis: How are scrap, CBAM, EVs, energy rewiring the aluminium industry?
The aluminium industry stands at a juncture material quality, recycling capacity, cross-border cooperation, carbon compliance and energy security are falling into a network of interconnectivity. The aluminium supply chain is evolving from simply securing enough metal to securing the right quality, the right carbon profile, the right technology and the right energy at the right cost. For businesses, this means supply-chain decisions are increasingly becoming strategic rather than purely transactional. From secondary aluminium trust to a recycling ecosystem India’s secondary aluminium market is expanding, but buyers need stronger checks before committing to suppliers, as trust has to accompany volume. As Indian buyers increase their participation in secondary aluminium, supplier...

Australian bauxite forecast at $39/t vs Guinea at $34-46/t: How ore quality, freight and oversupply are shaping prices
What happens when the world’s biggest bauxite supplier produces too much of the one commodity it dominates? Guinea’s bauxite market is offering a striking answer. Record exports have strengthened its position in global trade, but the surge in supply has also pushed prices lower. Australia, meanwhile, continues to command a premium, even as prices across the market weaken. Guinea’s FOB bauxite price is forecast at around USD 34–46 per dry metric tonne in 2026, while Australia’s FOB price is forecast at around USD 39.15 per wet metric tonne in FY26. So why does Australian bauxite continue to hold a different price position when Guinea is supplying the market at such enormous volumes? The answer begins with quality, but it does not end there. Ore characteristics, freight costs, mining...

Coal-heavy Australian aluminium vs renewables-led New Zealand: How Oceania is balancing decarbonisation
Oceania’s primary aluminium industry is facing a fragmented energy transition. While Australia, the leading aluminium producer of the continent, has abundant renewable resources and a well-established aluminium value chain, its smelters remain significantly more dependent on fossil-fuel-based electricity than the broader Oceania region. New Zealand, another major aluminium producer in the region, tells a different tale. The International Aluminium Institute (IAI) classifies Australia and New Zealand together as Oceania, but their smelting power profiles are markedly different. In the Australia dataset for 2023, coal accounted for 58 per cent of primary aluminium smelting electricity, compared with 36.4 per cent from hydropower and 5.2 per cent from other renewables. The 2024 Oceania...

Aluminium extrusion usage in building and construction to grow 1.24% CAGR through 2035, with Americas at 1.15%, Europe at 1.30% & MEA at 2.47%
What does the building and construction market mean for aluminium extrusion industry? The answer may depend less on how much the world builds and more on where it builds and what those buildings require. As construction activity picks up across regions, aluminium extrusion is set to follow - but with the strongest opportunities emerging in different ways across markets. The global construction market was valued at about USD 11.4 trillion in 2024 and is estimated at USD 12.1 trillion in 2025. It is forecast to expand to around USD 16–17 trillion by 2030, representing a 5-6 per cent CAGR over the next five years, according to various industry sources. This expansion matters for aluminium extrusion because building and construction is already the largest end-use sector for extruded...

Asia’s alumina exports jump 27%: Is an 8Mt H2 shipment within reach?
Asia’s alumina exports entered 2026 on a strong footing, with shipments to global markets reaching 7.05 million tonnes worth USD 2.76 billion in H1 2026 , up 27.36 per cent year-on-year . The sharp rise in H1 was driven by a quarter-on-quarter surge by a considerable margin. This indicates an acceleration in aluminium production, translating into an increased demand for alumina in the market. The key question for H2 2026 is whether Asia can maintain this pace despite geopolitical disruptions, evolving refinery capacity and changing market demand. H1 2026 sets a strong export benchmark Comparing the H1 export graphs of Asia across 2026, 2025 and 2024, the Y-o-Y improvement remains consistent. H1 2026 – 7.05 million tonnes, up 27.36 per cent Y-o-Y from H1 2025 H1 2025 – 5.54 million tonnes,...

