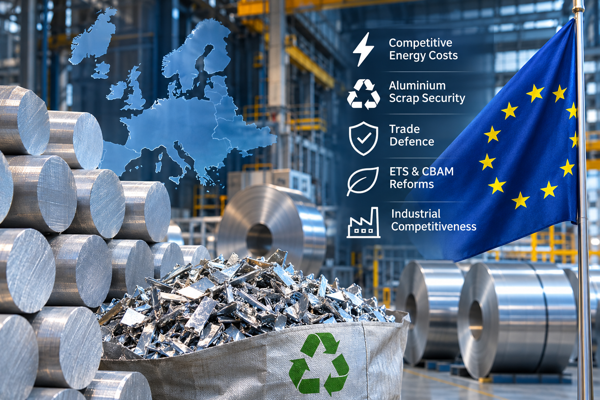
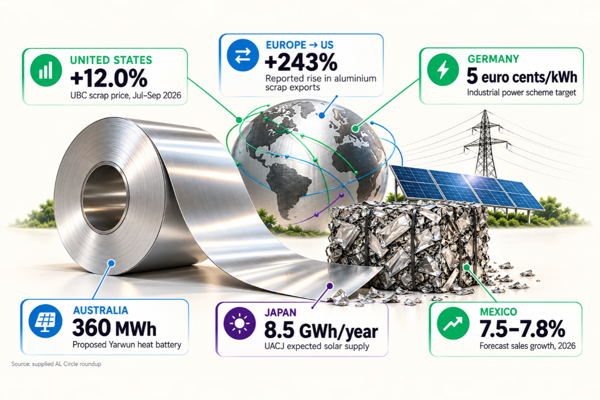
AL Circle Analysis: 243% US scrap rise, 6Mt European recycling & Germany’s power fix drive aluminium trade
Aluminium’s trade map is no longer drawn by smelters alone. Scrap flows, power contracts, industrial policy and specialist grades now shape who secures metal, at what cost and under whose rules. Ten recent developments across Europe, the US, Australia, Japan and Mexico show how recycling, energy and regulation are becoming the new levers of aluminium competitiveness. They also show where traders, exporters and policymakers may need to adjust. Scrap tug-of-war: the US pull, Europe’s leak and the recycling base at stake The pull starts with price. The US UBC scrap benchmark averaged USD 2,322.89 a tonne in July, USD 2,491.22 in August and USD 2,602.51 in September. That is a 12 per cent climb, and it came after a July that opened at USD 2,464.98 and fell to USD 2,270.76 within two days....
Europe’s 9M 2026 aluminium production jumps to 5.56Mt as smelter restarts gain ground
As the global aluminium supply chain continues to swing between shifts and crunches, how has Europe fared on the production front in the 2026 year-to-date calendar? Substantially well, going by the output figures. Between January and September 2026, the European continent, including Russia, has produced a total of 5.56 million tonnes of primary aluminium, building a significant year-on-year growth chart. The nine-month growth chart Set against the same period of 2025, the first nine months of 2026 show a clear lift in output. From January to September 2026, Europe, including Russia, produced 5.56 million tonnes of primary aluminium, raising the annual growth rate by 5.69 per cent year-on-year (Y-o-Y) over the 5.26 million tonnes produced in 2025. Explore the production, demand and...
Grow with
AL Circle

What happens to aluminium when supply, energy and carbon collide: A market simultaneously facing scarcity, costs and power risks
The global primary aluminium industry has entered 2026 with a very different market condition from the one that defined the past decade. What was once a story of supply abundance, Chinese expansion and cyclical price swings is now turning into one of scarcity, geopolitical fragmentation and carbon-driven trade barriers. At the same time, emerging supply hubs such as Indonesia and Guinea are grappling with resource protection, infrastructure tailbacks and rising power needs, while supply shocks in Mozambique, Iceland and the downstream sector are constraining the market further. China’s 45 million tonne ceiling has become the market’s hard limit One of the heaviest and most impactful events in the global aluminium market is the enforcement of China’s 45 million tonne primary aluminium...

China May gasoline demand to contract over 10% Y-o-Y
China's daily gasoline consumption in May is projected to fall over 10 per cent compared with the same period last year, partly due to high prices constraining the downstream demand, aside sustained substitution of electric vehicles, according to OilChem's data. In detail, China's gasoline demand is estimated at around 390.300 tonnes per day in May, rising 6.56 per cent from April but down 10.71 per cent from last May, based on OilChem's analysis. Entering May, the gas stations have launched sales promotions on the backdrop of sound retail margins, easing the constraints on the demand end caused by high prices. However, the May demand is likely to contract over 10 per cent compared with last year, a far more significant year-on-year decline than a normal level of around 5 per cent,...

China’s aluminium exports jump 15% in April amid Gulf turmoil, but can it replace GCC supply?
As tensions in the Middle East continue to disrupt one of the world’s most critical trade corridors, global aluminium buyers are turning towards China in search of supply stability. But while China’s exports are accelerating rapidly, the bigger question remains - can the country truly offset the growing supply risks emerging from the Gulf region? The changing trade pattern is becoming increasingly evident across major markets including India, Mexico, United States, Vietnam and South Korea, where importers are ramping up purchases from China amid concerns over freight uncertainty, tighter supply availability and potential disruptions to Gulf-linked shipments. China shipments jump amid Gulf uncertainty China’s exports of unwrought aluminium and aluminium products climbed sharply in April...

Scaling sustainability: Beverage cans in Africa’s fragmented market
In the global shift towards more sustainable packaging, aluminium beverage cans are often positioned as a near-ideal solution – infinitely recyclable, lightweight, and increasingly favoured by brands seeking both environmental credibility and shelf appeal. In Africa, however, their growth tells a more complex story. Demand is rising, but unevenly, shaped by competing realities: aspiration and affordability, formal industry and informal systems, global ambition and local constraint. Demand for aluminium cans is growing across the continent, though not in the same way as in Europe or North America. Here, the transition remains uneven, unfolding against structural and economic limits. Iris Arsic, the features editor of The Metal Packager, speaks with Chukwuma Ndigwe, recycling team lead at...

India: Aluminium prices rise w-o-w on firm MCX and LME trends
Domestic aluminium prices in India increased w-o-w as of 7 May 2026, supported by firmer trends on the London Metal Exchange (LME) and the Multi Commodity Exchange of India (MCX). As per market assessments, P1020 ingot prices in Delhi NCR rose by INR 4,500 per tonne, or 1.2 per cent, W-o-W to INR 375,000 per tonne on 7 May. Similarly, Mumbai prices increased by INR 3,000 per tonne, or 0.8 per cent, W-o-W to INR 374,000 per tonne during the same period. How did Indian and global exchanges perform? Domestic aluminium futures on the Multi Commodity Exchange of India increased W-o-W by INR 4,080 per tonne, or 1.1 per cent, to INR 369,080 per tonne, indicating improved momentum in the domestic market despite intra-week volatility. For forward-thinking aluminium market insights amidst supply...

China’s aluminium overcapacity may become the hidden stabiliser of its renewable power grid
For more than a decade, the phrase “industrial overcapacity” has been shorthand for possible inefficiency in China’s heavy industries — too many smelters, too much idle infrastructure, too much capital trapped in sectors that Beijing has repeatedly tried to rationalise. Aluminium has often sat at the centre of that debate because of its enormous electricity appetite and its strategic importance to manufacturing, transport, defence and energy transition technologies. But a new research is challenging that entire narrative. Instead of treating overcapacity as a burden, the study argues that China’s surplus aluminium-smelting capacity could become a critical flexibility tool for a renewable-heavy electricity system. Excess smelting capacity may function as a seasonal balancing mechanism for...

Global alumina production drops 6.1% in Q1 2026 as major markets retreat Q-o-Q, while North America moves against the trend
Global metallurgical-grade alumina production lost momentum in Q1 2026 after several key producing regions scaled back from the exceptionally strong output levels seen at the end of 2025, with North America emerging as the only region to register quarter-on-quarter growth, albeit marginally. China underwent widespread refinery maintenance and environmental shutdowns, Asia & Africa normalised after aggressive year-end production pushes, while Europe and Oceania continued battling energy pressures, maintenance activity and operational disruptions. These combined factors pulled global alumina production down 6.1 per cent quarter-on-quarter to 35.4 million tonnes in Q1 2026 from 37.7 million tonnes in Q4 2025. However, compared with Q1 2025, worldwide output remained broadly stable, rising...

Indian auto acceleration attracts global suppliers; aluminium supply takes centre stage
As ongoing geopolitical tensions of the Middle East conflict and the resulting inflation and shifting market dynamics bring Europe and the United States to experience a fading demand in the automotive industry, including Ford Motor Company, Stellantis, General Motors, and Volkswagen Group, auto component manufacturers eye the automotive market of India, which has been displaying robust growth. Since the 1991 de-licensing, the sector has been backed by the ‘Make in India’ initiative. The post-pandemic boom cemented India’s position as the fourth-largest player in automobile production on the global platform. Explore- Most accurate data to drive business decisions with Global ALuminium Industry Outlook 2026 across the value chain Although India does not remain untouched by the impacts of...

US' declining bauxite imports in 2025: A critical overview
The United States has long been a net importer of bauxite, owing to the small domestic reserves located in Arkansas, Alabama, and Georgia. This trend has not changed much except the numbers going up or down in 2025. Jamaica and Turkey, the only two primary exporters of bauxite to the US, have remained firm, albeit the amount dropped year-on-year, leading to the decline in the United States’ total bauxite imports. Factors driving the decline in the US bauxite imports The erosion of alumina refining capacity in the domestic market from 5 million tonnes in 2000 to nearly 600,000 tonnes today has practically reduced the demand for bauxite in the United States. At present, only one refinery - Atlantic Alumina’s Gramercy plant in Louisiana is running but at its one-third capacity, producing...

Here’s why we deduce red mud to be aluminium industry’s next resource frontier
For decades, the aluminium industry has lived with a structural contradiction: for every tonne of alumina produced, it generated up to 1.5 tonnes of highly alkaline waste. That equation has now reached a breaking point. With global alumina output crossing 141 million tonnes in 2023 and 154 million tonnes in 2025, annual bauxite residue generation has already exceeded 175 million tonnes. The cumulative stockpile stands at an estimated 4 billion tonnes, making it one of the largest untapped secondary mineral reserves on the planet. In 2026, that legacy is no longer being managed. It is being mined. Not sustainability alone, but a convergence of economics, regulation, and geopolitics Red mud, long treated as a disposal liability due to its pH of 10-13 and contamination risks, is now being...

36Mt of global alumina capacity remains unutilised, with China and Asian region showing the widest gap
Global metallurgical alumina production has been expanding in a measured and consistent manner. Output rose from 130.4 million tonnes in 2021 to 133.1 million tonnes in 2022, followed by gradual increases to 134.8 million tonnes in 2023 and 137.8 million tonnes in 2024. The trajectory strengthened in 2025, with production reaching 144.9 million tonnes, reflecting a sharper 5.2 per cent rise. However, the underlying dynamics point to a market that is not constrained by supply capacity. With global installed refining capacity at around 181 million tonnes in 2025 and utilisation levels between 85 per cent and 87 per cent, nearly 36 million tonnes of capacity remains unutilised. This indicates that output is being actively managed rather than maximised, with producers responding to demand...

Solar subsidies, aluminium shocks, and the 2026 market redone by geopolitical distress
The global energy transition has reached a point where renewable policy and industrial metals are structurally interlocked. With one month into Q2 2026, solar installation subsidies and aluminium supply chains have formed a feedback loop that is actively redoing both markets. Aluminium, long described as ‘congealed electricity,’ sits at the centre of this convergence, with the solar PV sector accounting for around 87 per cent of incremental aluminium demand within renewables. What distinguishes the 2025-2026 phase is not growth, but correction. China’s solar PV subsidy withdrawal, the European Union’s conditional incentives, the US’ tightening domestic rules, and a sudden geopolitical-induced trade disruption in the Middle East have collectively dismantled the assumptions of the previous...

India’s anti-subsidy probe on Malaysia’s aluminium wire rod imports for domestic boost
The Government of India, through its Directorate General of Trade Remedies (DGTR) under the Ministry of Commerce, has launched an anti-subsidy investigation on aluminium wire products from Malaysia. The concern for a probe was raised by the leading Indian aluminium manufacturers, such as Vedanta Limited, Hindalco Industries Limited, and Bharat Aluminium Company Limited, urging for a review to finalise an extension to the duties for trade protections. On Monday, the government announced that the probe has been made in light of the existing countervailing duties (CVDs) on Malaysia’s exports of “Aluminium Wire/Wire Rods above 7 mm diameter” (HSN code: 760511) that are scheduled to lapse in September. Under World Trade Organisation rules, countries can levy such duties to protect domestic...

India: Imported aluminium scrap prices show mixed trends despite LME strength, supply tightness
India's imported aluminium scrap prices exhibited mixed movements w-o-w as of 28 April 2026, despite an uptrend on the London Metal Exchange (LME), ongoing geopolitical tensions, and constrained global supply. According to BigMint's latest assessment for CFR Nhava Sheva deliveries, UK-origin zorba 95-5 scrap eased by USD 45 per tonne W-o-W to around USD 2,875 per tonne, reflecting a correction after the recent rally. In contrast, US-origin tense 6-7 per cent scrap gained USD 10 per tonne W-o-W to USD 2,740 per tonne. LME aluminium strengthens w-o-w Three-month aluminium prices on the London Metal Exchange (LME) increased by USD 35.5 per tonne to USD 3,588 per tonne on 27 April 2026 from USD 3,552.5 per tonne on 20 April 2026, indicating continued strength in market sentiment. Meanwhile,...
Can India sustain 8.25% aluminium duties when 55% of demand is imported?
India’s aluminium tariff regime, especially now in 2026, has become a regulatory fault line between upstream smelters chasing security, downstream processors absorbing cost pressure, recyclers fighting for cheaper feedstock and the country is trying to balance it all to keep a lid on inflation while building a strategic industrial base. A tariff to protect, but not to simplify At the centre of the debate is India’s differentiated duty structure. Primary aluminium under HS 7601 is charged at 8.25 per cent, scrap under HS 7602 at 2.5 per cent, bars, rods, profiles, plates, sheets and strips at 7.5 per cent, foil at 7.5 per cent-10 per cent, and finished structures and articles at 10 per cent. That means that the duty structure has created a constant friction point, because preferential...

Global aluminium production drops 1.6% Q-o-Q in Q1 2026, led by declines across Africa, GCC, South America, and Oceania
The opening quarter of 2026 presents a curious contradiction. On the surface, global aluminium production slipped-from 18.6 million tonnes in Q4 2025 to 18.3 million tonnes in Q1 2026, a 1.6 per cent decline. But step back, and the bigger picture tells a different story: output remains 1.1 per cent higher than Q1 2025 levels. So what changed so quickly-and why did almost every region move in the same direction? A cooling cycle, starting with China in Q1 2026 The slowdown did not come from one place. It showed up everywhere, almost at once. China, which still dominates global supply, nudged lower from 11.1 million tonnes in Q4 2025 to 11.0 million tonnes in Q1 2026 - a 0.9 per cent dip. On paper, that looks minor. In reality, it says a lot about where the system stands today. With a de...

With renewable energy set to power 45% of global electricity, led by China, Europe, US, India, where do aluminium industries stand?
Renewable energy is moving from supportive to strategic role as it is set to account for 45 per cent of the global electricity generation. This marks a structural shift in how industries will be powered. China, Europe, the United States, and India are at the centre of this transformation, driven by rapid additions in solar, wind, and hydropower capacity. While these regions lead the clean energy buildout, they also represent some of the world’s most significant aluminium production hubs, where electricity remains the single most critical input cost. So, this calls for an evaluation that how far the clean power surge in these regions is translating into lower-carbon aluminium production across these major regions. Before that assessment, the scale of the renewable buildout itself deserves...

Global bauxite production Q1’26: How the trend fared amid geopolitics and market shifts
As the primary raw material for aluminium, global bauxite mining and production continues to reinforce the aluminium value chain, with supply patterns increasingly shaped by shifting trade flows, policy interventions and evolving demand from downstream sectors. In 2026, global bauxite production is expected to reach around 475 million tonnes, which is a 0.63 per cent year-on-year (Y-o-Y) increase from 2025. This expansion is driven primarily by rising demand for aluminium products. Recent developments across major producing regions point to a changing production landscape, influenced by geopolitical dynamics, environmental considerations and rising demand from energy transition sectors. As key producing regions adjust output strategies, the market is entering a phase of recalibration...

