Giga-Casting: The aluminium shot - Alloy science, scrap loop economics, and survival pivot every foundry must execute now
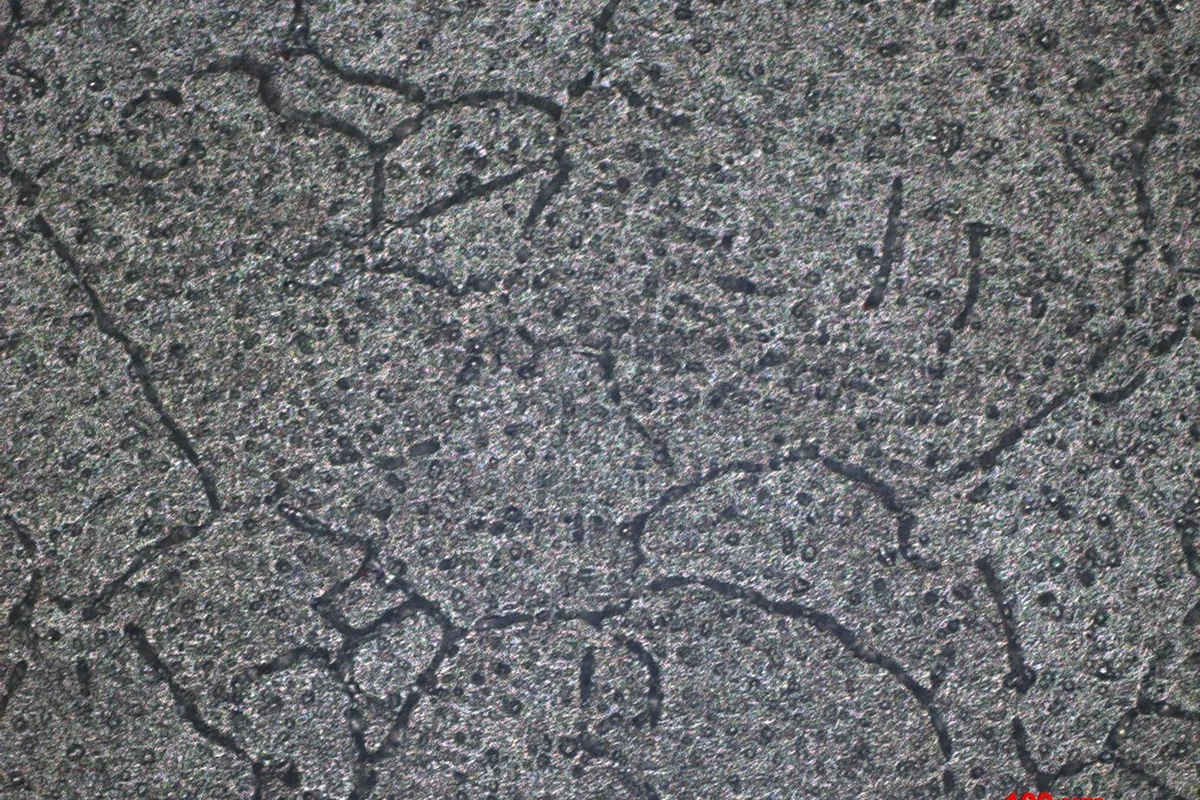
Aluminium alloy microstructure under an inverted microscope. Strontium modification converts coarse acicular silicon flakes (visible here) into fine fibrous particles-the single most important alloying step that makes structural aluminium giga-casting mechanically possible. (Photo: Wikimedia Commons / CC BY-SA 4.0)
Giga-casting technology has rewritten the economics of automotive aluminium, but the deepest disruption is not in the press hall. It is in the alloy chemistry, the scrap loop, and the macroeconomic positioning of every foundry that supplies the automotive sector. After Part 1 which highlighted aluminium giga-casting revolution in foundries, Part 2 of this series examines the metallurgical science that makes aluminium giga-casting possible, the demand that is about to be created, the closed-loop scrap economy that will redefine secondary metal markets, and what foundries in Germany, China, North America, and India must do to survive the transition.
The alloy revolution inside the machine
Standard ADC12 cannot be used in giga-casting. Understanding why requires a short look at alloy metallurgy.
ADC12 contains 1.5 to 3.5 per cent copper. Copper enables T6 heat treatment, which builds tensile strength in the finished casting. An aluminium giga-casting measuring 1.5 metres across cannot undergo T6 solution treatment without catastrophic dimensional distortion. The thermal gradients across a component of that size during solution treatment cause warping that destroys dimensional accuracy. ADC12 is also prone to surface blistering during the electro-deposition paint process when residual gas pores are present - a failure mode that is manageable in small castings but systemic at giga scale (Wang et al., China Foundry, 2024).
The industry needed an entirely new alloy class: aluminium alloys that achieve structural mechanical properties in the as-cast condition, with no post-casting heat treatment.
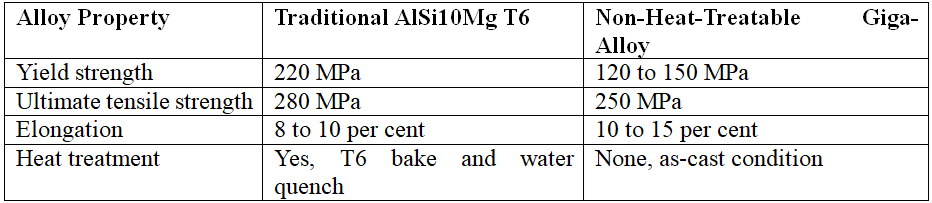
Silafont-36 (Rheinfelden Alloys) is the benchmark European giga-casting alloy. AlSi9Mg composition, copper-free, 10 to 12 per cent elongation in as-cast condition. The absence of copper eliminates the hot tearing and porosity problems that copper introduces at giga scale.
Tesla's special Al-Si alloy, mentioned in a 2021 patent, is probably an Al-Si-Mn mix with added vanadium and chromium to keep its structure stable, reaching a minimum strength of 130 MPa right after casting.
Xiaomi's Titan Metal and NIO's proprietary giga alloy reflect a growing pattern among Chinese EV makers of treating alloy chemistry as a competitive asset rather than a commodity. Both alloys remain proprietary, signaling that the Chinese EV ecosystem is building structural intellectual property at every level of the supply chain.
The iron and manganese chemistry demands close attention. The key metric is not the absolute iron content alone - it is the Mn:Fe ratio. Research from the EU's SALEMA project demonstrates that iron levels up to 0.25 to 0.26 wt% (weight percent) are tolerable in structural HPDC alloys when manganese is maintained at 0.60 wt% or above, because the Mn-rich alpha-AlFe,MnSi intermetallic dominates over the brittle beta-AlFeSi platelet phase. Optimising giga-casting alloy chemistry is a multi-element balancing act, not a single impurity ceiling (Bongiovanni, PhD Thesis, SALEMA Project, 2025).
The strontium modification story is the detail that almost no aluminium trade publication covers with technical depth. Silicon in Al-Si alloys naturally solidifies as coarse acicular flakes - hard, brittle, and randomly oriented. Each one is a pre-existing stress concentrator. Adding 150 to 200 parts per million of strontium to the melt transforms this morphology entirely, converting the acicular flakes into fine fibrous particles. The result is an elongation increase from approximately 4 per cent to 10 to 12 per cent. That single alloying addition is what makes structural giga-casting mechanically possible.
Strontium modification is not a one-time addition at the furnace. Industrial data from the SALEMA European research programme shows that strontium content can fall from over 200 parts per million in the incoming alloy ingot to below 50 parts per million in the final casting - a burn-off exceeding 75 per cent - due to oxidation losses during remelting, melt transfer, and holding (Bongiovanni, PhD Thesis, SALEMA Project, 2025). Foundries that do not account for this burn-off will produce castings with inadequate elongation and will not understand why their scrap rate is elevated.
India holds a specific opportunity within this aluminium alloy chemistry transition. Indian aluminium smelters - principally Vedanta and Hindalco - that can supply ingots with iron controlled below 0.20 wt% and certified Mn:Fe ratios are positioned to capture the structural alloy premium segment globally, rather than merely exporting commodity ingots. The SALEMA project's Mn:Fe findings make this a commercially actionable direction for India's primary smelting sector right now.
The high-vacuum HPDC imperative
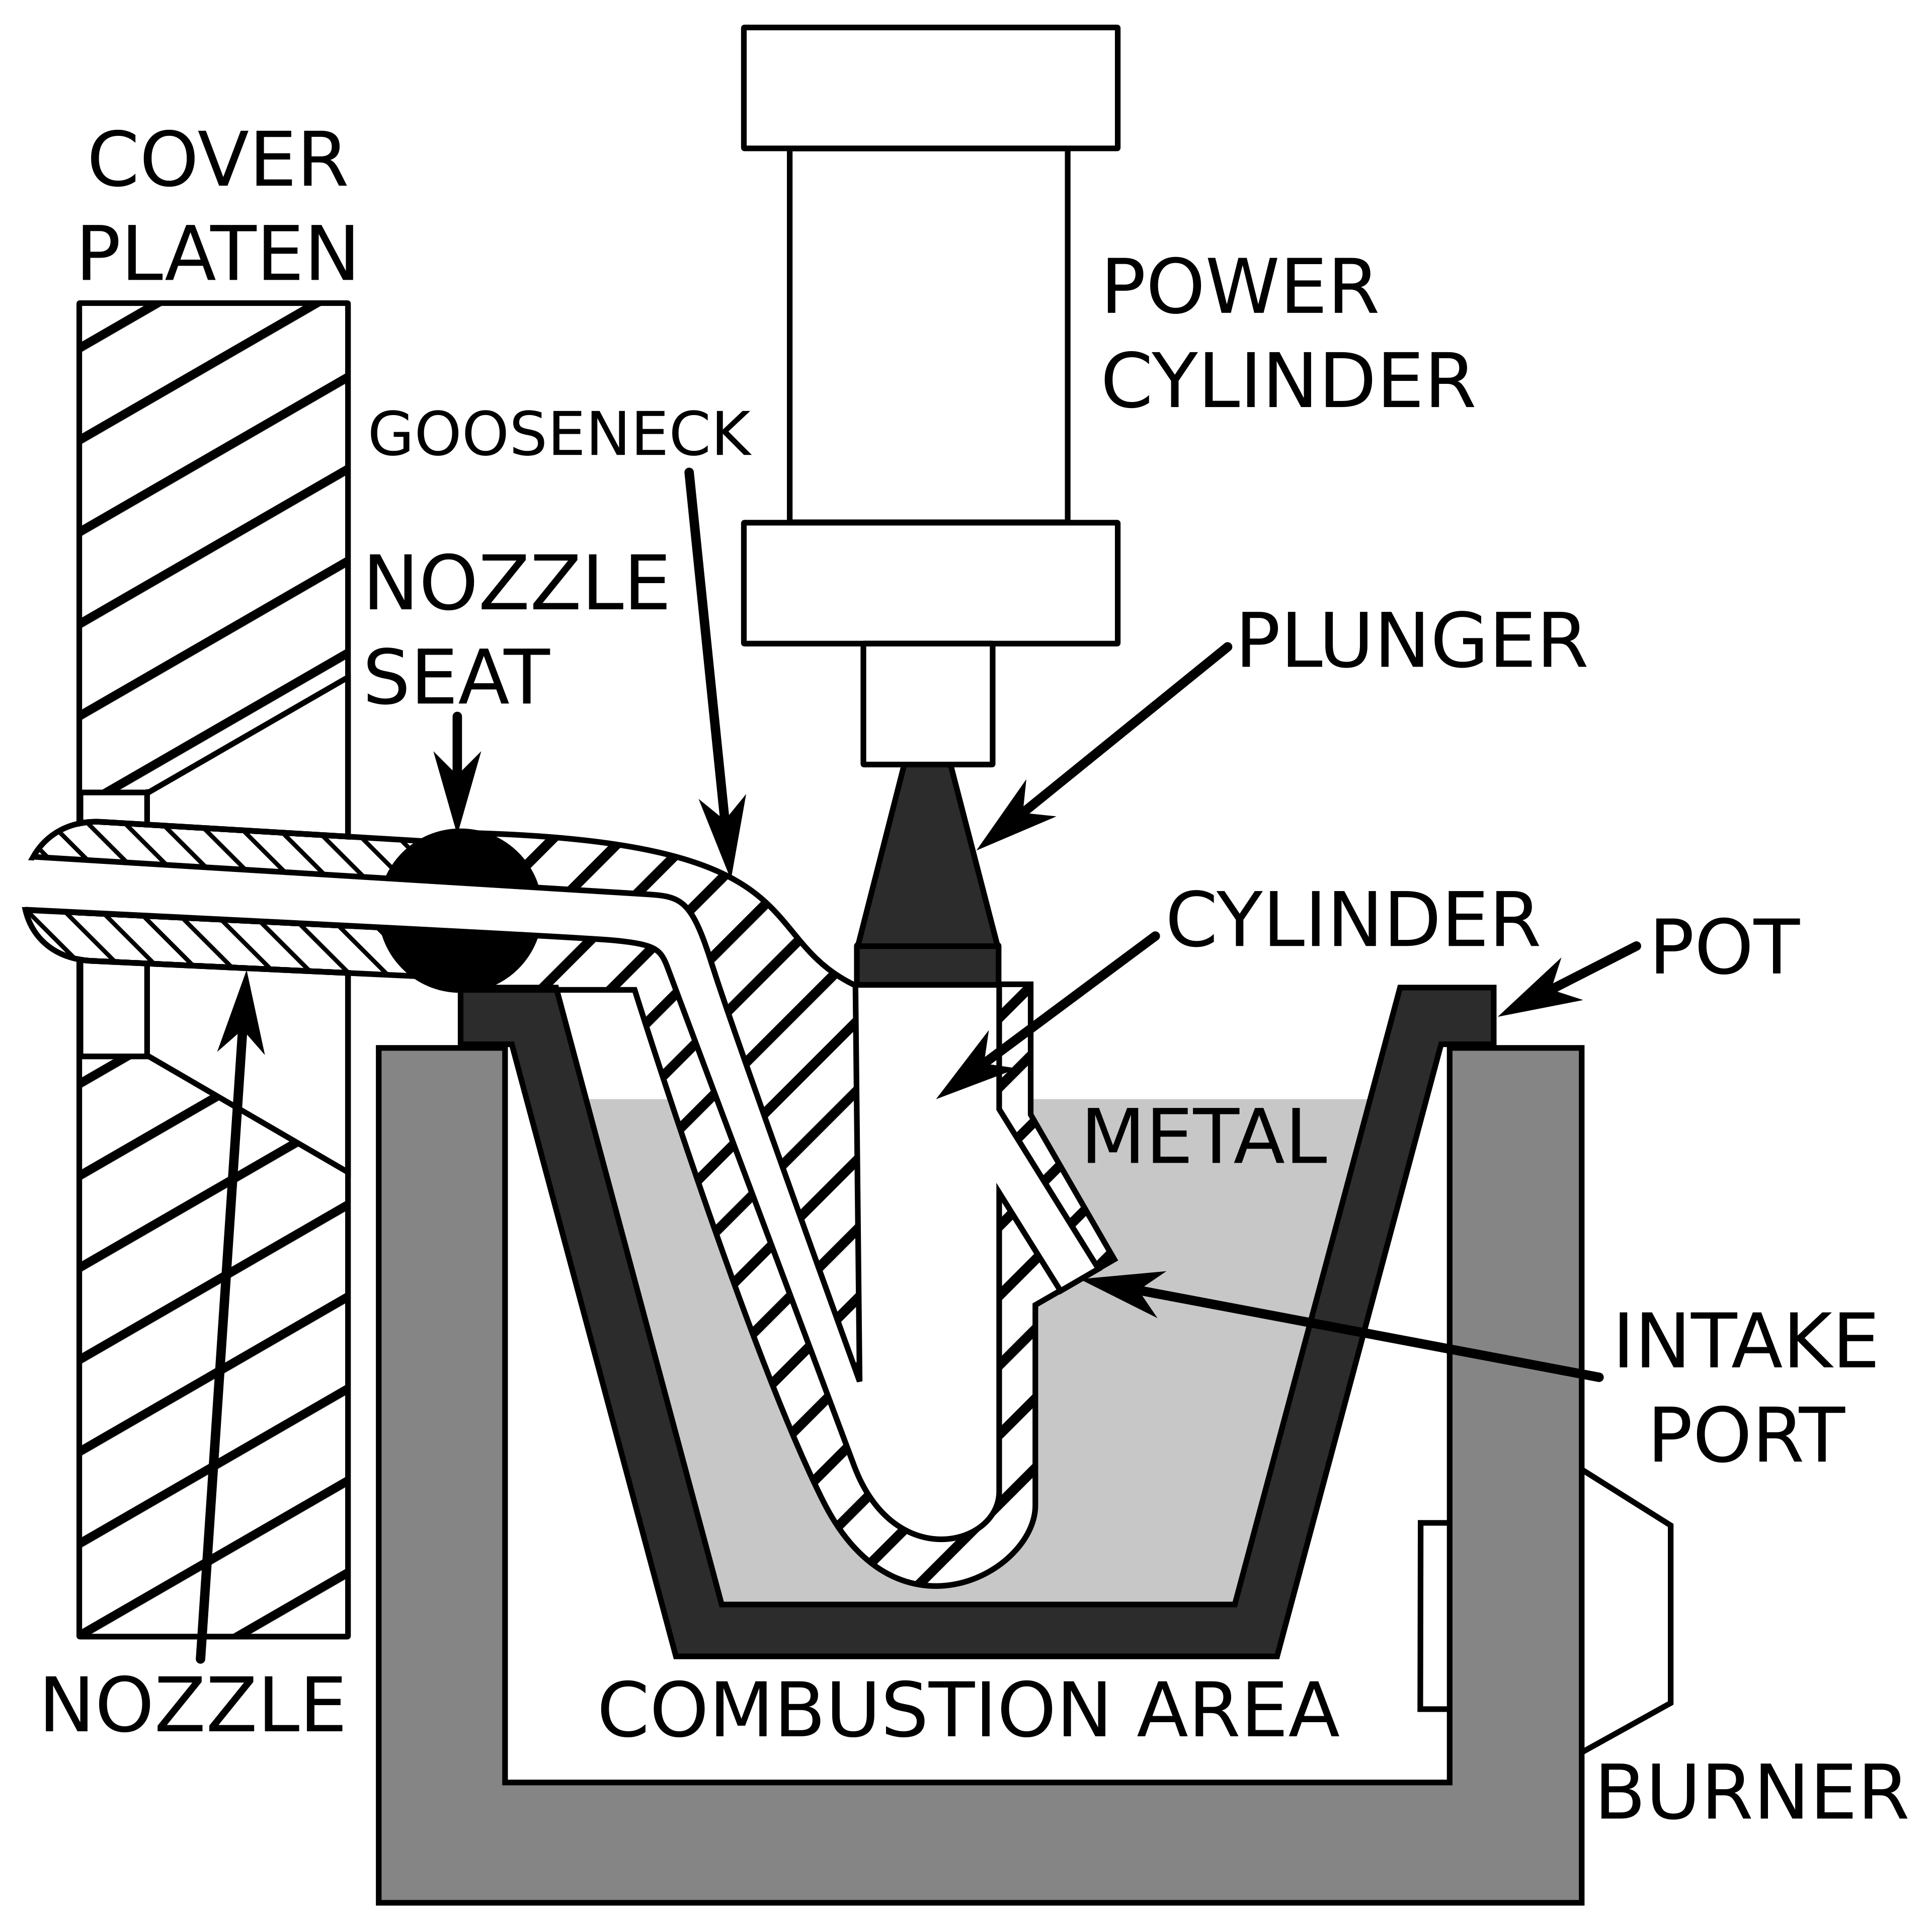
Schematic cross-section of the high-pressure die casting process. In giga-casting, molten aluminium is injected into a die cavity at injection velocities above 50 metres per second. High-vacuum systems evacuate air to below 100 millibars within 0.5 seconds before each shot. (Diagram: Wikimedia Commons / CC BY-SA 3.0)
High-vacuum HPDC evacuates air from the die cavity to absolute pressures below 100 millibars within a 0.5-second window immediately before molten metal injection. This fundamentally prevents gas porosity formation in the solidifying aluminium matrix. Research confirms that applying a 200-mbar vacuum during the casting of the AlSi10MnMg alloy reduces porosity by 60 per cent relative to conventional HPDC (Bongiovanni, PhD Thesis, SALEMA Project, 2025, citing Soares et al.). That reduction in internal voids directly improves elongation at fracture and makes the alloy viable for safety-critical structural applications.
The porosity challenge at a giga scale is more severe than in conventional HPDC. A giga-casting must fill a die cavity of 1.5 metres or more in under one second at injection velocities above 50 metres per second. At that velocity, turbulent metal flow is unavoidable. Research published in Frontiers in Materials in April 2026 by Jarfors at Jönköping University demonstrates that the controlling quality problem in HPDC is not hydrogen; it is the oxide bifilm, formed when the fill front folds back on itself during mold filling and traps a double layer of oxide skin in the casting microstructure (Jarfors, Frontiers in Materials, April 2026). At giga-casting scale, fill distances are far longer, making this problem proportionally worse.
Typical HPDC scrap rates range from 5 to 10 per cent of production. Filling-related issues account for 35 per cent of defect sources, shrinkage 20 per cent, and gas-related porosity 15 per cent (Bongiovanni, PhD Thesis, citing Bonollo et al., peer-reviewed). Research published by Wang, Coryell et al. in China Foundry (2024) measured properties at multiple locations within a real aluminium giga-casting. Ultimate tensile strength varied from 175 to 280 MPa across the same part. Elongation varied from approximately 1 to 8 per cent. Achieving consistent mechanical properties across a 1.5-metre casting is the defining technical challenge of giga-casting production.
The die itself is one of the most consequential and least discussed cost centres in the process. A giga-casting die for a rear underbody costs EUR 1.5 to 3 million and requires 6 to 12 months to design, machine, and qualify (Wang et al., China Foundry, 2024). Conformal cooling channels - manufactured by selective laser sintering of hot-work tool steel - cost EUR 200,000 to 500,000 per insert (Wang et al., 2024; Sun et al., Robotics and Computer-Integrated Manufacturing, 2026). A single giga-casting CFD simulation can involve meshes exceeding 100 million elements and require 20 hours on 192 computing units (Sun et al., Robotics and CIMS, 2026).
The aluminium demand mathematics
A Tesla Model Y rear underbody casting weighs approximately 66 to 70 kg as a finished part - confirmed by Munro & Associates teardown (April 2025), which gives the rear casting as approximately 145 pounds / 66.5 kg. With a typical casting yield of 75 to 80 per cent, each shot consumes approximately 85 to 90 kg of aluminium alloy.
At Tesla's production rate of 500,000 Model Y vehicles per year, the demand for rear underbody aluminium reaches 42,500 to 45,000 tonnes annually. The front underbody requires approximately the same amount of aluminium, around 42,500 to 45,000 tonnes per year. Total underbody giga-casting aluminium for the Model Y alone reaches 85,000 to 90,000 tonnes per year from a single alloy family.
Multiply this across every OEM committed to giga-casting by 2030 - including Toyota, Volvo, BYD, Hyundai, Ford, NIO, Xpeng, and Xiaomi - and the incremental aluminium demand attributable specifically to giga-casting technology reaches, by this publication's conservative estimate, 5 to 8 million tonnes per year. This demand does not exist today. It is entirely new, and it is exclusively for specific heat-treatment-free alloy compositions that the conventional ADC12 market does not supply.
The alloy ingot premium is commercially significant for every alloy producer reading this. According to industry estimates, that level of chemistry control commands a premium of USD 50 to 150 per tonne over standard ADC12 ingot (Yang et al., 2025). The alloy producers who achieve certification for structural giga-casting programmes will capture that margin for the life of each vehicle platform, typically 6 to 8 years.
Scrap economics - The circular loop nobody has calculated
Compressed aluminium scrap bales in a recycling facility. A single 9,000-tonne giga press generates 18,000 kg of clean single-alloy gate and runner scrap per 20-hour production day, creating a closed-loop secondary aluminium economy that requires only 5 per cent of the energy of primary production. (Photo: Wikimedia Commons / CC BY-SA 4.0)
A 9,000-tonne giga press producing rear underbodies at 45 shots per hour generates 3,150 kg of excellent castings and 900 kg of clean gate and runner scrap every operating hour. Over a 20-hour production day, that is 18,000 kg of identified, single-alloy giga-casting scrap per machine per day.
This scrap is not ordinary foundry return metal. It is clean. It comes from a single alloy. Its chemistry is precisely known. It can be directly recycled back into giga-casting alloy without complex remelting and chemistry adjustment. The OEM that operates the giga-press owns the highest-quality secondary aluminium feedstock available in its supply chain.
Recycling aluminium requires only 5 per cent of the energy needed for primary production. Approximately 75 per cent of all aluminium ever produced remains in active use today. Automotive recycling rates already exceed 90 per cent (European Aluminium Association, cited in Bongiovanni PhD Thesis, SALEMA Project, 2025). Volvo explicitly cites its mega-casting programme as supporting its carbon neutrality targets because the single-alloy scrap stream enables high recycled content without quality compromise.
As these loops tighten, the OEM's supply base progressively bypasses the conventional alloy producer who previously performed remelting and chemistry adjustment services. The opportunity lies in supplying certified giga-casting alloy ingots to OEMs and Tier 1 casters that have not yet established their own recycling infrastructure. That window is probably five years wide before the loops close permanently.
The macroeconomic lens - Three global theatres and India
Germany: The decarbonisation crucible. In Germany, giga-casting interacts with three macroeconomic forces simultaneously: high industrial power prices, strict decarbonisation mandates, and the historical concentration of automotive tooling expertise in Bavaria and Baden-Württemberg. The giga-casting die is predominantly manufactured from German and Austrian H13 hot-work tool steel, precision-machined in specialist shops at EUR 1.5 to 3 million per die (Wang et al., China Foundry, 2024). That value does not follow the press to Shenzhen. German industry is set to lead the production of large castings by selling advanced software for thermal simulations, highly accurate tool steel molds, cooling insert technology, and advanced machine control systems.
China: The dominant ecosystem. China is not adopting giga-casting. China is defining it. BYD, NIO, ZEEKR, Xpeng, and Xiaomi are running 13,000-tonne machines, developing proprietary aluminium alloys, and building alloy certification infrastructure simultaneously. LK Group owns IDRA, manufactures machines under the LK Machinery brand, and supplies giga-presses to Tesla Shanghai and BYD Shenzhen simultaneously. For non-Chinese OEMs and Tier 1 suppliers, every year without a committed giga-casting programme is a year of increasing structural cost disadvantage.
North America: The Tier 1 Window. North American adoption has been concentrated at the OEM level - Tesla, Ford, and GM - with Linamar as the only Tier 1 to have made a confirmed investment. The physical infrastructure retrofit alone - covering ceiling height upgrades, extended floor footprints, and dedicated power supply - can cost tens of millions of dollars before the press is purchased. The Tier 1 window is open but narrowing.
India: A specific and reachable opportunity
India has no operating giga-presses as of mid-2026. China has hundreds. But India holds a specific advantage that the capital bottleneck discussion tends to obscure. India's primary aluminium smelting capacity of 4.1 to 4.2 million tonnes annually - operated by Vedanta and Hindalco at near full utilisation - is a potential supply chain anchor for global giga-casting alloy producers. Indian smelters that can supply ingots with iron controlled below 0.20 wt% and certified Mn:Fe ratios can capture the structural alloy premium segment globally, rather than merely exporting commodity ingots.
India's largest Tier 1 casters are already making real investments. Jaya Hind Industries installed one of India's largest HPDC machines - a 4,400-tonne press at its Urse, Pune plant in December 2024 (Economic Times Manufacturing, December 2024; The Print/ANI, December 2024; Mobility Outlook, December 2024). Samvardhana Motherson commissioned a 5,500-tonne press at Aurangabad, as reported by industry sources. Rockman Industries processes over 65,000 tonnes of aluminium annually. These investments position Indian companies to supply the precision secondary EV components - motor housings, inverter casings, thermal management plates, and suspension brackets - that a giga-press will never produce.
The survival pivot for foundries worldwide
John Stokes, General Manager of IDRA Group, speaking to AL Circle, described the global die casting equipment industry as "a small and very conservative industry," adding, "When the dust settles, we're going to end up with maybe five or six super groups around the world."
A giga-press system costs between EUR 6 and 20 million per machine before dies, building upgrades, and power infrastructure (ANP Consulting, April 2024). Total cell investment routinely runs USD 50 to 100 million (ANP Consulting, January 2024). Technical analyses note explicitly that "high initial investments and the need for specialised infrastructure make it difficult for smaller foundries to participate" (Wang et al., China Foundry, 2024).
The mid-tier foundry that maps every component on the new EV platform and identifies the parts the giga-press physically cannot produce - the motor housing, the inverter casing, the thin-wall thermal management plate, and the sensor housings with hermetic sealing requirements - and then invests in precision HPDC, vacuum, and alloy certification capability is not disrupted. It is repositioned into a more specialised and higher-margin segment that the giga-press creates rather than destroys.
Tesla's Giga Casting 2.0 ambition is to cast all EV components as a single piece, reducing the total part count from approximately 400 to just a handful. The 20,000-tonne machine already announced will produce a complete vehicle underbody in a single shot. Based on announced specifications, the machine is expected to be approximately 30 metres long and require 30 MW of peak electrical power. The hollow subframe innovation - using 3D-printed sand cores to create hollow structural elements inside aluminium giga-castings - reduces weight by 30 per cent compared to solid casting, confirmed by Tesla's own claim and corroborated by Wang et al. (China Foundry, 2024) and Yang et al. (Journal of Alloys and Compounds, 2025).
The manager in Bavaria, revisited
Klaus Hartmann did not close his unit when the OEM letter arrived.
He spent two months mapping every component on the new EV platform. He identified 31 parts that the giga-press physically cannot produce. The motor housing. The thermal management plate. The inverter casing. Seven suspension components in two alloys. Twelve sensor housings with internal channels and hermetic sealing requirements.
His 22 displaced components generated EUR 2.1 million in annual revenue. His 31 new target components represent EUR 5.4 million.
He also changed his alloy supply protocol. He asked his aluminium alloy supplier for strontium assay data across the full melting cycle, not only on the incoming ingot certificate. He now knows that Sr burn-off from ingot to final casting can exceed 75 per cent in industrial production - and that his structural castings' elongation depends on what is in the die, not what was printed on the delivery document (Bongiovanni, SALEMA PhD Thesis, 2025).
He invested in a vacuum HPDC upgrade on one existing line. He contracted alloy certification testing for an Al-Si-Mg composition with a controlled Mn:Fe ratio. He submitted qualification samples to two OEM procurement teams.
Giga-casting did not destroy his business. It forced it to become better.
The winners of this decade will not be the companies that simply secure financing to buy the largest presses. They will be the metallurgical experts who control aluminium solidification across a two-metre span, the die makers who machine conformal cooling into 80 tonnes of hot-work tool steel, and the foundries that understand precisely which work the giga-press cannot do - and make themselves indispensable for all of it.
To be continued. Part 3 of this series named "Giga-Casting: The aluminium shot" will address the harder question: which foundries, alloy makers, and Tier 1 suppliers will survive the reset and which ones will be left behind when the structure is no longer the business?
Disclaimer: The opinions, information, claims, references, and images presented here are those of the author alone and AL Circle holds no responsibility.
Unlock full access – sign up for FREE.
Key benefits
Victura Group names automotive lighting industry veteran Vineet Sahani as CEO
Next articleCapral Aluminium expands Victorian footprint through new Geelong facility
Grow with
AL Circle












_md.webp)