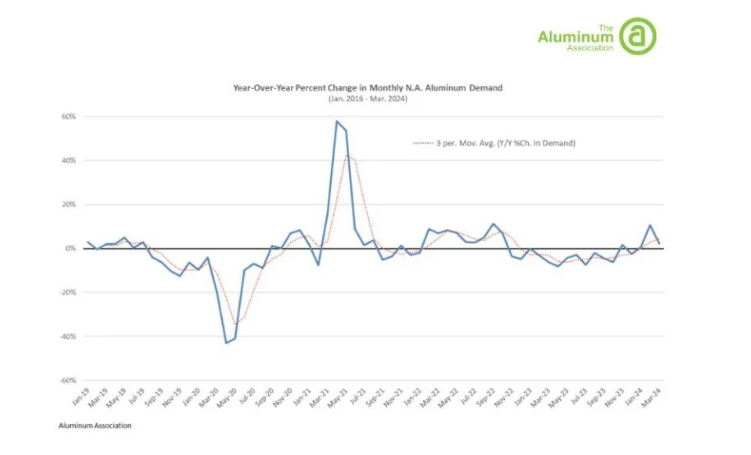
Aluminium demand in North America, stemming from the automotive, aerospace, construction, and packaging industries, is undergoing an upward movement, fuelled by a concerted move towards sustainability by manufacturers. The aluminium industry in North America is categorised by product type and end-user sectors. Aluminium castings, primarily serving the transportation sector, lead in demand among all product types, followed by flat-rolled products supporting the packaging industry.
According to AL Circle’s report “Global Aluminium Industry Outlook 2024,” North America accounted for approximately 21.5 per cent of the global aluminium flat-rolled product use and 8.25 per cent of extrusion use in 2023.
In the first quarter of 2024, North America, including the United States and Canada, witnessed a 4.3 per cent year-on-year growth in aluminium demand, found the preliminary data of the Aluminium Association. The demand rebounded in Q1 2024 after a 3.9 per cent drop last year, while it stayed strong in 2022.
Charles Johnson, president & CEO of the Aluminum Association, said: “Domestic aluminium demand is rebounding so far this year amidst continued interest from our customers and end consumers in more sustainable, recyclable material options. We continue to believe that the North American region – and the United States in particular – is one of the best places in the world to make and use aluminium. The ongoing investment and demand we are seeing appear to agree.”
The Aluminium Association has pointed out that aluminium demand, including domestic and imported metal, in the United States and Canada totalled 6,955 million pounds during the first three months of 2024, compared to the previous year’s demand of 6,666 million pounds.
The Aluminium Association also highlighted that a substantial portion of demand stemmed from domestic orders, which grew by 4.8 per cent annually till April 2024, based on Net New Orders of Aluminum Mill Products index (baseline index 100). Total semi-fabricated or mill product demand rose five-tenths of one per cent year-over-year.
Overview of import, export & shipments
Through March 2023, primary aluminium ingot shipments rose 16 per cent Y-o-Y, while sheet and plate shipments increased by 6.1 per cent. But in contrast, foil shipments plunged by 19.2 per cent and extruded product shipments decreased by 5.4 per cent on an annual basis.
Concerning imports, North America’s unwrought aluminium and semi-fabricated aluminium product imports also fell 13.5 per cent Y-o-Y through April 2024. But exports of aluminium ingot and mill products climbed up year-on-year by 36.6 per cent, totalling 769 million pounds.
The above data indicates that North America’s domestic shipments and exports increased through the first quarter of 2024, compared to imports, suggesting the fact that its production loomed higher than the demand. This observation is further supported by the hike of the United States’ exports. From January to March 2024, the United States aluminium exports (including scrap) amounted to 854,000 tonnes, up by 9 per cent from 778,000 tonnes during the corresponding period of the previous year.
Aluminium production trend
From January to May 2024, North America’s primary aluminium production totalled 1.667 million tonnes, reflecting an escalation of 4.97 per cent from 1.588 million tonnes during the same period of the previous year.
This hike was sustained with annual increases each month through the year-to-date period. In January, February, and March, North America’s primary aluminium output expanded by 5.6 per cent, 8.9 per cent, and 4.6 per cent year-on-year to amount to 339,000 tonnes, 318,000 tonnes, and 341,000 tonnes, respectively. North America’s production in March 2024 stood the highest in five months of 2024, as the output in April and May came in at 331,000 tonnes and 338,000 tonnes, respectively. The April and May output also recorded a Y-o-Y increase of 3.44 per cent and 2.74 per cent, respectively.
Throughout the first five months of 2024, North America maintained an average daily production at 11,000 tonnes, up from 10,500 tonnes recorded during the corresponding period in 2023.
This noticeable growth in North America’s primary aluminium production has been resulted from substantial manufacturing investments over the last decade. The Aluminium Association has noted that its member companies have collectively announced more than $10 billion in investments for domestic production, with $200 million earmarked for US manufacturing in 2024 alone.
This investment surge is backed by anticipated demand growth for sustainable packaging, eco-friendly buildings, lightweight vehicles, and greener infrastructure. With sustainability as a backbone of future aluminium demand, the Aluminium Association has composed a report, Pathways to Decarbonization: A North American Aluminium Roadmap, outlining the theoretical roadmap to achieve 2050 net-zero goals.