LME aluminium price pulls back rapidly before the holiday, then recovers from lows: Why did it fall below USD 3,150 per tonne?
The image used in this article is taken from SMM's official website
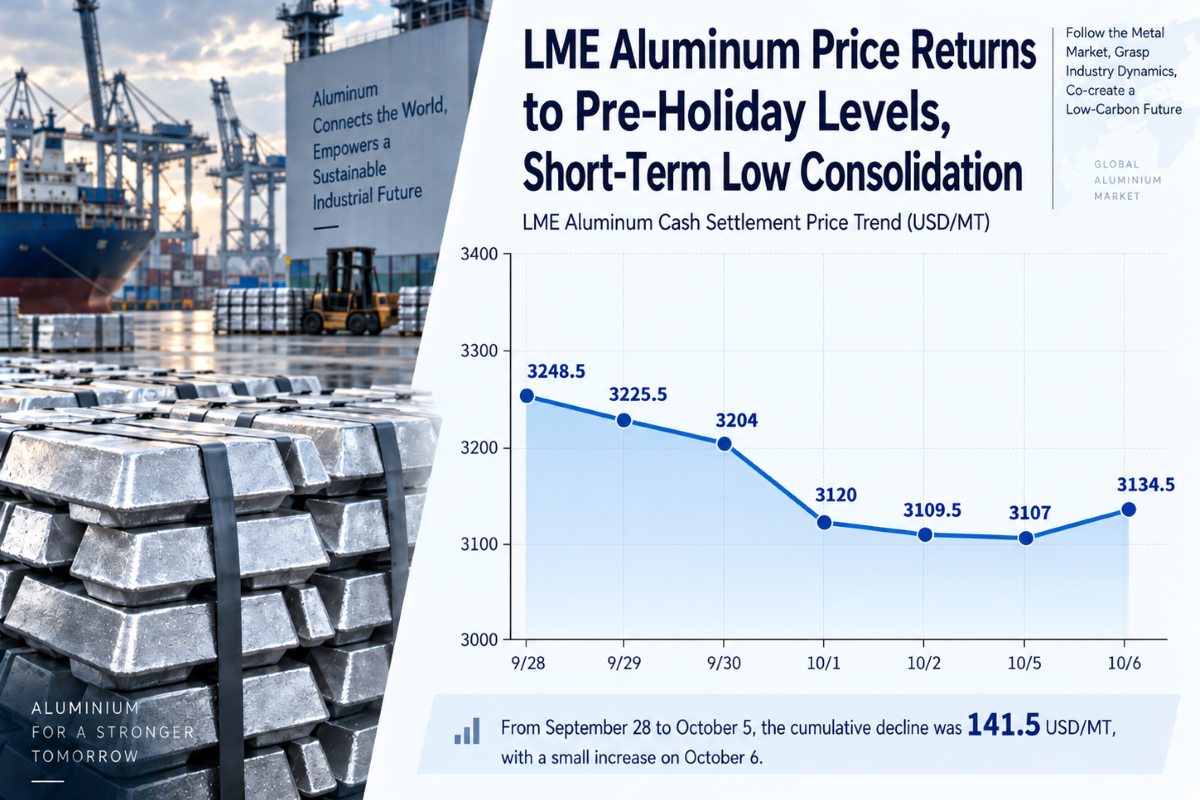
Since late September, LME aluminium prices ended their previous trend of fluctuating at highs and underwent a notable pullback around China’s National Day holiday. The LME spot aluminium settlement price fell from USD 3,248.5 per tonne on September 28 to USD 3,204 per tonne on September 30, with the decline accelerating further in October. It dropped USD 84 per tonne in a single day on October 1 to USD 3,120 per tonne, and fell further to USD 3,109.5 per tonne on October 2. As of October 5, the LME spot aluminium settlement price had declined to USD 3,107 per tonne, a cumulative drop of USD 141.5 per tonne from September 28, or about 4.36per cent. Compared with the previous staged high of around USD 3,350 per tonne, the cumulative pullback exceeded USD 240 per tonne, a decline of about 7per cent. On October 6, the LME spot aluminium settlement price rebounded slightly to USD 3,134.5 per tonne, up USD 27.5 per tonne from the previous trading day, but remained significantly below the earlier high.
LME aluminium prices pulled back for consecutive sessions before the holiday, with the decline accelerating further in early October
In terms of price pace, this round of correction can be roughly divided into two stages.
The first stage occurred before the National Day holiday. From September 28 to September 30, the LME aluminium spot settlement price fell from USD 3,248.5 per tonne to USD 3,204 per tonne, a cumulative decline of USD 44.5 per tonne over two trading days, or about 1.37per cent. Against the backdrop of LME aluminium prices having previously run above USD 3,300 per tonne, the willingness to rush to buy amid continuous price rise at high levels began to weaken, and some bulls chose to take profits. Meanwhile, as the National Day long holiday approached, domestic spot purchasing gradually turned more cautious, and market attention on whether traditional peak-season demand could continue to materialise increased notably.
The second stage occurred in early October. On October 1, the LME aluminium spot settlement price fell USD 84 per tonne in a single day, or about 2.62 per cent, marking the most pronounced single-day pullback during this correction. Prices subsequently dipped further to around USD 3,100 per tonne and remained at low levels from October 2 to 5.
Overall, from September 28 to October 5, LME aluminium prices pulled back by more than USD 140 per tonne cumulatively in just a few trading days, reflecting that the risk premium accumulated at earlier highs and bullish sentiment were cooling rapidly.
Geopolitical risk premium was given back, and earlier supply concerns cooled somewhat
A key driver behind the previous rapid rise in LME aluminium prices was the persistent geopolitical risk in the Middle East and the resulting supply concerns.
Since the beginning of this year, changes in the Middle East situation have at times significantly disrupted global aluminium supply expectations. The Gulf region is a major global production and export hub for primary aluminium, and the market had been closely watching shipping risks in the Strait of Hormuz, energy supply, and the operating conditions of local smelters, which significantly elevated the supply risk premium. However, as some production and logistics links gradually recovered, market concerns over extreme supply deficits began to cool, and part of the price premium previously driven by supply disruption expectations was given back. Therefore, this round of decline in LME aluminium prices cannot be simply attributed to a single geopolitical factor, but should rather be understood as a shift in the market’s assessment of supply risks.
What the market had previously been trading was:
- whether supply would be further disrupted.
- What the market is now focusing more on is:
- how quickly the previously disrupted supply can recover, and when new supply will be released.
- As this trading logic shifted, part of the risk premium previously embedded in aluminium prices was gradually squeezed out.
- The strong US dollar and high interest rate environment continue to weigh on nonferrous metal valuations
Beyond geopolitical factors, the macro funding environment is also a key reason for this round of LME aluminium price correction.
From late September to early October, long-term US Treasury yields stayed at relatively high levels, and the US dollar remained broadly strong, exerting pressure on dollar-denominated commodities. Since LME aluminium prices had already experienced a substantial rally, the willingness of funds to keep chasing base metals higher declined as the dollar strengthened and interest rates stayed high. Some earlier profit-taking funds chose to exit, further amplifying the price pullback. At the same time, the high interest rate environment continued to suppress global manufacturing and end-use demand expectations to some extent. For a commodity like aluminium, which has both financial and industrial attributes, prices are more prone to high-level corrections when the macro funding environment weakens and spot demand does not clearly beat expectations.
However, after October 6, the dollar’s upward momentum weakened somewhat, and market expectations for further US interest rate hikes also cooled, easing macro pressure in stages. This partly explains why LME aluminium prices began to see a modest recovery after falling to around USD 3,100 per tonne.
Therefore, short-term prices are effectively influenced by two opposing forces:On one hand, high interest rates and the earlier dollar strength continue to weigh on commodity valuations; on the other hand, after the rapid and sustained decline, LME aluminium prices themselves have some technical repair demand as the dollar’s rally slows.
China’s “September peak season" demand fell short of expectations, passively dragging on LME aluminium to some extent
Entering September, China's "September-October peak season" demand improvement fell short of earlier expectations. Downstream buyers mainly made just-in-time procurement, and high prices dampened spot transactions, putting domestic aluminium prices under pressure. The settlement price of the front-month SHFE aluminium contract fell from RMB 24,225 per tonne on September 24 to RMB 24,035 per tonne on September 29.
As a major global aluminium consumer market, China’s weakening demand expectations also passively dragged on LME aluminium to some extent. However, LME aluminium’s correction over the same period was notably larger than SHFE aluminium’s, indicating that China’s demand was not the dominant factor in this round of LME aluminium decline.
In contrast, the more pronounced pullback in LME aluminium was mainly driven by a combination of factors, including a strong US dollar, the high interest rate environment, the unwinding of earlier geopolitical and supply risk premiums, and insufficient support for high prices from overseas physical demand. At the same time, visible inventory outside China remains at relatively low levels, suggesting that this round of decline reflects a repricing of future supply-demand dynamics and valuations rather than an obvious surplus already emerging in the spot market.
The overseas secondary aluminium market also did not see significant rush buying amid continuous price rise
In the overseas secondary aluminium market, the rapid rise in primary aluminium prices has not been fully transmitted to the aluminium scrap and secondary aluminium spot markets.
Currently, in some parts of Asia, the available supply of used beverage cans (UBCs) is relatively ample. Affected by factors such as labor disputes at some large aluminium enterprises in South Korea, inventories of some used beverage cans in the Japan and South Korea markets have increased, and suppliers are more willing to seek overseas sales channels. Meanwhile, transactions for mixed aluminium casting scrap and other grades remain relatively slow, with notable differences in price expectations between some buyers and sellers.
In terms of secondary aluminium alloy, downstream die-casting enterprises also have relatively limited capacity to accept high-priced alloy ingots. Especially with no significant better-than-expected growth in end-user orders for automobiles, motorcycles, and other die-casting products, secondary aluminium enterprises find it difficult to smoothly pass on the full increase in raw material costs downstream.
Therefore, although primary aluminium prices rose rapidly earlier, the aluminium scrap and secondary aluminium markets did not experience a demand expansion of the same magnitude. This means that a certain degree of divergence has gradually emerged between earlier financial market gains and the actual spot market, which also weakened the foundation for further price increases.
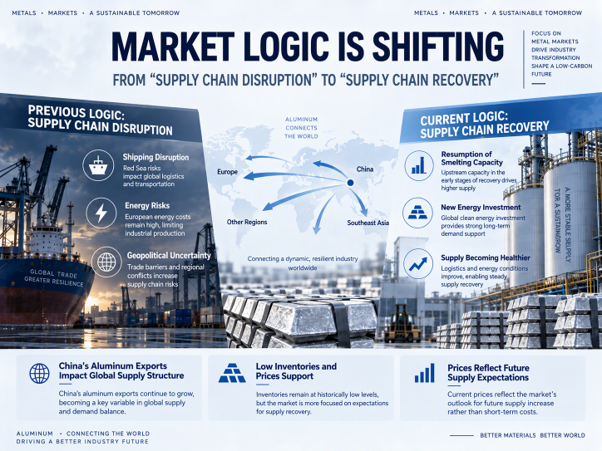
The market is shifting from “supply disruption trading” to “supply recovery trading”
Compared with the current immediate supply and demand situation, what deserves more attention in the recent LME aluminium market is that capital is repricing supply expectations for the coming months. After the earlier escalation of geopolitical conflicts, the market mainly focused on supply disruptions in the Middle East, shipping obstructions, and metal shortages in European and US markets. However, as high aluminium prices have persisted for a considerable period, some smelting capacity that had previously cut production due to high costs, energy issues, or insufficient profitability has regained the economic conditions to resume production. Meanwhile, new aluminium capacity projects in Asia and the Middle East are also becoming a key focus of market attention.
Among them, Indonesia has continued to attract investment in the aluminium industry chain in recent years. With the successive construction of local alumina, aluminium, and supporting energy projects, the future supply structure of aluminium in Asia still has the potential for further changes. Besides Indonesia, aluminium smelting projects in the Middle East, Central Asia, and other emerging markets are also steadily advancing. Therefore, the core trading logic of the aluminium market is currently undergoing a relatively notable shift: previously, the market traded more on "where supply disruptions might occur,” whereas now it is increasingly trading on “which supplies can recover, and which new capacity is about to be released.”
The impact of this shift on prices is very important, because even if the spot market has not yet shown a clear surplus, as long as the market believes that supply pressure will ease in the coming months, financial prices may react in advance.
Changes in China’s aluminium semis exports and global trade flows warrant continued attention
Beyond the recovery in primary aluminium supply, China’s exports of aluminium products are another variable that cannot be ignored in the future global supply-demand balance. When domestic demand recovers at a relatively mild pace while aluminium processing enterprises maintain high production levels, more aluminium semis may enter the international market through exports.
With aluminium prices and regional premiums in markets outside China still at elevated levels, changes in the competitiveness of China’s aluminium semis exports and the export profit window will directly affect the supply actually available in the international market. Therefore, for aluminium prices outside China going forward, what needs attention is not just how much aluminium the world has produced, but which markets these metals and aluminium semis ultimately flow to.
In recent years, aluminium trade flows among North America, Europe, the Middle East, and Asia have been affected by multiple factors including tariffs, regional premiums, energy costs, and geopolitical risks. When price differentials between different regions widen, metal tends to flow to markets with higher profits.
Low inventory has not stopped LME aluminium prices from falling; the market is now trading the future direction of supply and demand
Notably, this round of price pullback has not been built on a significant increase in global visible inventory. Currently, visible aluminium inventory outside China remains at relatively low levels overall, which means that from the perspective of immediate supply and demand, the market has not yet seen a very obvious spot surplus.
By conventional logic, low visible inventory usually means spot supply is still tight and should provide some support to LME aluminium prices. But this price performance shows that: low inventory does not necessarily mean prices cannot fall.
Financial markets are trading not just how much aluminium is in warehouses today, but more importantly how the supply-demand balance may change over the next three months, six months, or even longer. If the market begins to expect a gradual recovery in Middle East supply, an increase in capacity outside China, and continued inflows of Chinese aluminium products into the international market, while end-use demand growth does not accelerate at the same pace, then capital may move early to reduce its pricing of future supply tightness.
In other words, a fairly notable shift is now emerging in the market:the physical market may not yet be in surplus, but prices have already begun to price in the possibility of a marginal loosening in future supply and demand ahead of time.
After falling to around USD 3,100 per tonne, prices saw a short-term recovery from lows
Looking at the latest prices, after the sharp decline on October 1, the downward momentum of LME aluminium prices has slowed somewhat. On October 2, the LME spot aluminium settlement price was USD 3,109.5 per tonne, and on October 5 it was USD 3,107 per tonne, with prices over the two days basically holding near USD 3,100 per tonne; by October 6, prices rebounded toUSD 3,134.5 per tonne.
On one hand, after the previous continuous sharp decline, some bearish funds chose to take profits, and some buying support began to emerge near USD 3,100 per tonne. On the other hand, as the US dollar eased from its earlier strength, macro pressure on LME aluminium prices also diminished in stages.
However, it is more appropriate to interpret this move as a low-level repair after a rapid pullback, rather than confirmation that a new upward trend has formed. In particular, on October 7, the Chinese market was still in the National Day holiday period, and domestic spot trading and downstream procurement had not yet fully resumed, so real demand in the Chinese market still needs further verification after the holiday.
Market outlook: LME aluminium prices are entering a phase of supply-demand repricing.
Overall, this round of LME aluminium’s rapid pullback from above USD 3,300 per tonne to near USD 3,100 per tonne was not driven by a single factor.
From a macro perspective, high interest rates, the earlier strengthening of the US dollar, and profit-taking by fundsjointly pressured nonferrous metals.
From a geopolitical perspective, as some supply risks eased, the risk premium accumulated earlier began to unwind.
From the demand side, the actual improvement in China’s traditional peak-season demand did not fully meet earlier expectations, and downstream procurement became more cautious in a high-price environment; overseas aluminium scrap and secondary aluminium markets also did not show sufficiently strong momentum to chase prices higher.
At the same time, market expectations on the supply side are also shifting.
Middle East supply is gradually recovering, some overseas smelting capacity may resume production, and new aluminium capacity in regions such as Indonesia continues to advance, causing the market to shift from the previous “supply disruption pricing” toward “supply recovery pricing”.
What is more noteworthy is that this correction occurred against a backdrop of still relatively low visible inventory outside China.
Therefore, the current decline in LME aluminium prices does not entirely mean that the physical market has already shown a clear surplus, but rather reflects financial markets’ early trading of marginal improvement in the future supply-demand balance.
In the short term, after the continuous decline, support has emerged near USD 3,100 per tonne. But whether LME aluminium prices can rebuild sustained upward momentum still depends on fundamental changes after the National Day holiday.
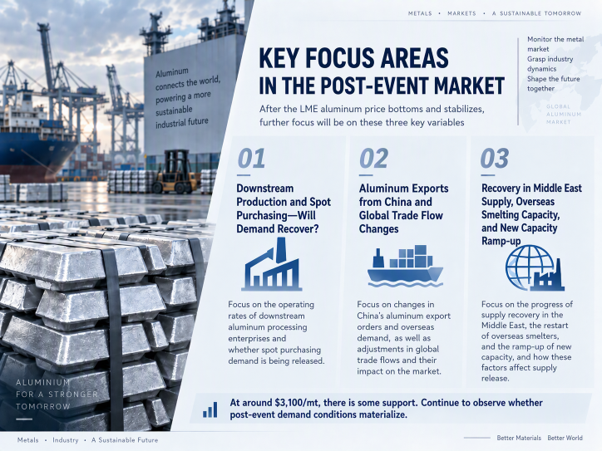
Going forward, the market will focus on three aspects:
- whether downstream operating rates and spot procurement in China can clearly recover after the National Day holiday;
- whether China’s aluminium semis exports and global regional trade flows continue to increase effective supply in markets outside China;
- the actual pace of Middle East supply recovery, production resumptions at overseas smelters, and the release of new capacity in regions such as Indonesia.
If downstream orders and spot aluminium purchases improve significantly after the holiday, while the pace of supply recovery outside China falls short of market expectations, the current relatively low visible inventory could once again become an important support for LME aluminium prices.
Conversely, if actual demand recovery remains weak while expectations for supply-side improvement are gradually realised, the market may continue to digest the price premium previously driven by supply risks and elevated sentiment.
Overall, LME aluminium prices are now transitioning from the earlier single-focus supply risk trade into a phase of repricing macro factors, demand, supply recovery, and global trade flows. In the short term, prices are likely to remain highly volatile, and the actual pace of post-holiday consumption recovery will serve as a key observation window for the market to determine whether this pullback is a temporary correction or the beginning of a further downward shift in the price center.
Note: This article has been shared by SMM and has been published by AL Circle with its original information without any modifications or edits to the core subject/data.
Grow with
AL Circle