04 DECEMBER 2014LUISS University-FACE Press Release
The EU import tariff on primary aluminium costs billions of Euros to downstream SME's
Edited by : AL CIRCLE
3 min read

The first-ever economic study on the downstream EU aluminium industry conducted by LUISS University in Rome unveils the magnitude of the damage inflicted on EU SME's and the unfair competitive advantages given to EU and extra-EU producers by the current import tariff regime and the financial diversions it permits.
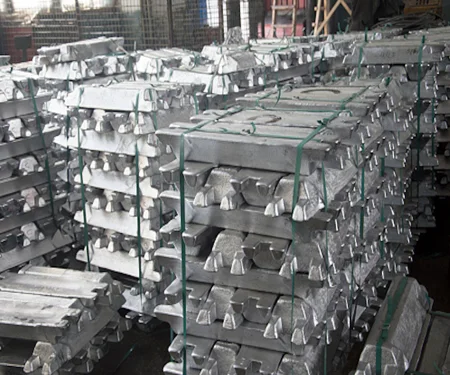
The maintaining by the European Union of an economically unjustified import duty on primary aluminium has imposed up to 15.5 billions Euros additional costs to downstream aluminium SMEs in the past fourteen years, seriously impinging on their competitiveness, and has allowed producers of this metal in and outside Europe to cash-in important artificial benefits to the detriment of the competitiveness of the EU aluminium industry. This extra-cost is due to the fact that all producers of primary aluminium artificially include an equivalent of the value of the 6% import duty on all the metal sold into the EU, irrespective of its origin.
The LUISS Study is the first ever comprehensive analysis of the EU downstream aluminium industry, which represents around 90% of the EU aluminium industry's workforce. Conducted with the support of the Federation of Aluminium Consumers in Europe (FACE), one of its key findings is the estimate of the cumulated cost incurred by EU downstream firms imposed by the EU import tariffs on primary aluminium over the period 2000-2013.
According to four different scenarios considered, the cumulated cost of the import tariff borne by downstream firms is estimated to be between €5.5 billion and €15.5 billion.
Only a marginal share of such an amount is actually collected by EU Customs. The remainder constitutes extra revenues for EU and extra-EU firms, typically big and vertically integrated. Primary aluminium tariffs artificially inflate the costs of semi-finished and finished aluminium products and, combined with the increasing competitive pressure stemming from extra-EU producers, progressively endangers downstream firms based in the EU, thus weakening the international competitiveness of the entire EU aluminium value chain. The study strongly recommends the suppression of the duty on primary aluminium imports, for several reasons:
• EU is already largely dependent on primary aluminium imports and domestic production capacity can cover only 45% of the EU apparent consumption of primary aluminium;
• EU trade policy is harming the competitiveness of the heart of the EU aluminium industry, as downstream activities (extruding, rolling and casting) currently employ more than 90% of the total workforce in the EU aluminium industry;
• The effects of the duty contradict the spirit of the Lisbon Treaty. EU trade policy is limiting economic initiatives in downstream aluminium activities, penalising SMEs and explicitly favouring big vertically integrated producers.
Unlock full access – sign up for FREE.
Key benefits
Find exclusive data-driven insights and in-depth analysis
Get our daily newsletter delivered straight to your inbox
Access real-time and historical price trends from global indices
Post and respond to latest business leads
Stay ahead with alerts on learning tools
...and so much more!SIGN UP / LOGIN
Previous article
Ford plants get ready to churn out the much-awaited F-150s
Next articleAluminum in automotive to encourage paintless dent removal policies
Grow with
AL Circle