Fxstreet.com
Idling high-cost secondary smelting capacity would benefit entire supply chain - Beck Aluminum
Edited by : AL CIRCLE
3 min read
The near-term demand picture for the US secondary aluminium industry looks relatively bright while the transport end-markets continue to show strength beyond expectations, Scott Beck, president of Beck Aluminum, said.
Still, the sector faces numerous challenges, including smelter overcapacity, tightening spreads and general economic uncertainty.
“For the most part, we're cautiously optimistic, especially about 2014, but there are headwinds that we have to overcome and structural imbalances that need to be addressed,” Beck said at the Cru North American Aluminum Trends conference.
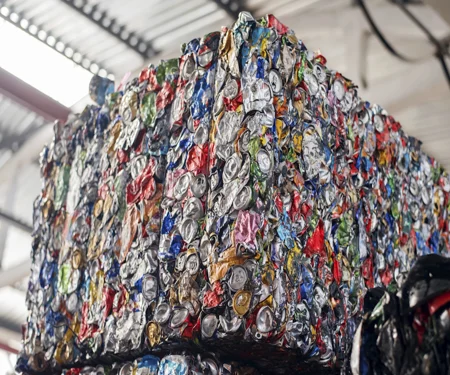
Beck sees scrap continuing to displace primary metal as feed for cast houses and foundries because it costs 10-20 percent less, he said.
“Recycled aluminium consumes only five percent of the energy and produces 90 percent fewer emissions than primary aluminium smelting,” he added. “This means there will be far more competition for every pound of scrap.”
“Also, exports to China have increased ten-fold since 2000. This export option has placed a new floor on scrap prices and makes for a smaller pie for everyone else in America,” he added.
But spread compression is by far the biggest problem facing scrap smelters today, Beck said, noting that the differential between A380 die cast alloy and high grade auto shreds, which are used to make A380, dropped to 18.25 cents in the fourth quarter of 2012 from 33.25 cents in the fourth quarter of 2011.
Additionally, the difference between 356 aluminium casting alloy and wheel scrap has fallen to just 15 cents in January this year from 25 cents in February 2011, he added.
“Ours is an industry of overcapacity, where secondary smelters are competing aggressively for both sales and scrap,” Beck said. “The more costly, less efficient capacity should be idled or closed, which would allow those who remain to raise prices, increase margins and thrive.”
There are over 300 million pounds per year of secondary smelter capacity in America today, while another 300 million pounds per year has either been idled or shut down completely in recent years, Beck said. Additionally, aluminum’s share as a percentage of curb weight is expected to increase to 11 percent in 2020 from about nine percent today. That would equate to more than 500 pounds of aluminium per vehicle at the end of the decade, up from 343 pounds in 2012, according to Ducker Research.
“Automotive demand growth for aluminium castings and rolled products will continue over the next decade. The average car today is over 11 years old and 20 percent of the fleet has been on the road for over 16 years. We will see further penetration, especially in light trucks, while engineers are designing aluminium-intensive blocks, heads, suspension components and power-train applications,” Beck said.
But while car and wheel markets are doing well, the rest of the casting industry - the producers of motors in tractors, drilling equipment, combines and connectors all share a lack of confidence in the economy and the US government, he cautioned.
Previous article
Transnet targets BHP’s aluminium smelters
Next articleChinese aluminium scrap price spikes
Grow with
AL Circle