Government policies and subsidies have been instrumental in fostering the growth of the electric vehicle market. However, as these incentives are phased out and policies evolve, the public will increasingly shape the future market adoption trajectory.
As electric vehicles (EVs) become increasingly common on roads, the number of charging points is also rising. This trend is expected to continue as nations strive to reduce emissions in alignment with net-zero goals and internationally agreed temperature targets.
The United States recently introduced more stringent national pollution standards for passenger cars and light-medium vehicles. These standards mandate a 56 per cent reduction in tailpipe pollution and vehicle carbon emissions by 2032, based on 2026 levels. While this doesn't explicitly ban internal combustion engines, meeting these standards will necessitate a significant increase in EV production. Despite the United States seeing EV sales surpass 1 million units annually for the first time in 2023, they still only represent 7.2 per cent of all new light vehicles sold.
While the US announcement is a step in the right direction, it falls short of the measures taken by some other nations. For instance, the European Union has already implemented a ban on the sale of new petrol-powered cars starting in 2035, in line with the revised UK policy, which was pushed back from its initial 2030 deadline. This EU law, ratified in February 2023, initially faced resistance but eventually allowed for internal combustion engine vehicles that exclusively use e-fuels, synthetic carbon-neutral fuel.
However, it is subject to review in 2026. There are concerns that slower-than-anticipated growth in electric vehicle sales could prompt legislators to reconsider or postpone the ban on internal combustion engine vehicles.
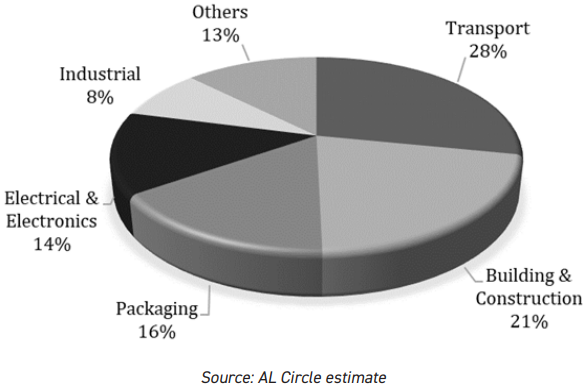
Passenger cars are the single largest user segment of aluminium amongst other transport sectors, with the rise of EVs also playing a crucial role. In 2023, the transportation sector accounted for the major share, 28 per cent, followed by the building and construction sector, 21 per cent.
Global aluminium usage across end-user sectors, 2023 (000 tonnes)
Total usage: 97.8 million tonnes
Aluminium usage in the transportation sector stood at 27.5 million tonnes in 2023. The demand is likely to reach 28.2 million tonnes in 2024. Discover insights into the diverse applications of aluminium across global industries in the comprehensive report "Global Aluminium Industry Outlook 2024." Access your copy now to delve deeper into the nuanced landscape of aluminium utilisation across sectors worldwide.
In 2022, battery electric vehicles (EVs) and plug-in hybrid vehicles globally constituted 14 per cent of all new car sales, amounting to 10.2 million units, in contrast to 62.66 million non-EV sales. Notably, certain countries such as Norway (88 per cent) and Sweden (54 per cent) exhibited remarkably high levels of EV sales. Norway's significant shift to EVs stemmed from tax incentives, including purchase and registration discounts and reduced toll charges. Moreover, Norway's reliance on hydroelectric power ensures minimal overall emissions from EV usage.
China also experienced substantial growth in EV adoption, with 29 per cent of new vehicles sold in 2022 being EVs. This growth is attributed to China's substantial investment in battery technology, particularly lithium iron phosphate batteries. Companies like CATL have secured a dominant 37 per cent market share in the EV battery segment by offering more affordable yet effective products, even though their driving range may not match traditional lithium nickel manganese cobalt batteries.
Despite dropping EV prices, advancements in battery technology, and the expansion of charging networks, subsidies and incentives alone may not drive widespread adoption. Consumer behaviour, along with the manufacturers, policymakers, and societal influences, will play pivotal roles. Challenges such as range anxiety and the availability of charging infrastructure can be addressed through concerted government and private sector investments. For instance, the UK witnessed a 43 per cent growth in its charging network in 2023, while the United States allocated US$5 billion in its 2022 Infrastructure Bill to bolster nationwide charging infrastructure.
As of 2022, EVs constituted a mere 2 per cent of the global car fleet. However, if the exponential sales growth observed in recent years persists, EVs are poised to become increasingly prevalent on roads worldwide.