02 JULY 2012Reuters
LME explores aluminum expansion in North America
Edited by : AL CIRCLE
4 min read

The London Metal Exchange is considering launching a North American aluminum contract, sources say, a measure that could expand the footprint of its most-active futures market.
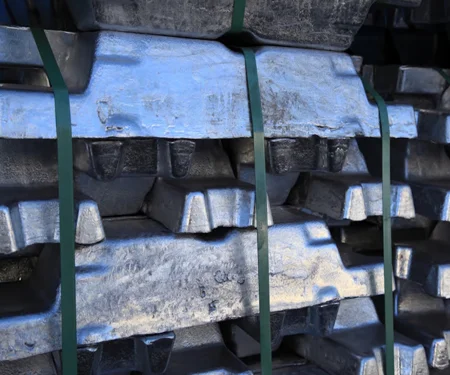
Discussions are still at an early stage, but the LME has begun to canvas physical traders and consumers about the viability of a U.S. contract that would include the Midwest physical premium, which represents the additional cost of delivering the metal from an LME warehouse in Detroit or New Orleans or a producer plant to the Midwest, market participants have told Reuters.
At least one ring dealing member had asked the 135-year old exchange to look into a new contract based on feedback from its own customers, according to a senior executive at the firm.
If the LME follows through, it would be biggest expansion of its most-active metals contract, and could be a breakthrough after several years of lackluster product launches. Many buyers in North America, which accounts for about a quarter of the global 40-million-tonne market, already hedge their costs using over-the-counter (OTC) derivatives based on an average monthly Midwest premium, which is paid on top of the LME's benchmark aluminum price.
The new LME contract would allow direct users like Novelis Inc -- as well as their customers like Coca Cola (COKE.O) and Ford Motor Co (F.N) -- to hedge both their premium exposure and base price risk at the same time, rather than separate transactions.
Interest in the contract has arisen in the wake of the shock collapse of MF Global, the world's largest commodities broker-dealer and also a leading player in the OTC aluminum premium market. Its collapse heightened concerns over counterparty risk in the market, stoking demand for a centrally cleared contract.
With an outright price, the LME contract would provide a one-stop shop. The LME launched primary aluminum in 1978. Today's high-grade contract began trading in August 1987 and now accounts for over a third of monthly volumes.
The need to build an in-house clearing facility before launching any new contracts will likely delay any major new undertakings by several years, sources say.
Chris Evans, head of business development for the LME, declined to comment.
The strategy to leverage its existing contracts rather than branching out into niche new markets is a shift for the exchange, which has been criticized by some users for straying from its core -- with minimal success.
To succeed, the LME may have to win back the support of U.S. end-users, many of whom remain frustrated over the exchange's efforts to deal with a four-year-old warehousing controversy.
While LME prices hit a two-year lows this week, North American aluminum buyers are paying record premiums of more than 10 cents per lb for physical delivery on top of the base price.
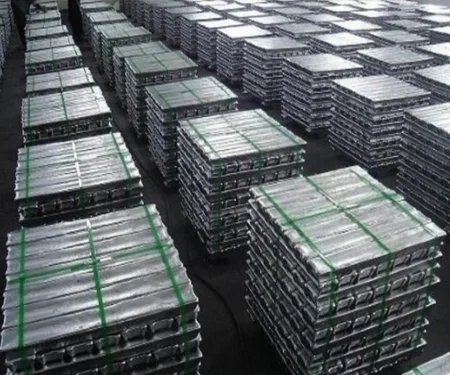
The cause is not a shortage of supply, critics say, but the fact that warehouses owned by JPMorgan (JPM.N) and Goldman Sachs (GS.N) are offering financial incentives and financing deals to store metal in their facilities -- forcing end-users to bid up prices to secure the metal for their own needs. Almost 5 million tonnes of aluminum has been pulled into LME-bonded warehouses over the past five years, much of it locked in for years at a time.
The other unresolved issue is the wait times to take delivery of metal. An owner of aluminum in a Detroit warehouses may have to wait as long as a year before getting hold of their metal due to the enormous queues.
Late last year, the LME raised the minimum load-out rate for some warehouses in an effort to placate angry users, but it has done little to ease the bottleneck, they said.
Many details still need to be worked out. It's not clear if it would be physically delivered, as is LME standard, or cash-settled, which may require the exchange to use a premium assessed by a publication.
Previous article
Rio Tinto expects Chinese growth to cross 8 percent in 2012
Next articleHindalco to Raise Funds Through NCDs
Grow with
AL Circle