The ongoing geo-political conflict in West Asia has put many end-user sectors under strain in several parts of the world. From packaging to building and construction, all have been whining over raw material crisis, especially aluminium, since Gulf countries contribute a substantial portion of the metal used in these manufacturing sectors. Not only large economies like Europe, the United States, or India are grappling with crisis, but also countries like Sri Lanka, which consumes only 28,000 tonnes of aluminium in the construction sector, yet under pressure. That’s because out of 14,941 tonnes of unwrought aluminium sourced in the country, 5,235.73 tonnes come from Bahrain.
Now, coming to the automobile industry, for which the problem is more nuanced because the industry is largely dependent on aluminium and crude oil, and Gulf countries are the major suppliers of both the commodities. About 210-250 kg of aluminium and 50-100 gallons of crude oil go into the production of one passenger vehicle. Globally, about 14-17 million tonnes of aluminium is used in passenger vehicles. The calculation goes like this – according to International Organization of Motor Vehicle Manufacturers (OICA), about 50 million units of passenger vehicles were produced in the first three quarters of 2025, meaning 16 million units per quarter. So, on average, the annual output of vehicles is around 66 million units; hence, aluminium usage amounts to 13.9-16.5 million tonnes. Passenger vehicles consume about 60 per cent of total aluminium consumption in the automobile industry, hence the remaining 40 per cent, which is equivalent to 11 million tonnes is used in commercial cars.
On the other hand, if 50-100 gallons of crude oil in used in one passenger vehicle, then about 157 million barrels of crude oil is used annually for the production of 66 million units of passenger cars. Roughly 7 gallons of oil are needed just to produce the synthetic rubber and materials for one vehicle’s tires, while plastics and engine lubricants add to the overall usage.
The closure of Strait of Hormuz for the last one and a half month has chocked off roughly 12 million barrels per day of oil production – which the International Energy Agency explains the biggest disruption in the history of the global oil market. As a result, Brent crude oil price in March peaked at USD 119 per barrel. Now, it has slightly dipped to USD 98 per tonne, as of April 17, 2026.
But it is not only about inflated oil prices or aluminium supply chain disruptions, the damage runs deeper and in several layers for the automobile industry. Daniel Harrison, Senior Automotive Analyst at Ultima Media, explains: "Iran's de-facto blockade of the Strait of Hormuz hasn't just elevated energy prices or disrupted supply chains, it also cascades up the value chain to affect every type of raw material used in automotive production; steel, aluminium, plastics, rubbers, glass, semiconductors, and even the production of helium used in the production of EV batteries. "The effect? The certainty of inflationary cost pressures upon OEMs."
Still, of all the disruptions that have happened to the automobile sector over six weeks, the most structurally difficult one to unwind is the primary aluminium supply chain chaos.
To know how the industry leaders are reading the current aluminium market, read our latest e-Magazine "Aluminium LeaderSpeak 2026"
In which regions, auto industry suffered the most?
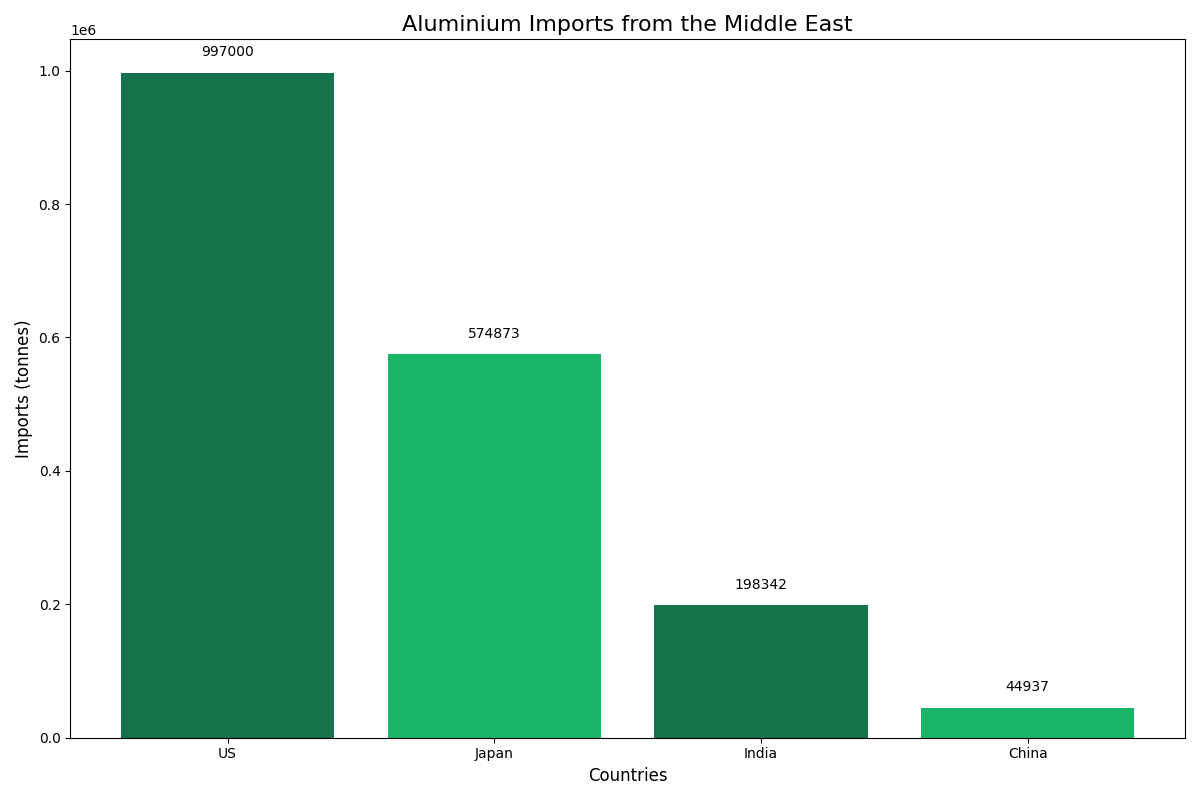
As per the data revealed by OICA in 2025, China, the United States of America, Japan, India, and Germany are the present top five automobile manufacturers, followed by Mexico, South Korea, Brazil, Spain, and Czech Republic the remaining five leading producers of the top ten list. Of them all, the United States, India, and Japan are in the most vulnerable positions, given their aluminium import volume from the Middle East countries. The United States imports around 997,000 tonnes of aluminium (including semi-finished products) from Gulf countries, which is more than 19 per cent of the nation’s total aluminium imports. For automobiles, the United States consumes about 233 kg of aluminium per vehicle and produces nearly 8 million units of cars (commercial + passenger). So, aluminium consumption in its automobile industry amounts to about 1.63 million tonnes. This indicates that the United States aluminium imports from the Middle Eastern countries account for more than 60 per cent of what is used in the automobile industry.
Besides aluminium, the United States also imports a substantial volume of crude oil from the Middle East – which is about 490,000 barrels per day. However, compared to the US, China and India rely more on the Middle East’s crude oil. While China imports nearly 2 billion barrels per day, India secures USD 50.8 billion worth of oil annually.
China and India also import aluminium from the Middle East of about 44,937 tonnes and 198,342 tonnes, respectively. China relatively imports lessened volume but India’s total imports from the Middle East represent 83 per cent of the aluminium used in the country’s passenger vehicles production. India, on average, consumes 45 kg aluminium per vehicle, while its production of cars is 5.3 million units, according to OICA. So, aluminium consumed in the sector is about 239,000 tonnes.
Japan, the third largest automobile producer in the world, imports 574,873 tonnes of aluminium from the Middle East. This makes Japan the next highest importer of aluminium from Gulf after the United States. Japan, due to the supply chain disruption from the Middle East, has already turned to Russia’s RUSAL to replenish the shortfall. Also, RUSAL has announced to divert a part of f its aluminium shipments originally intended for China to Japan.
Don't miss out- Buyers are looking for your products on our B2B platform
Double-whammy for the automobile industry
Well, it is not only a one-way transaction. Besides being aluminium and crude oil importers from the Middle East market, these countries are also the exporters of their finished-products (here automobiles) to the Gulf countries. China, especially, exports one-sixth of its total automobile supplies to Saudi Arabia and the United Arab Emirates. Of the 8.32 million cars shipped overseas by Chinese automakers in 2025, 1.39 million were destined to Gulf, according to Reuters. Major car exporters include Chery Automobile, BYD, SAIC Motor, Changan Automobile, and Geely. This certainly contributes significant to the nation’s economy. According to various reports, China's automobile exports were one of the major economic pillars in 2025, with export values reaching approximately USD 142.46 billion.
However, surprisingly, China’s exports have not faced a hit due to the Middle East crisis, but what have suffered are the nation’s domestic sales. They dropped 15.2 per cent from a year earlier to 1.67 million vehicles in March, owing to rising fuel prices.
The Middle East is also a common automobile export destination for India, Japan, and South Korea. India exported USD 8.8 billion worth of cars in 2025, of which 25 per cent were shipped to the Middle East, mainly Saudi Arabia, according to customs data. But this year, due to the Middle East crisis, S&P Global Mobility estimates that India’s automobile exports to the Middle East will face a hit of roughly 1.6 to 1.7 lakh vehicle units annually. As a result, there is expected to be setback in country’s economy as India’s automobile exports contribute 6 to 7.1 per cent to the overall GDP.
Japan exports 320,699 vehicles to the Middle East, which represents 15 per cent of the company’s total exports of over 2 million units.
The challenge for the automobile industry is unique. It faces a multi-layered crisis due to the Middle East conflict. Not only are supply chains for critical materials like aluminium and crude oil disrupted, but the cascading effect on raw material prices, coupled with shifts in demand from key export markets, paints a grim picture for the global automobile sector.












_md.webp)