Alcoa reports $483m net income in Q3 2026 as aluminium production rises
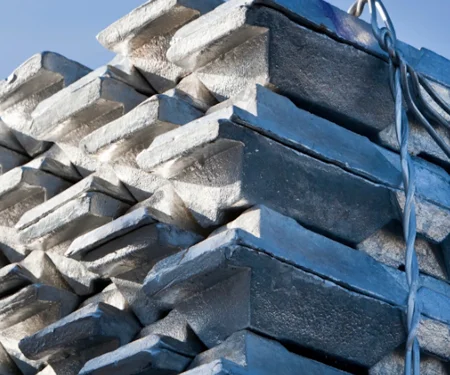
Stock image for referential purposes only
Alcoa Corporation reported net income of USD 483 million in the third quarter of 2026, up from USD 407 million in the previous quarter and USD 232 million in the same period last year, as the company increased aluminium production and improved refinery performance.
Revenue reached USD 3.7 billion, down 6.6 per cent from USD 4 billion in the second quarter but up from about USD 3 billion in the third quarter of 2025. Adjusted EBITDA, excluding special items, was USD 789 million, compared with USD 901 million in the previous quarter and USD 270 million a year earlier.
Adjusted net income stood at USD 1.82 per share, while earnings per common share were USD 1.81. Alcoa generated USD 643 million in cash from operations and reported free cash flow of USD 472 million. Its cash balance reached USD 4.4 billion at the end of the quarter, including USD 2.6 billion in financing secured for its planned acquisition of South32 Limited’s interests in bauxite, alumina and aluminium assets, referred to as AliGroup.
Explore the production, demand and consumption forecasts of bauxite and alumina in our report: "Global Bauxite & Alumina Market Forecast to 2036: Supply–Demand, Trade Flows & Price Outlook"
Alcoa’s alumina production increased 11 per cent successively to 2.5 million tonnes, mainly due to improved operational stability at its Pinjarra refinery in Australia. Aluminium production rose 2 per cent to 649,000 tonnes, supported by capacity restarts completed in the second quarter and the completion of the Alumar smelter restart in Brazil during the third quarter.
Third-party alumina shipments increased 2 per cent from the previous quarter, primarily cause is higher production. However, total aluminium shipments fell 5 per cent following elevated second-quarter volumes associated with inventory repositioning in the first quarter.
Third-party revenue from alumina rose 7 per cent from the previous quarter, driven by higher average selling prices and increased shipments. However, aluminium revenue fell 9 per cent as both shipments and average selling prices declined.
Alcoa said improved production costs in both segments and higher alumina prices supported its quarterly results, although these gains were more than offset in adjusted EBITDA by lower aluminium prices and shipments.
Looking for alumina refinery raw materials? Compare grades, explore sourcing options, and connect with global suppliers on AL Biz.
AliGroup acquisition and other developments
Alcoa continued to advance its planned acquisition of South32’s interests in bauxite, alumina and aluminium assets, progressing regulatory approvals and transition and integration planning. South32 shareholders approved the transaction on October 15, 2026, and the acquisition remains on track to close in the first half of 2027.
The company completed offerings, totalling USD 2.6 billion in September to help fund the acquisition, which includes approximately USD 3.1 billion in cash consideration, alongside related fees and expenses.
Alcoa also entered into definitive agreements to sell portions of its Massena East site in New York. The company expects to receive approximately USD 50 to 65 million at closing, depending on the amount of approved data centre capacity. Additional proceeds of approximately USD 60 to 250 million could follow from approved capacity expansions and capacity-based payments over the seven years after closing. The transaction is expected to close within six months, subject to permitting, regulatory approvals and other conditions.
Unlock key insights from leading companies and experts across the aluminium ecosystem with our e-Magazine - Mine to Market: Aluminium Producers & Manufacturers 2026
2026 outlook
Alcoa reaffirmed its full-year 2026 production and shipment projections. For the alumina segment, it expects production of 9.5 to 9.6 million tonnes and shipments of 11.5 to 11.6 million tonnes. For the aluminium segment, the company projects production of 2.4 to 2.6 million tonnes and shipments of 2.6 to 2.8 million tonnes.
For the fourth quarter, Alcoa expects higher production and shipments in both segments, supported by continued refinery stability and additional output from its smelting operations.
The company expects aluminium segment adjusted EBITDA to face higher raw material costs and planned maintenance, each expected to have an unfavourable impact of approximately USD 30 million. Higher alumina costs within the aluminium segment are also expected to have an unfavourable impact of approximately USD 30 million sequentially.
Alcoa expects other income to increase by USD 20 million in the fourth quarter due to higher interest earned on cash held for the AliGroup acquisition. Full-year interest expense is projected to reach about USD 185 million, an increase from the previous projection due to the issuance of senior notes. Fourth-quarter operational tax expense is expected to be approximately USD 65 to USD 75 million, depending on market conditions and profitability across jurisdictions.
Grow with
AL Circle