Tighter Asian supply supports primary aluminium premiums despite weak demand
The image used in this article is generated with an AI tool and does not depict any real-time moment
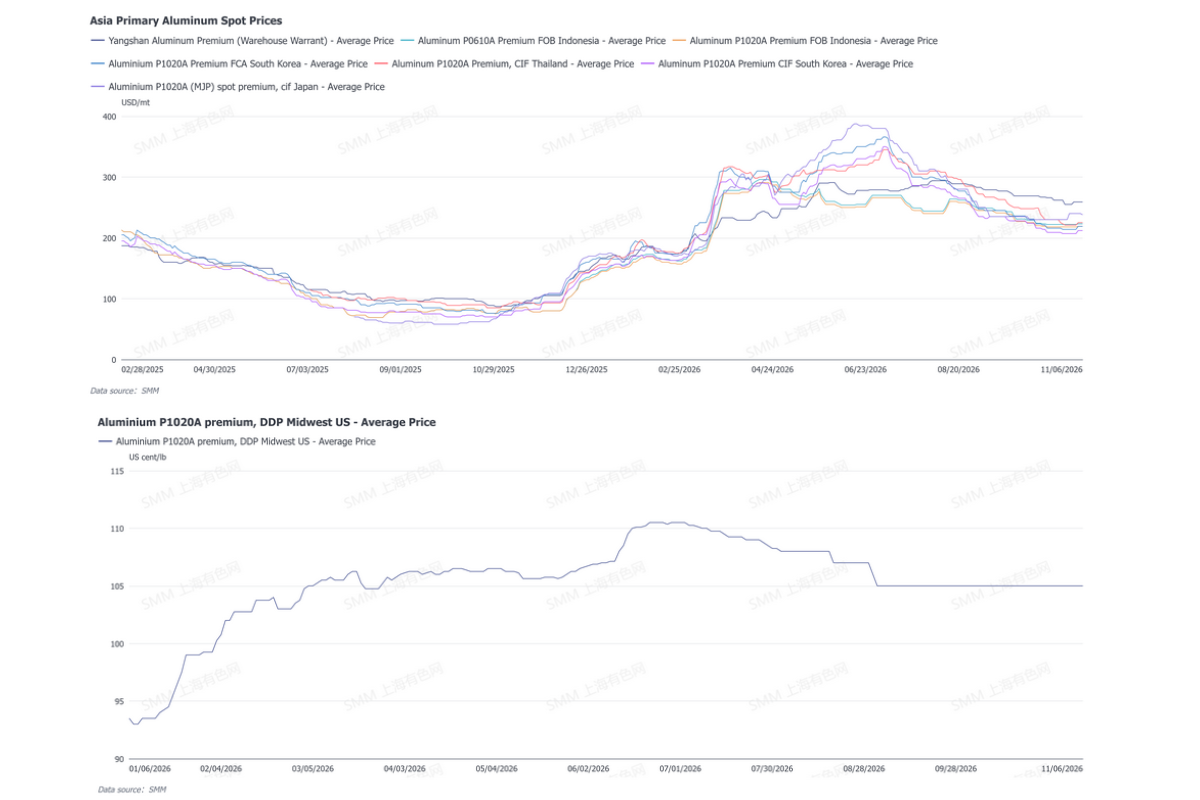
Overseas primary aluminium spot markets remained generally subdued this week, although price movements became more mixed across Asia. Downstream demand remained weak, but tightening availability in Southeast Asia reduced the presence of low-priced offers, while Japan’s MJP spot premium moved higher following several recent transactions.
South Korea saw a marginal improvement in downstream purchasing, although demand remained concentrated on immediate requirements rather than broader restocking. In the United States, the Midwest DDP premium stayed at 105 US cents per lb, while overall market activity remained weak.
I. Review of spot premiums by region
According to the latest SMM data, the CIF Thailand P1020A premium stood at around USD 225 per tonne, while the FCA South Korea premium was around USD 219 per tonne and the CIF South Korea premium was around USD 212 per tonne.
In Japan, the CIF MJP spot premium increased to around USD 238 per tonne following several transactions during the week. The Yangshan warehouse-warrant premium remained higher at around USD 259 per tonne.
In Indonesia, the FOB P0610A premium stood at around USD 223 per tonne, while the FOB P1020A premium was around USD 219 per tonne. Meanwhile, the US Midwest DDP P1020A premium remained at 105 US cents per lb as of November 6.
Southeast Asia
Southeast Asia: Weak demand meets tighter spot availability
End-user orders across Southeast Asia remained weak this week, with downstream processors continuing to purchase aluminium ingots mainly according to immediate production requirements rather than building inventories.
However, the supply side has changed compared with previous weeks. The amount of material circulating in the regional spot market has tightened noticeably. Some cargoes have been redirected toward the Chinese domestic market, while relatively low freight rates to Europe have also encouraged some material to move westward.
At the same time, traders had already reduced inventories during the previous period of weak demand. As a result, sellers holding spot material are now less willing to offer aggressively at low levels, and the availability of cheaper cargoes has narrowed.
In Thailand, downstream purchasing remains subdued, with the CIF P1020A premium around USD 225 per tonne. Weak consumption continues to limit upside, but tighter circulating supply may reduce the scope for further significant declines.
South Korea: Purchasing improves slightly, but incremental demand remains limited
The South Korean market showed a marginal improvement in downstream purchasing this week, although the increase was relatively modest.
Most transactions continued to reflect essential production requirements, with little evidence of broader inventory replenishment. Buyers therefore remained selective despite the slight pickup in activity.
The FCA South Korea premium stood at around USD 219 per tonne, while the CIF premium was around USD 212 per tonne. Without a stronger increase in downstream orders, the improvement in purchasing activity is unlikely to translate into a significant recovery in premiums in the near term.
Japan
CIF Japan MJP primary aluminium spot
Japan’s MJP spot premium moved higher this week after several transactions were concluded, with the assessment increasing to around USD 238 per tonne.
The increase indicates that some buying interest has returned at current levels, although the number of transactions remains limited. Broader downstream demand is still weak, and buyers and traders continue to take a cautious approach toward additional purchases.
The recent deals therefore provide some support to the spot premium, but they do not yet indicate a broad recovery in Japanese physical demand. Market participants are likely to continue watching whether further transactions can be concluded around similar levels before determining whether the recent increase can be sustained.
United States
US Midwest DDP market remains weak but premium holds at 105 US cents per lb
The US Midwest market remained weak this week, although the DDP P1020A premium continued to hold at 105 US cents per lb.
Physical trading activity remained limited, with little evidence of a meaningful improvement in downstream demand. At the same time, the market has not seen sufficient pressure to push the premium below its current level.
As a result, the Midwest DDP premium remains stable in price terms despite relatively weak underlying market activity.
Market outlook
The overseas primary aluminium market continues to show a divergence between weak demand and changing regional supply conditions.
In Southeast Asia, downstream consumption remains soft, but reduced circulating supply and fewer low-priced offers may provide some support to premiums after the declines seen in previous months. South Korea has seen a slight improvement in purchasing, although demand remains largely need-based and lacks meaningful incremental growth.
Japan’s MJP market has shown a modest improvement following recent transactions, but the increase in premiums should not yet be interpreted as a broader recovery in demand. Further transactions will be important in determining whether current levels can be sustained.
In the United States, underlying market activity remains weak, while the Midwest DDP premium continues to hold at 105 US cents per lb. Overall, overseas premiums may find greater support from tighter availability in some markets, but a more substantial recovery will still depend on stronger downstream demand.
Note: This article has been issued by SMM and has been published by AL Circle with its original information without any modifications or edits to the core subject/data.
Grow with
AL Circle












_md.webp)