Inventory buildup continues, spot prices steady-to-weak, ex-China price spread widens amid China's loose supply
The image used in this article is from SMM
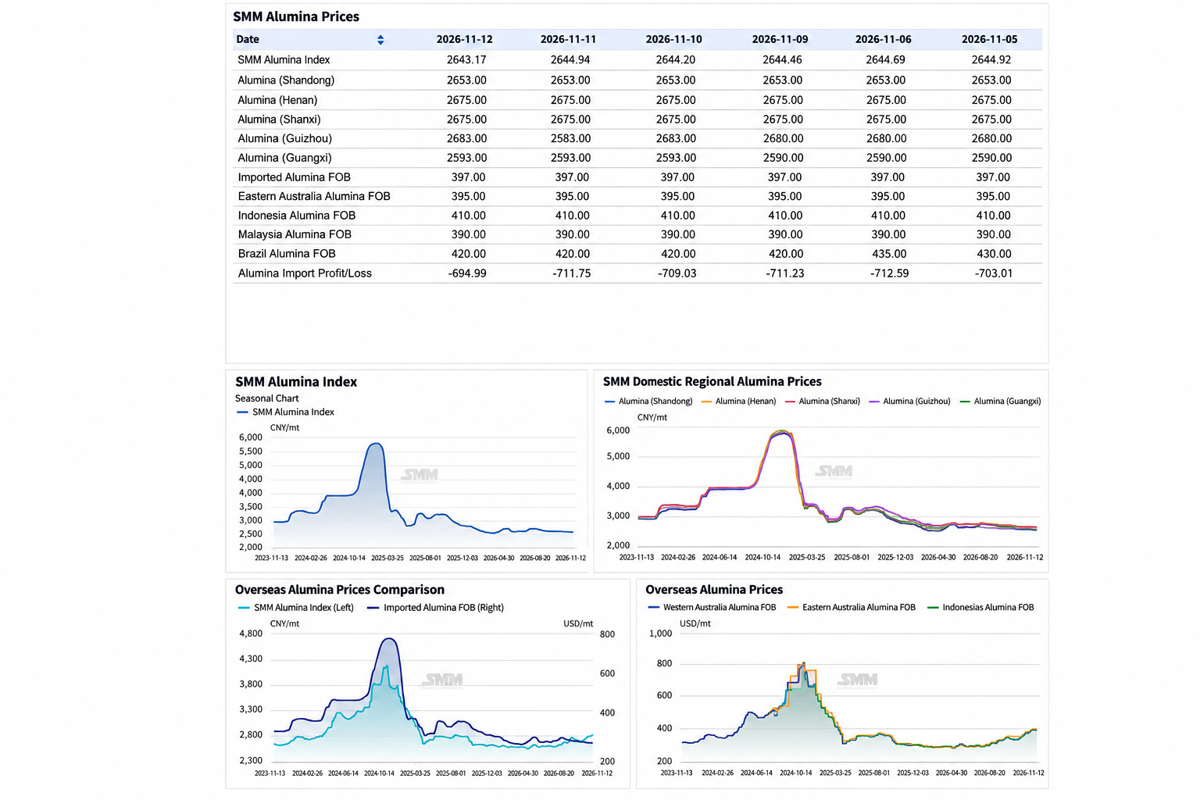
According to SMM data, as of this Thursday, the SMM alumina index stood at RMB 2,643.17 per tonne, down RMB 1.75 per tonne WoW. By region, Shandong was quoted at RMB 2,600-2,670 per tonne, flat WoW; Henan was quoted at RMB 2,650-2,700 per tonne, flat WoW; Shanxi was quoted at RMB 2,650-2,700 per tonne, flat W-o-W; Guangxi was quoted at RMB 2,570-2,610 per tonne, flat WoW; Guizhou was quoted at RMB 2,650-2,710 per tonne, flat WoW.
Ex-China market: As of November 12, 2026, the FOB Western Australia alumina price was USD 397 per tonne, with ocean freight at USD 34.3 per tonne and the USD per CNY selling rate near 6.68. This translates to a delivered price at major Chinese ports of approximately RMB 3,338.16 per tonne, which is RMB 694.99 per tonne above the alumina index price.
According to SMM data, as of this Thursday, China's total built metallurgical-grade alumina capacity was 119.62 million tonnes per year, with operating capacity at 90.52 million tonnes per year. The national weekly operating rate for metallurgical-grade alumina rose 0.12 percentage points WoW to 75.67 per cent. By region, Shandong's weekly alumina operating rate was flat WoW at 82.32 per cent; Shanxi's weekly alumina operating rate was flat WoW at 74.04 per cent; Henan's weekly alumina operating rate was flat WoW at 57.67 per cent; Guangxi's weekly alumina operating rate rose 0.57 percentage points WoW to 75.49 per cent; Guizhou's weekly alumina operating rate was flat W-o-W at 84.17 per cent.
In the spot market, one deal was concluded this week. Xinjiang procured 10 kt of spot alumina, with delivered prices at RMB 2,935 per tonne.
This week, China's total alumina inventory rose 75,600 tonnes W-o-W to 7.7354 million tonnes, with the pace of inventory buildup accelerating notably from last week. By segment: Aluminium smelter raw material inventories fell 22,700 tonnes to 3.6388 million tonnes, as downstream continued to draw down in-factory inventory; inventory levels remained high and purchase willingness stayed weak. Alumina refinery finished product inventories rose 14,200 tonnes to 1.3756 million tonnes, as a slight rebound in production drove further accumulation. Port inventories surged 121,000 tonnes to 1.041 million tonnes, serving as the main contributor to this round of inventory buildup, as previously in-transit cargoes arrived at ports in concentrated fashion, with sustained arrivals at both domestic trade and foreign trade ports pushing inventories higher. On the industry front, the supply side has largely stabilised following earlier maintenance and inspections. Futures prices remained rangebound at low levels, overall market sentiment stayed weak, and trading activity was subdued. Futures prices are expected to remain at low levels going forward. Looking ahead, capacity in Guangxi is resuming operation after earlier maintenance concluded, supply is expected to keep increasing, and market pressure will rise further. Total alumina inventory nationwide is expected to continue its buildup trend. On the price front, the supply-demand easing pattern remains unchanged and upward drivers are weak, so spot prices are expected to mainly hold steady with narrow, slightly weak fluctuations.
Note: This article has been shared by SMM and has been published by AL Circle with its original information without any modifications or edits to the core subject/data.
Grow with
AL Circle












_md.webp)