The aluminium industry sits at a stark juncture where demand tied to the energy transition is set to surge. But is it a viable choice, bearing the short-term and long-term impact? Industry projections point to roughly an 80 per cent rise in aluminium demand by 2050, while the sector itself remains an outsized emitter, with direct emissions concentrated in primary production and global sector emissions measured in the order of gigatonnes. Meeting downstream demand for “green” metal while slashing the sector’s own footprint is not optional: it is an existential commercial imperative. The choice facing producers is binary in economic terms. Invest now, absorb large up-front costs and capture a durable price and capital advantage; or delay, preserve short-term margins and face growing regulatory, market and financing penalties that will erode competitiveness.
Image source: https://www.basystems.co.uk/
Dual role of aluminium in the energy transition
The capital arithmetic is unforgiving and unambiguous. Retrofitting existing primary smelters with inert-anode technology is recognised as a pathway widely recognised as the only credible route to eliminate direct process emissions at scale, and carries an estimated cumulative price tag of roughly USD 200 billion to 2050. That equates to about USD 7 billion a year, roughly a 38 per cent uplift over the sector’s ordinary annual capital expenditure. The industry’s current structural profile — typical profit margins near 13 per cent and a sector WACC around 9 per cent- means internal cashflow alone cannot shoulder this burden.
At the same time, credible price signals for low-carbon metal exist. Market participants reported green premium bids approaching USD 50 per tonne in 2024 for aluminium certified to strict sub-4 tonnes of CO2e per tonne smelter intensity thresholds. That premium is the mechanism through which investors hope to recoup the large inert-anode and renewables capex — but the premium alone is insufficient unless it is underpinned by standardised certification, long-term offtakes and predictable policy.
Decarbonisation has two levers of very different scales. Electrifying production with low-carbon power wherin replacing captive fossil generation with renewables and firming solutions becomes the imperative and represents the largest single opportunity, with potential savings on the order of hundreds of millions of tonnes of CO2e by mid-century if deployed rapidly.
Yet aluminium smelting requires reliable baseload power; integrating variable renewables implies additional system costs for storage, hydrogen, demand response and grid upgrades. Those complementary investments are non-trivial and must be planned alongside plant retrofits.
The second lever is the process change itself: inert anodes, as commercialised in early pilots, eliminate carbon anode CO2 emissions by producing oxygen instead of CO2 in the Hall-Héroult cell. Piloted at scale, inert anode technology could eliminate upwards of 6.5 million tonnes of CO2 annually in key regions. But deployment at a global scale is capital-intensive; without de-risked finance and credible long-term revenue streams, the roll-out will stall.
Emissions baseline and decarbonisation trajectory
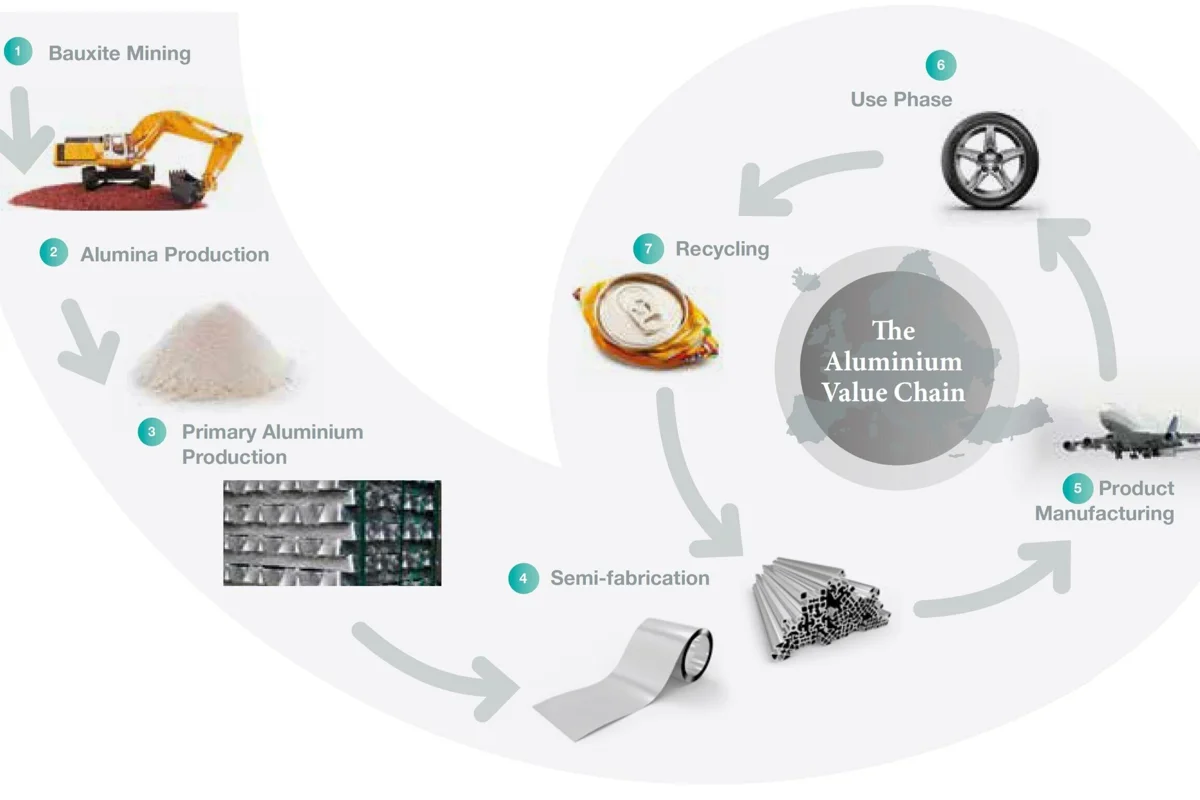
There is a third pathway that is immediate, cheap and powerful: recycling. Secondary production consumes roughly 5-10 MJ per kg of aluminium, which is about 5 per cent of the energy intensity of the primary output, and typically emits around 0.5 tonnes of CO2e per tonne versus multiple tonnes for primary metal.
Secondary aluminium production has grown significantly, hitting record levels in 2024 and constituting approximately 78 per cent of the total aluminium production in 2022. The secondary market is robust, projected to reach USD 168.75 billion by 2032, with processing volumes expanding at a 4.83 per cent rate through 2030.
The low capital intensity of building recycling facilities, compared to primary smelters, makes this an attractive investment. Increasing recycling efforts and improving scrap sorting could unlock significant supply, potentially meeting 25 to 50 per cent of the existing metal supply gap, provided that landfilled or exported scrap is recaptured.
But recycling is not a panacea.
Even if recycling scales, it will not fully substitute for decarbonised primary production: meeting an 80 per cent demand increase requires new, low-carbon primary capacity as well as more scrap. Policy and investment must therefore push both levers — maximising secondary output while financing the capital-intensive primary transition.
Click to subscribe and get free access of our upcoming e-magazine - Sustainability & Recycling: Aluminium's Dual Commitment
Finance is already favouring winners (and penalising laggards)
Regulatory action has already started to stratify the market. The EU’s Carbon Border Adjustment Mechanism (CBAM) and related compliance mechanisms place a direct cost on embedded emissions in imports. Estimates point to an added cost to high-carbon aluminium of roughly USD 20–50 per tonne by 2026 under CBAM-style obligations.
For producers who cannot credibly certify low smelter emissions, that is not merely a compliance bill; it is effectively a tariff that erodes market access and compresses margins. Conversely, compliant producers gain protected access to premium markets and avoid the downside. The message to management teams is stark: emission performance is now a determinative commercial variable in trade flows, not an environmental vanity metric.
Capital markets are pricing sustainability into valuations and cost of capital. Companies with high ESG performance have demonstrated markedly better operating outcomes and investor access with higher margins, lower WACC and resilience in stress periods. Sustainability-linked finance is no longer a niche; it is a mainstream route to lower-cost funding conditional on verifiable targets. The inverse is also true: firms that fail to commit to transparent decarbonisation trajectories will find access to capital narrower and more expensive.
A practical blueprint producers must adopt now
The sector needs an urgent, integrated playbook. First, secure long-term, bankable offtake and PPA contracts that underwrite the revenue streams necessary to justify inert-anode and renewables capex.
Second, invest aggressively in MRV (monitoring, reporting and verification) systems and product-level certification so the market can reliably pay the green premium.
Third, prioritise secondary expansion through improved scrap collection, sorting and domestic processing capacity to capture low-cost, low-carbon supply.
Fourth, lobby for targeted public-private risk sharing: governments and multilateral finance must underwrite a portion of the USD 200 billion retrofit requirement through concessional capital, guarantees and performance-linked grants to bridge the valley of death.
Finally, adopt integrated financial disclosures that tie decarbonisation milestones to explicit OPEX savings, premium capture and regulatory exposure reduction—because intrinsic investors now demand quantifiable, cash-flow-linked ESG outcomes. Each step is non-optional if producers seek to preserve market share and profitability in the coming decade.
Download our exclusive report to gain in-depth industry insights: World Recycled ALuminium Market Analysis Industry forecast to 2032
The green premium phenomenon and quantification
The direct financial boon of sustainability is realised through the Green Premium, which reflects the market value assigned to certified low-carbon products. Demand for verified low-carbon aluminium (P1020) remains robust, with offers heard close to USD 50 per tonne in 2024, assessed as a differential over the standard London Metal Exchange (LME) price.
To standardise the valuation of this premium, price reporting agencies have established detailed assessments:
- Low-Carbon Aluminium Price (LCAP): This assessment tracks a premium over the cash-settlement price for primary aluminium with verified 1 and 2 emissions of no more than 4 tonnes of CO2 per tonne of aluminium at the smelter. The inclusion in this assessment requires certification of smelter emissions by an internationally accepted, independent organisation.
- Zero-Carbon Aluminium Price (ZCAP): This concept builds upon the LCAP by adding the cost of offsetting any remaining emissions to net zero. It is calculated as ZCAP=LCAP+(4*CEC), where CEC is the price for voluntary, aviation-grade carbon credits.
The LME is engaging in market discussions to formalise these price premia for sustainable metals. The establishment of such standards transforms carbon performance from an environmental metric into a distinct, high-value commodity class, essential for quantifying risk and spotting opportunities. The USD 50 per tonne premium is the market’s immediate mechanism to help secure the necessary ROI for the USD 200 billion inert anode CapEx.
Mitigation strategies for high-carbon incumbents to avert the bane
High-carbon incumbents must strategically deploy capital to mitigate escalating risks:
- Accelerated energy transition: The shift to low-carbon electricity accounts for the largest potential emissions savings (651 Mt CO2e by 2050). Firms dependent on fossil fuels must prioritise retiring captive power plants ahead of schedule. Firms leveraging existing hydro resources, as seen in Brazil or Norway, will gain immediate structural advantages.
- Investment in scrap processing: Given that secondary production is far less capital-intensive than primary smelters, incumbents should strategically invest in advanced scrap sorting and closed-loop material management. This helps secure vital feedstock and meets growing domestic demand for low-carbon material while addressing the global scrap squeeze.
- Compliance and transparency: Immediate investment in Monitoring, Reporting, and Verification (MRV) systems for emissions tracking is essential to meet the impending compliance requirements of mechanisms like CBAM. Robust data transparency transforms a compliance cost into a prerequisite for future competitiveness.
Companies recognised as ESG leaders, such as AMAG Austria Metall AG, are ranked at the top of the aluminium sub-industry by rating agencies like Sustainalytics. This leadership translates into favourable market perceptions and superior valuation metrics. The differentiation between sustainability leaders and laggards is visible in equity valuations.
Low-carbon leaders, such as Norsk Hydro (leveraging hydropower), tend to exhibit higher Price-to-Earnings (P/E) ratios compared to high-carbon peers. This disparity is a proxy for the market’s pricing of climate transition risk. Investors award a valuation premium for operational security, lower future regulatory liability (reduced exposure to costs), and clear, forward-looking strategies that link initiatives to reliable future cash flows.












_md.webp)
_md.webp)
_md.webp)