US Fed rate hike expectations further heat up, macro sentiment under pressure bearish for aluminium prices
Stock image for referential purposes only
Futures: The daytime session closed at RMB 24,075 per tonne yesterday, edging up 0.02 per cent, with intraday fluctuations between 23,980 and 24,110. Prices remained above all key moving averages (MA5=24,000, MA10=23,558.5, MA30=23,789.83, MA60=23,569.67), with the moving average system maintaining a bullish alignment and the medium-term uptrend intact.
The MACD indicator showed DIF=101.76 and DEA=91.37, with the histogram turning from negative to positive at 20.78, forming a golden cross signal that indicates renewed bullish momentum and a possible end to the short-term correction. Trading volume rebounded slightly to 61,600 lots, with market activity showing modest improvement.
The suggested core trading range for SHFE aluminium is 23,800-24,400. LME aluminium closed at USD 3,276.5 per tonne, up 0.12 per cent, with intraday fluctuations between 3,248 and 3,276.5. Prices remained above all key moving averages (MA5=3,248.9, MA10=3,236.7, MA30=3,233.3), with the moving average system in bullish alignment. The MACD indicator showed DIF=5.60 and DEA=2.95, with the histogram positive at 5.29, maintaining a golden cross state and sustained bullish momentum. The suggested core trading range for LME aluminium is 3,250-3,320.
Macro front: US Central Command confirmed that starting from 0:00 Beijing time on September 2, US forces launched strikes against targets of Iran's Islamic Revolutionary Guard Corps in response to Iranian attacks on commercial vessels in the Strait of Hormuz and US military bases in the region. US President Trump stated that the strikes were "massive and powerful." If Iran retaliates against these strikes, it will face even more intense and higher-intensity strikes. Following the latest round of attacks, Iran's armed forces announced they had launched operations in response to the US strikes, with US bases and interests in the region now being targeted by Iranian missiles and drones.
Fed Governor Barr said he would be prepared to support rate hikes if US inflation fails to ease further. With Fed Chairman Warsh having previously signalled a hawkish stance and US Treasury yields continuing to climb, market expectations for the Fed to resume rate hikes as early as the September meeting have further intensified.
Fundamentals: Markets outside China, overseas aluminium production resumptions and new capacity continue to ramp up as planned, with damaged capacity in the Middle East gradually recovering. Market expectations for the global aluminium market to shift from tight to loose in the longer term persist, continuing to cap aluminium price upside room.
However, LME visible inventory remains at a historically extremely low level of around 250,000 tonnes, providing bottom support for LME aluminium. As oil prices pull back, overseas smelting energy costs are edging lower at the margin, weakening cost support for aluminium prices.
Spot premiums have seen limited improvement, and bulls lack sufficient momentum for sustained upward moves. In the Chinese market, inventory side, this week domestic aluminium social inventory continued its destocking trend. As of this Monday, domestic aluminium ingot social inventory fell 15,000 tonnes W-o-W from last Thursday to 837,000 tonnes, and fell 23,000 tonnes from last Monday, showing counter-seasonal destocking characteristics, providing strong support for aluminium prices.
Demand side, downstream processing enterprises' operating rates currently remain at neutral levels. With the traditional "September peak season" approaching, the market holds expectations for subsequent demand improvement, but downstream pre-restocking remains limited in scale, with participants still waiting to see whether peak season real demand materialises. Spot transactions are dominated by just-in-time procurement.
Primary aluminium market: SHFE aluminium futures continued to rally. Some suppliers in the market held bullish sentiment. Coinciding with tight supply in Wuxi today, A00 aluminium ingot spot premiums rose, with main transactions at discounts of 10 yuan/mt to premiums of RMB 10 per tonne. Today was the last working day of August. Aluminium futures moved sideways in a narrow range. Market buying sentiment remained subdued.
Only a few top-tier downstream processing enterprises maintained just-in-time procurement in small volumes. Overall transactions were sluggish. Ultimately, actual transaction prices in the central China market were centred around discounts of RMB 110-140 per tonne against the SHFE aluminium September contract. Today, aluminium price gains widened, and spot market pressure intensified.
Although inventory remained stable at low levels, on one hand persistently high absolute prices exerted pressure, and on the other hand expectations of further declines in spot-futures price spreads prompted early selling to realise cash. Additionally, some warrant cargo was dumped at low prices, causing disruption. Suppliers kept cutting prices to sell. Downstream buyers were unable to chase higher prices and made few purchases beyond basic just-in-time procurement. Traders were also in no rush to buy, gradually purchasing mainly low-discount cargo. Transactions were poor.
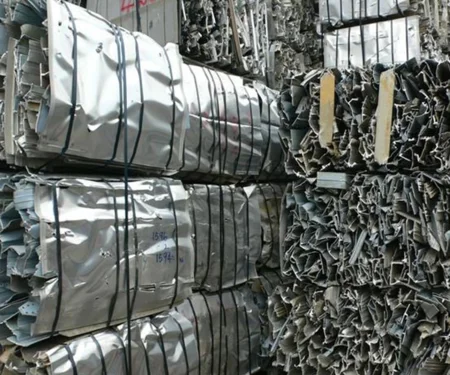
Aluminium scrap: Today, SMM A00 spot aluminium closed at RMB 24,110 per tonne, up another RMB 170 per tonne from the previous trading day. Domestic aluminium scrap prices overall edged higher, with some regional varieties recovering the previous day's declines. On the price difference between A00 aluminium and aluminium scrap, as of September 1, the price difference between A00 aluminium and mixed aluminium extrusion scrap free of paint in Foshan was about RMB 2,302 per tonne and the price difference between A00 aluminium and shredded aluminium tense scrap was about RMB 1,137 per tonne, remaining stable W-o-W.
Against the backdrop of continued rebound in primary aluminium prices, aluminium scrap fluctuations were relatively limited, and the price transmission mechanism was hindered, mainly constrained by two factors: first, with the traditional peak season about to arrive, downstream secondary aluminium alloy demand has not shown significant improvement; second, high inventory of wrought aluminium alloy scrap raw materials such as doors and windows in Henan and other regions has weakened the elasticity of aluminium scrap price increases.
In addition, on the supply side, the "reverse invoicing" policy constraints continued, and the scarcity of compliant invoiced aluminium scrap provided bottom support for aluminium scrap prices. On imports, this week, imported shredded aluminium prices at Ningbo port were lowered from RMB 21,670 per tonne to RMB 21,370 per tonne (tax inclusive), and at Tianjin port from RMB 21,720 per tonne to RMB 21,420 per tonne (tax inclusive).
The import window has improved compared with before recently, with traders showing increased inquiry and purchasing enthusiasm, and import supply has increased. In the short term, the market is at the tail end of the traditional off-season.
Orders at downstream scrap utilisation enterprises have yet to show a clear recovery, and the pre-peak-season effect is not significant. Scrap utilisation enterprises continue to purchase as needed and maintain low inventory strategies, with limited acceptance of higher prices. Some enterprises chose to hold off and observe after earlier price increases. On the import side, previously traded cargoes arriving at ports have provided some supply replenishment, but the deeper effects of the UAE ban and EU tariff hikes will continue to limit the release of high-quality scrap imports.
Secondary aluminium alloy: Spot: Today, ADC12 market quotes were generally firm, with the SMM ADC12 price rising RMB 50 per tonne from the previous trading day to RMB 24,100 per tonne. Driven by higher aluminium prices and aluminium scrap raw material costs, cost support strengthened further. Demand side, entering the traditional peak season, end-use orders improved from earlier levels, but the overall recovery remained limited, and market purchasing has yet to show a significant pickup.
Some enterprises, having already adjusted prices the previous day, stayed on the sidelines today, and the market remained cautious about further price increases. Overall, the current rise in ADC12 prices is mainly driven by the cost side, with demand improvement providing some support, but sustained upward momentum has not yet formed. In the short term, the market still needs to monitor cost changes and the pace of end-use demand recovery.
Comprehensive outlook:Macro front, the Jackson Hole central bank symposium released hawkish signals, and Fed Chairman Warsh struck a hawkish tone in his debut remarks. Expectations for a September rate hike heated up again, global liquidity expectations tightened, and macro sentiment came under pressure, creating bearish pressure on aluminium prices. However, China's continued inventory destocking and the ongoing "September peak season" provided strong support below aluminium prices. With bullish and bearish factors intertwined, aluminium prices are expected to continue to consolidate at highs.
Indonesia sees aluminium opportunity in Middle East supply crisis, but coal is powering the race
Next articleLME aluminium cash price rises to $3,260.5/t, Asian Reference Price gains 1.2% on September 1
Grow with
AL Circle