UK aluminium squeezed by weak production, soaring demand, and high energy costs – What's the way forward? What UK Budget indicates?
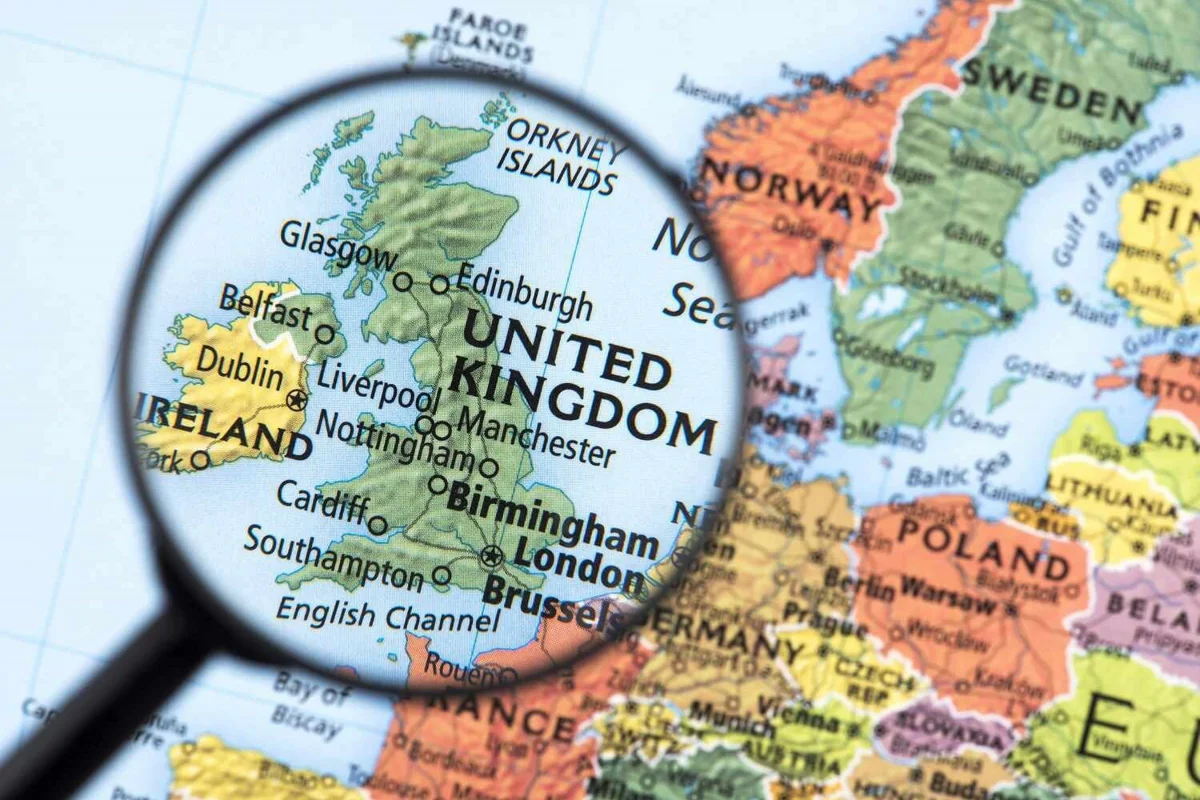
The United Kingdom’s aluminium industry has two options ahead to survive - one is by remaining reliant on imported aluminium cast, rolled, extruded, or forged semi-fabricated products with little or no control over embedded carbon, and the other is by developing a domestic recycling-based supply chain aligned with circular economy principles and national net zero goals. Because over the years, almost all the UK’s primary aluminium smelters have shut their operations due to unbearable energy costs. The only remaining smelter is the one owned by Alvanche in Lochaber, capable of producing a small fraction (50,000 tonnes per year) of the UK’s growing aluminium need.
UK aluminium demand vs production
According to 2024 analysis, aluminium consumption in the UK domestic market was about 296,000 tonnes, of which primary aluminium demand was 167,000 tonnes and secondary aluminium demand was 129,000 tonnes. The market value, which was at USD 2.03 billion in 2023, is poised to grow at a CAGR of 3.2 per cent to USD 2.65 billion by 2030. In contrast, aluminium production decreased from 320,000 tonnes in 2000 to 103,000 tonnes in 2024.
Unlock full access – sign up for FREE.
Key benefits
LME aluminium cash offer rises to $2,867.5/t as opening stocks fall 0.47% to 525,800t
Next articleRUSAL eyes India as a viable market for its low-carbon aluminium portfolio
Grow with
AL Circle