The US produces a large quantity of beverage cans domestically. But, it isn't enough to cater to the country's need. Import takes up a large portion of the aluminium trade in the stance of the United States. And among these inbound trade comes the aluminium can which is an intergral part of America's gastronomy as well as beverage industry. As the new tariffs are part of an aggressive tariff policy by US President Donald Trump that has impacted the global system of international trade, the Bureau of Industry and Security (BIS) announced the inclusion of two products to the additional 25 per cent Section 232 tariffs on aluminium-derived products. These products are classified as follows: HTSUS 7612.90.10 (empty aluminium cans) and HTSUS 2203.00.00 (beer).
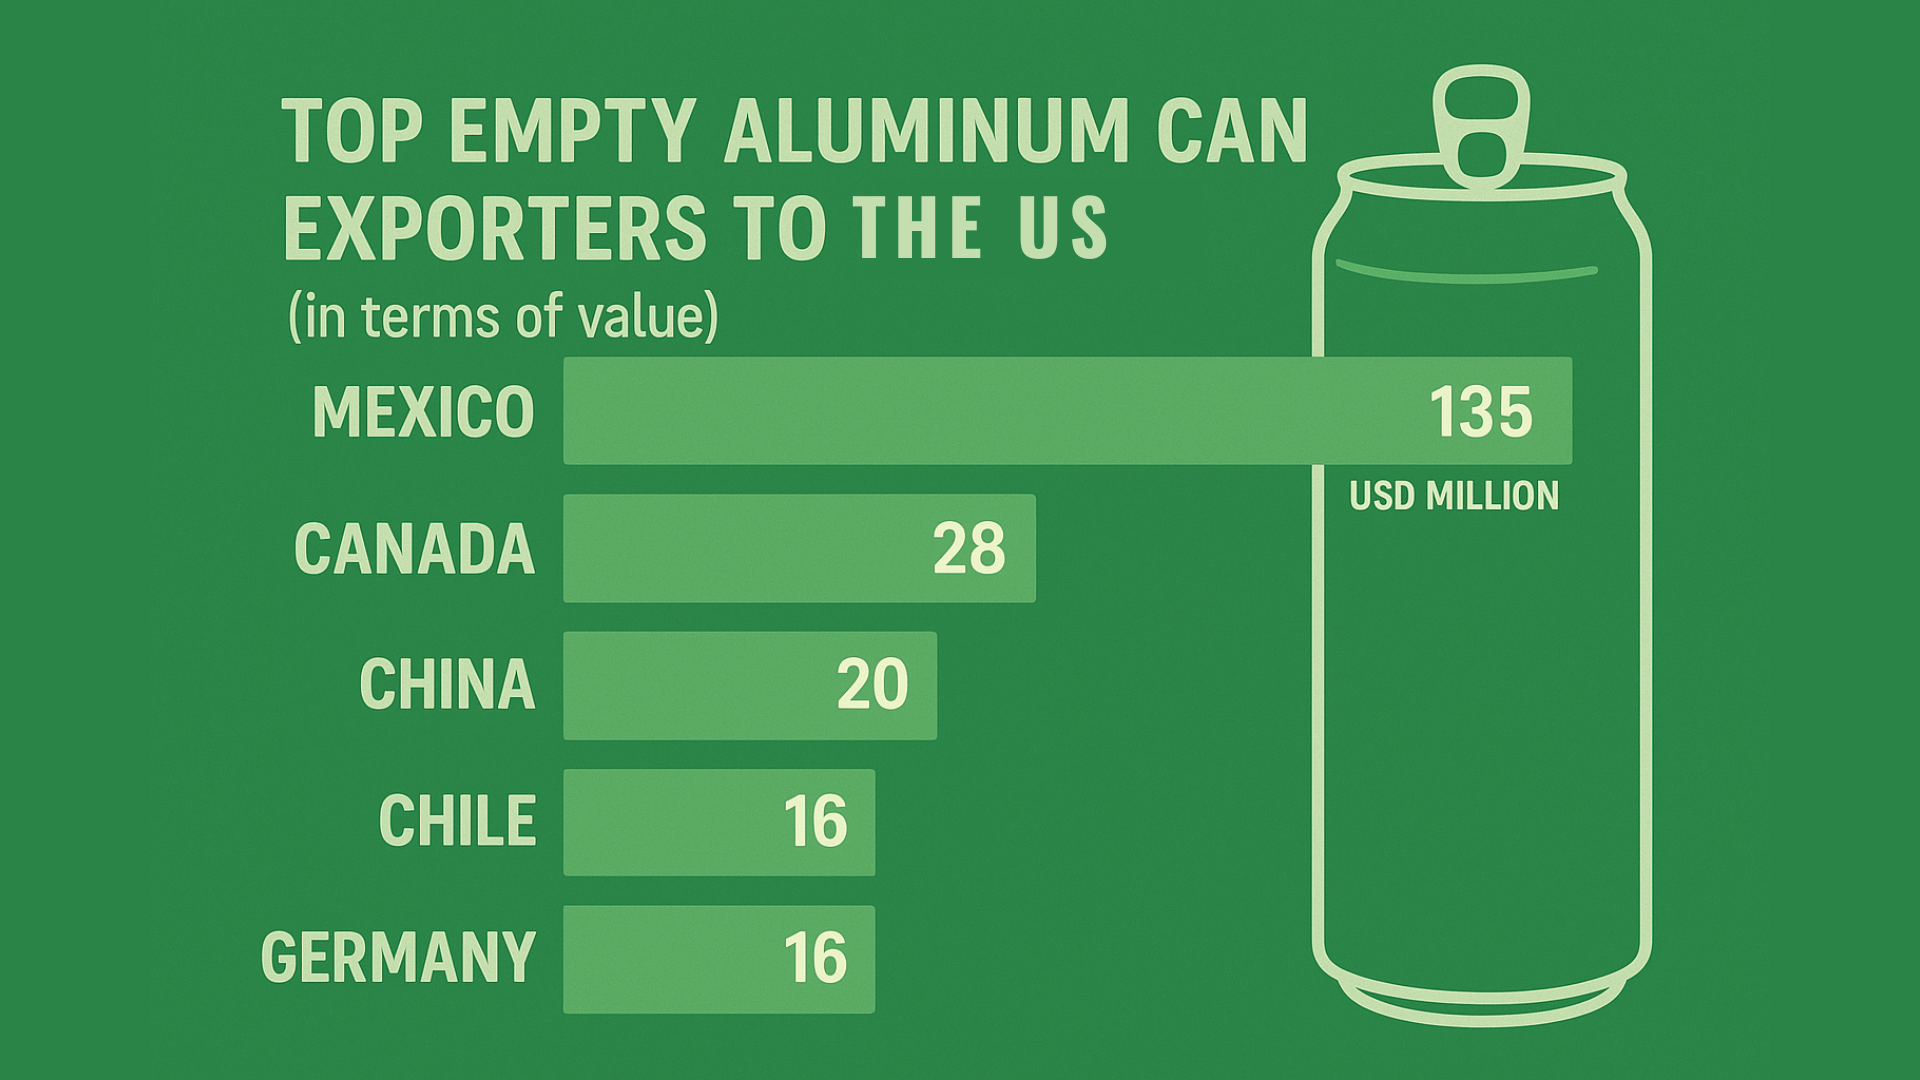
The newly added item in the list, an empty aluminium can, has a huge production market in the US. However, demand exceeds supply in this scenario. The following are the five largest exporters of empty aluminium cans to the United States in 2024:
According to 2024 data, Mexico exported a total of USD 135 million valued aluminium cans to the United States.
There are three major producing companies who have the lion’s share of contribution towards the export numbers. In 2024, Crown Holding’s six beverage‑can facilities in Mexico collectively produced approximately 6.85 billion aluminium beverage cans. Simultaneously, Ball Corporation’s (Monterrey plant) two-line beverage‑can plant began production in late 2016. While Ball doesn’t break out Mexico-only volumes, the company shipped 52 billion aluminium beverage containers across North and Central America in 2022 (including Canada, the US and Mexico).
Mexico is one of Ball’s fastest-growing markets in the region, and North & Central American volumes rose further in 2024, underscoring that the Monterrey plant is running at several billion cans annually.
Envases Universales’ (Grupo Envases) Yucatán plant (opened 2016) is estimated to produce 2 billion cans per year, whereas, since this year, the Hidalgo State plant (under construction, coming online 2025) is designed for 2 billion cans per year.
Mexico’s shared land border slashes shipping times and costs, enabling just-in-time delivery for high-volume beverage customers. Even in the face of US tariffs, many companies stick with Mexico because of its geographic closeness, shorter transit routes, and fewer supply‑chain headaches compared to overseas sourcing
2024 saw Canada ship a cumulative USD 28 million. Canadian aluminium producers benefit from lower energy costs, particularly due to the availability of hydroelectric power. Electricity is a major component of aluminium production costs, and Canada’s lower energy prices provide a competitive edge over US producers, where energy costs are higher.
None of the top-producing companies of this second-largest exporting country, having production lines in the Americas, break out Canada-only figures in their public filings. Ball Corporation’s (Canada) North and Central America beverage‑can shipments were about 52 billion cans in 2022, and the company reports volumes will have risen further in 2024. Assuming Canada represents roughly 10 per cent of those North/Central America volumes (by population share), that implies the order of 5 billion cans produced in Canada in 2024.
Crown Holdings’ global beverage‑can shipments reached 82 billion cans in 2024, with North America accounting for approximately 40 per cent of that total (33 billion cans). If Canada’s share is again 10 per cent of North American volumes, that equates to roughly 3 billion cans made in Crown’s Canadian plants in 2024.
Ardagh Metal Packaging’s (AMP) global volumes grew 3 per cent in 2024 to an estimated 18 billion cans, with North America making up about 20 per cent of that (3.6 billion cans). Canada’s share of AMP’s North American output is smaller, around 15 per cent, suggesting the order of 0.5 billion cans produced at its Canadian facility in 2024.
During the last financial year, China was a USD 20 million exporter of empty cans to the US. Investments in precision processing, low-carbon smelting, and recycling infrastructure have elevated Chinese can‑sheet quality to meet stringent US beverage standards. Until late 2024, China offered export tax rebates of up to 13 per cent on aluminium products, effectively subsidising outbound shipments and bolstering competitiveness abroad. Although these rebates were cancelled as of December 1, 2024, their earlier impact helped Chinese can‑sheet producers secure US market share.
Among the top producers of the exporting country is Henan Airuihai New Materials Co. Ltd, which in 2024, though its “super pop‑can” project in Gongyi City was slated for an annual production of 30 billion aluminium cans, making it one of the single largest greenfield can‑making investments in China this year.
ORG Development Limited (ORG), a division spun out of CPMC Holdings, operates 11 beverage‑can and end-making plants across China and is estimated to produce roughly 15 billion aluminium cans annually.
Baosteel Packaging (China Baowu Steel Group affiliate), at its Xiamen facility, commissioned a high-speed can-making line in 2024 capable of turning out over 1 billion cans per year, with a second line already planned to further boost capacity.
Precise 2024 figures for state-owned CPMC Holdings and other regional players aren’t publicly broken out by plant, but with ORG’s 15 billion and Baosteel’s rapidly scaling lines, these three alone account for nearly half of China’s newly added can-making capacity in 2024.
Chile has exported cans worth USD 16 million to the United States during 2024, as per initial reports. In Chile, key aluminium can manufacturers include Ball Corporation (Ball Chile S.A.), Condensa, and Metalum, with Condensa specialising in aluminium packaging and Metalum focusing on aluminium recycling and processing. While Chile doesn’t produce as many cans as Mexico or China, it focuses on premium, high-grade aluminium packaging for beverages and exports a significant portion of its output.
Germany has also exported cans worth of USD 16 million to the US in 2024. In 2024, Germany’s total deliveries of aluminium tubes and aerosol cans to the national market reached 562.5 million cans, marking a 2.3 per cent decline compared to the previous year, with the aerosol can segment showing growth in the second half.
In sum, imports of empty aluminium cans to the US in CY 2024 were approximately USD 268 million, a 15 per cent drop from 2023 numbers.
On April 2, 2025, the Department of Commerce’s Bureau of Industry and Security issued a fresh notice published in the Federal Register. Apart from other similar packaging items, it mentions the addition of beer cans and empty aluminium cans to the list of aluminium ‘derived’ products. These products are, therefore, subject to tariffs under Section 232 of the Trade Expansion Act of 1962.
According to The Observatory of Economic Complexity, during January 2025, year-on-year imports of aluminium cans (overall) to the US decreased by 19.4 per cent. This was explained primarily by a decrease in imports from China (-USD 4.63 million or -64.2 per cent), Canada (-USD 3.4 million or -59.4 per cent), and the United Kingdom (-USD 444 thousand or -89.5 per cent).
Despite being home to some of the world’s largest can manufacturers, the United States still imports a significant volume of empty aluminium cans. Here’s why:
Massive domestic production – but not limitless
The US can‑production industry produces roughly 130.7 billion cans annually, employs over 28,000 people across 33 states (plus territories), and generates about USD 15.7 billion in direct economic activity through companies like Ball, Crown Holdings, and Silgan Containers. At the same time, US Beverage consumption alone exceeds 106 billion cans per year, and overall can usage (including food and general line cans) approaches 180 billion units annually.
Demand spikes and capacity constraints
The COVID-19 pandemic triggered a surge in off-premise beverage consumption: with bars and restaurants closed, consumers shifted to buying six‑packs and cases for home, and the rise of hard seltzers further amplified demand. Domestic can makers — already running near capacity — responded by raising minimum order quantities (e.g., Ball increased its printed‑can minimum from one to five truckloads per SKU) and halting warehousing for smaller customers, pushing some breweries to seek blank cans or mobile canning services that rely on imported aluminium.
Cost and resource imbalances
Although the US remain a significant producer of secondary (recycled) aluminium, primary smelters operate at only about 55 per cent capacity, well below Canada’s 95 per cent, due largely to high electricity costs that make US metal less competitive on price. Meanwhile, only about 43 per cent of US beverage cans were recycled in 2023, down from 57 per cent in 2014, resulting in annual losses of over one million tons of aluminium scrap (worth USD 1.6 billion) that could otherwise feed domestic can plants.
Out of the total imports to the US, some imported cans originate from Mexico and other plants that use lower‑cost Chinese aluminium sheets, effectively transhipping Chinese metal into the US supply chain. In recognition of this dependency, as of April 2, 2025, the US imposed a 25 per cent tariff on empty aluminium cans (alongside beer) under Section 232, aiming to level the playing field for domestic producers.
Though the import numbers sound punchy, the numbers have been following consistently for the past few years. There are two major contributors cited for the outcome — US tariff imposition since 2018, initially 10 per cent and then 25 per cent. On the other hand, American youth’s beverage consumption trait has gone way down, drastically making demand a weak link in the entire business. Now, the tariff and counter-tariff game is set to boost the domestic market and share that the downing import number is a good sign. But, given the scenario where Novelis sites come to a stop in West Virginia and production companies fail to meet the domestic as well as the international demand, the feasibility check in this case is far-fetched from the ideal situation.












_md.webp)
_md.webp)
_md.webp)