AL Circle recently had the privilege of attending the presentation of Mr Uday Patel, Senior Research Manager for Metals and Mining – Aluminium, Wood Mackenzie, at the ICSOBA 2024 conference in Lyon, France. This enlightening session provided valuable insights into the current challenges facing the aluminium industry, as well as the potential outlook that could reshape its future. His expertise provided a comprehensive understanding of the dynamic landscape, highlighting the critical factors influencing market trends and the implications for stakeholders across the industry. This write-up is derived from the macroeconomic outlook based on Wood Mackenzie’s Q3 analysis, which Mr Uday Patel shared during his presentation.
As the global economy begins to recover from the shocks of recent years, signs of both resilience and uncertainty emerge across sectors. Despite this momentum, the US economy is on the brink of a cyclical slowdown, with potential recession risks underscored by the approaching US elections and their implications for trade, fiscal, and foreign policy. Given these dynamics, the aluminium industry is at a crucial juncture, influenced by internal demand factors and broader geopolitical developments.
Economic recovery amid persistent slumps
Global GDP is growth stable at 2.7 per cent in 2024 and is forecasted to grow with a slight acceleration to 3.0 per cent in 2025. However, challenges linger, especially in developed economies where industrial production remains subdued. The expected delay in interest rate cuts has stalled investment rotation, impacting manufacturing and industrial output. For the aluminium industry, this industrial slowdown translates into a mixed demand outlook. While sectors like energy transition (wind and solar installations) and electric vehicles (EVs) are projected to increase aluminium consumption, these demand drivers are counterbalanced by overall sluggishness in traditional manufacturing.
US economy and recession risks
The US economy, which enjoyed an accelerated GDP growth rate in Q2 2024, now faces an impending cyclical downturn. Indicators such as slowed job growth and a steady uptick in unemployment signal softening economic conditions. A critical factor is the outcome of the US presidential election, where the distinct policies of the candidates could have pronounced effects on trade and economic stability. Notably, Trump's proposed increase in tariffs, especially a dramatic hike on Chinese imports, could shock the aluminium market and broader economy, potentially triggering a recession. In contrast, Harris's policy platform leans towards more balanced fiscal adjustments and continuing existing tariffs, potentially stabilising trade relations.
Trade tensions and aluminium market implications
Trade policies will play a significant role in shaping aluminium's future. Under the Trump administration, a proposed 60 per cent tariff on Chinese goods would disrupt global supply chains and further amplify trade tensions. Such barriers would elevate aluminium prices domestically, impacting industries reliant on imported materials and escalating inflationary pressures in critical sectors. This scenario could challenge US manufacturers relying on the global aluminium supply chain for various automotive and consumer electronics applications.
The global aluminium market has already been marked by volatility due to China's shifting economic policies and its sustained position as a primary importer of aluminium. In light of slower growth projections for China, questions arise about the sustainability of its import levels and the broader impact on global demand. Additionally, the European Union's CBAM (Carbon Border Adjustment Mechanism) will likely affect trade flows, as it may impose carbon costs on aluminium imports, potentially influencing where and how aluminium is sourced.
Energy transition as a lifeline for aluminium demand
Amidst this economic turbulence, the aluminium industry finds optimism in the energy transition. With energy transition sectors anticipated to constitute 37 per cent of total aluminium demand by 2040, government policies on renewable energy and sustainable transportation will be pivotal. Key areas such as EV production, renewable energy installations, and infrastructure for energy storage promise steady demand growth. However, the aluminium sector must also confront carbon pricing, particularly within the EU, where CBAM may extend to include indirect emissions, placing additional cost pressures on exporters.
To meet the projected demand, the industry will require an estimated 14 million tonnes per annum of additional smelter capacity by 2050, alongside increased recycling efforts. The latter aligns with a growing trend in mergers and acquisitions aimed at vertically integrating supply chains and securing scrap aluminium, reducing dependency on primary metal and lowering carbon footprints.
While short-term uncertainty prevails, including the potential for recession and policy-driven trade disruptions, the aluminium industry's long-term outlook is buoyed by the energy transition and ongoing technological advancements. The industry stands at a crossroads where strategic investments in recycling, decarbonisation, and low-carbon aluminium production will shape its trajectory. Maintaining a balanced approach to growth, adapting to policy changes, and strengthening supply chain resilience will be essential for the industry to thrive in a shifting global economy.
Information credit: Mr Uday Patel, Senior Research Manager for Metals and Mining – Aluminium, Wood Mackenzie
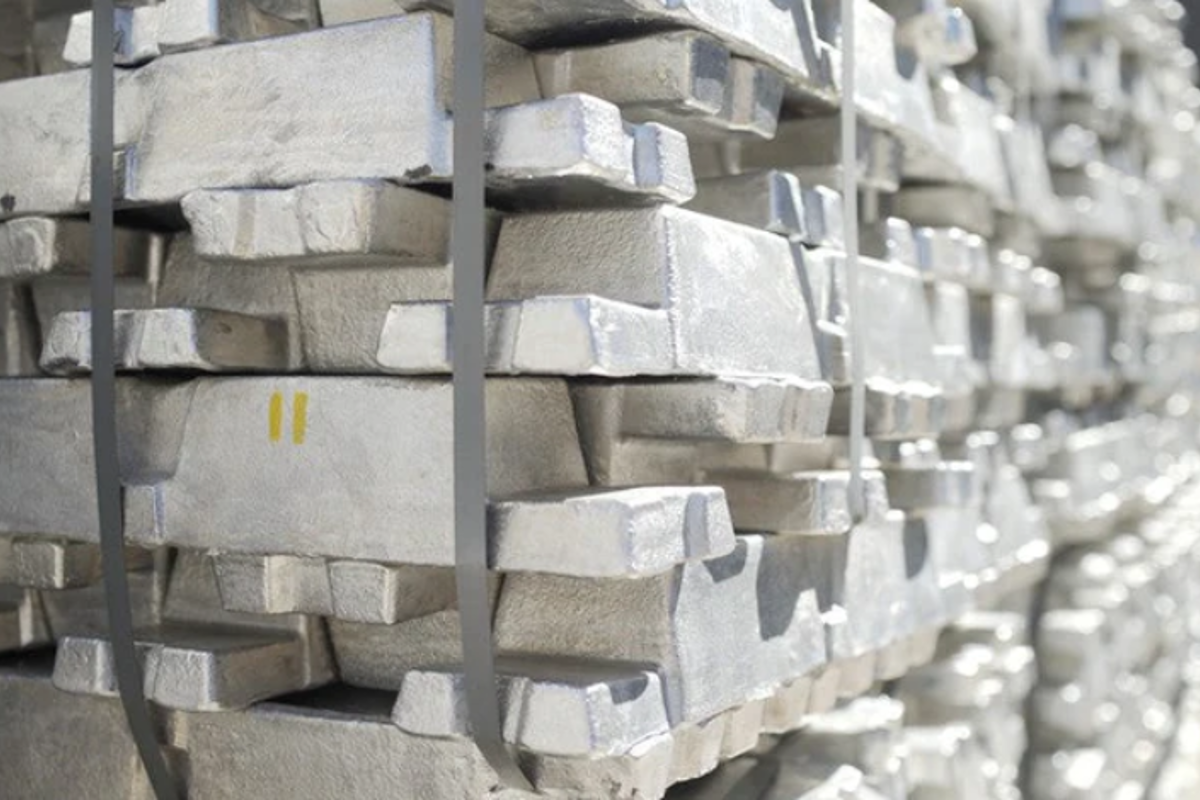
Image credit: Aluminium Warehouse, UK












_md.webp)
_md.webp)
_md.webp)