02 AUGUST 2012Hedgeweek.com
Experts analyze copper and aluminium price trends for 2012 second half
Edited by : AL CIRCLE
4 min read

With in the S&P GSCI Enhanced Commodity Index, industrial metals returned -4.7 per cent through early June 2012. Whilst not exactly exciting, the space at least held up stronger than energy, which was down 11.1 per cent. Widespread deleveraging and a move to net speculative short positioning in response to continued fears in the eurozone have caused some analysts to revise down their short-term forecasts, with Goldman Sachs, for example, reducing its three-month forecast for copper from USD9,000/mt to USD8,000/mt.
As the Goldman Sachs team wrote in their Commodity Watch report on 11 June 2012, despite reducing their near-term forecasts their base case is still for solid upside on a three-month basis in aluminium (+11 per cent) and copper (+10 per cent). The house view is even more positive for Q4 2012 and is based on the macroeconomic assumption that the US will engage in QE3, Europe will develop a sufficient policy response and China will loosen its monetary policy.
Goldman’s average price forecast for aluminium and copper in Q4 is USD2,400/mt and USD9,000 respectively.
Despite weak macro data, the micro fundamentals for copper have been resilient in 2012. On the one hand ex-China demand has softened (particularly in Europe), but on the other hand demand for social housing construction projects in China has supported consumption levels.
What’s more, because mine supply has been coming in lower than expected, the copper market has been in deficit since April; globally, inventories in copper have been declining on a seasonally-adjusted basis.
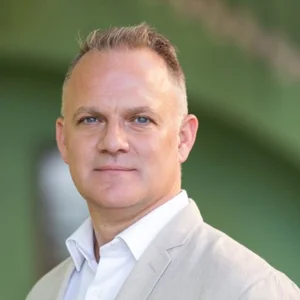
Daniel Brebner (pictured) is Head of Metals Research at Deutsche Bank. Expanding on the macroeconomic view shared by Goldman Sachs, Brebner thinks that based on global physical fundamentals “prices are likely higher than they should be”, due to the expectations of further monetary easing by China, the US and Europe in Q3. “
Brebner confirms that Deutsche Bank’s Q4 average price forecasts across the base metals complex are: copper, USD8,200/t; aluminium, USD2,100; nickel, USD19,000/t, and zinc, USD2,000/t.
Sanjay Saraf, Director of Metals Research at GFMS – a Thomson Reuters firm - has the same Q4 price forecast for copper as Brebner at USD8,200/t and thinks that copper has scope to outpace the other base metals “if we see Chinese demand coming back rapidly”.
Aluminium prices – which have fallen from USD2,151/mt to USD1,885/mt through June – now represent good short-medium term risk reward with Goldman Sachs’s trade recommendation being long September 2012 aluminium USD2,150/mt calls at a premium of USD18.8/mt.
“With minimal to no growth in output likely at current prices (even from supposedly low cost areas such as Xinjiang and Gansu in China), any significant growth in aluminium consumption would result in aluminium tightening and prices moving higher,” wrote the research team.
Aluminium prices on average are probably the ones that have fallen furthest below their marginal costs of production. Because of this, Saraf thinks that the downside risk for aluminium is relatively limited, noting that producer results are already showing that margins are being squeezed.
Aluminium’s large stock overhang means that further production cutbacks are needed before prices start to recover. Interestingly, as Brebner alludes to above, even though producers like Alcoa in Europe are already beginning to do this, the regional government in Henan Province, China recently introduced power price subsidies to prevent further cutbacks after levels were cut by 700,000 tonnes.
The Goldman Sachs team does not think that such a stock overhang will hinder price recovery in aluminium, pointing to the fact that it traded up to USD2,800/mt in early 2011 with similar overcapacity and stock levels to that seen today.
Looking ahead into 2013, Deutsche Bank’s Brebner believes that further monetary expansion will improve conditions in base metals: “We remain worried, however, that the spectre of deflation could once again emerge to put renewed and possibly more forceful downward pressure on the complex in late 2013.”
As the Goldman Sachs team wrote in their Commodity Watch report on 11 June 2012, despite reducing their near-term forecasts their base case is still for solid upside on a three-month basis in aluminium (+11 per cent) and copper (+10 per cent). The house view is even more positive for Q4 2012 and is based on the macroeconomic assumption that the US will engage in QE3, Europe will develop a sufficient policy response and China will loosen its monetary policy.
Goldman’s average price forecast for aluminium and copper in Q4 is USD2,400/mt and USD9,000 respectively.
Despite weak macro data, the micro fundamentals for copper have been resilient in 2012. On the one hand ex-China demand has softened (particularly in Europe), but on the other hand demand for social housing construction projects in China has supported consumption levels.
What’s more, because mine supply has been coming in lower than expected, the copper market has been in deficit since April; globally, inventories in copper have been declining on a seasonally-adjusted basis.
Daniel Brebner (pictured) is Head of Metals Research at Deutsche Bank. Expanding on the macroeconomic view shared by Goldman Sachs, Brebner thinks that based on global physical fundamentals “prices are likely higher than they should be”, due to the expectations of further monetary easing by China, the US and Europe in Q3. “
Brebner confirms that Deutsche Bank’s Q4 average price forecasts across the base metals complex are: copper, USD8,200/t; aluminium, USD2,100; nickel, USD19,000/t, and zinc, USD2,000/t.
Sanjay Saraf, Director of Metals Research at GFMS – a Thomson Reuters firm - has the same Q4 price forecast for copper as Brebner at USD8,200/t and thinks that copper has scope to outpace the other base metals “if we see Chinese demand coming back rapidly”.
Aluminium prices – which have fallen from USD2,151/mt to USD1,885/mt through June – now represent good short-medium term risk reward with Goldman Sachs’s trade recommendation being long September 2012 aluminium USD2,150/mt calls at a premium of USD18.8/mt.
“With minimal to no growth in output likely at current prices (even from supposedly low cost areas such as Xinjiang and Gansu in China), any significant growth in aluminium consumption would result in aluminium tightening and prices moving higher,” wrote the research team.
Aluminium prices on average are probably the ones that have fallen furthest below their marginal costs of production. Because of this, Saraf thinks that the downside risk for aluminium is relatively limited, noting that producer results are already showing that margins are being squeezed.
Aluminium’s large stock overhang means that further production cutbacks are needed before prices start to recover. Interestingly, as Brebner alludes to above, even though producers like Alcoa in Europe are already beginning to do this, the regional government in Henan Province, China recently introduced power price subsidies to prevent further cutbacks after levels were cut by 700,000 tonnes.
The Goldman Sachs team does not think that such a stock overhang will hinder price recovery in aluminium, pointing to the fact that it traded up to USD2,800/mt in early 2011 with similar overcapacity and stock levels to that seen today.
Looking ahead into 2013, Deutsche Bank’s Brebner believes that further monetary expansion will improve conditions in base metals: “We remain worried, however, that the spectre of deflation could once again emerge to put renewed and possibly more forceful downward pressure on the complex in late 2013.”
Previous article
Sterlite Industries updates on Vedanta Aluminium Limited
Next articleSHFE 1211 contract opened lower at RMB 15,385/mt on August 1
Grow with
AL Circle