Whenever there is a question of pricing, the aluminium industry has pointed towards a single influx inducer — electricity. If you’ve ever toured a smelter or skimmed an investor deck, you’ll hear the same refrain, “power is king, and aluminium is electricity in solid form”. But, as Maros Durka, Area Sales Manager at Grupa Kety, states, that is only half the truth. Yes, electrolysis eats megawatts like popcorn, but if power were the only story, Europe’s aluminium would be cheap and cheerful by now. After all, Europe boasts the cleanest smelters on earth, with over 78 per cent of output powered by renewables. And yet, paradoxically, European primary aluminium is still the world’s priciest.
So, what gives? Why are Europe’s ‘green’ tonnes also the most expensive ones?
Let’s start with the cost stack. Smelting is brutally energy-intensive. Depending on whose spreadsheet you read, electricity plus heat makes up 35-45 per cent of the bill, raw materials like alumina another 30-35 per cent, with the rest split between labour, maintenance, logistics and a sprinkling of compliance costs. If you zoom out, that looks straightforward: electricity dominates.
But, it’s not the source of the electrons that sets the price; it’s the market.
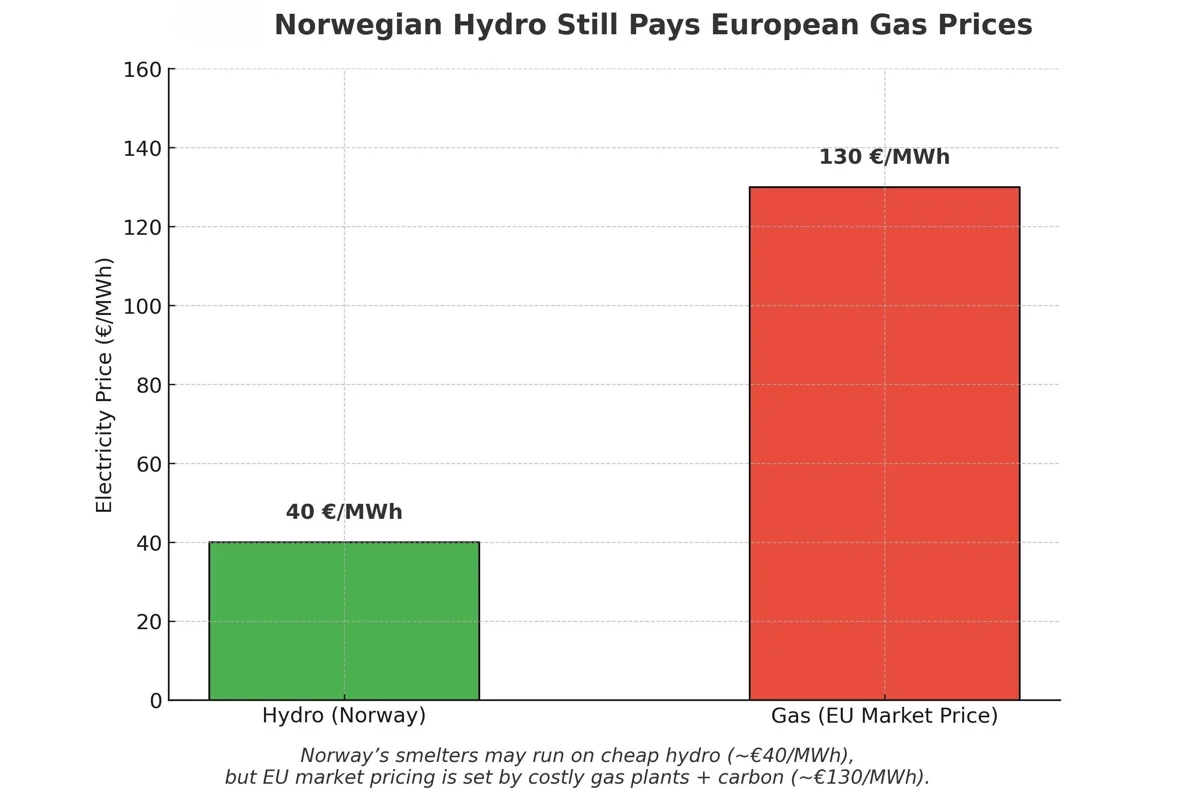
Even if a smelter in Norway runs on cheap hydro power, it still has to pay prices set by the wider market, which is driven by costly gas plants and EU carbon charges.
Europe’s marginal pricing system is like a restaurant where everyone pays the bill of the most expensive diner. When gas is the marginal generator, everyone — even wind and hydro — gets billed at gas-plus-carbon levels.
From Alcoa’s Iceland gamble to Europe’s energy crunch
The marriage between aluminium and cheap power has always been one of geography and politics. In the 1970s, when Alcoa signed its pioneering deal to anchor a smelter in Iceland, the logic was simple: tap the island’s abundant hydro, secure a century of low-cost electricity, and ride the aluminium cycle without being hostage to oil shocks. That gamble paid off. Iceland, with virtually no bauxite of its own, became a major exporter of aluminium by virtue of waterfalls and lava fields. A similar template was later mirrored in Norway’s hydropower-driven smelting and in Canada’s hydro-rich Quebec.
By contrast, continental Europe’s smelters tied themselves to fossil-linked grids and, in the 1990s and 2000s, liberalised power markets. When the EU pushed deregulation and carbon pricing, the bet was that open markets and emissions caps would drive both efficiency and cleaner power. What no one foresaw was the perfect storm of the 2020s: the Russian gas cut-off after 2022, ETS prices soaring past €90/tCO₂, and a belated renewables boom that created negative-price hours but not firm baseload for 24/7 industries. The result was brutal. By 2023, Europe had lost nearly half its smelting capacity, relying more on imports from the Gulf, Africa, and Russia’s sanctioned shadow trade.
A price gap the size of an ocean
Numbers tell the story best. The US, cushioned by shale gas and now by the IRA’s industrial sugar rush, delivered industrial electricity at around USD 70 pwe MWh in 2024. China hovered around USD 90, thanks to state-regulated tariffs and subsidies.
India, despite rising demand, is stuck in the USD 110–115 range. Europe? Still slogging at USD 130 in 2024 after peaking at a jaw-dropping USD 250 in 2022. That’s not a price gap; that’s a canyon.
The IEA’s data show that between 2019 and 2024, energy-intensive industries in Europe consistently paid more than their US and Chinese rivals. Even in 2025, when wholesale prices cooled, the average EU smelter remained shackled to higher bills than competitors across the Atlantic or the Pacific. In other words, Europe is greening faster, but paying more for the privilege.
When “green” doesn’t mean “cheap”
So why hasn’t Europe’s renewable boom translated into industrial bargains? Two reasons:
- Negative-price hours are growing across Germany, Spain, and the Netherlands. Great for headlines, useless for smelters running 24/7 potlines. You can’t pause electrolysis for a few cheap hours and restart when prices spike. Without flexible demand contracts or firm power purchase agreements, smelters remain price-takers.
- The EU’s ETS works like an invisible tax. Even if aluminium smelters cut their direct emissions, their electricity supplier still pays for carbon allowances — and happily passes the bill along. Member states offer partial compensation, but it’s patchy, and it doesn’t cancel out the structural gap.
This is why being powered by renewables does not immunise Europe’s smelters from high electricity prices. The electrons may be green, but the market makes them expensive.
In 2024, Europe witnessed a historic shift in electricity generation to renewables (wind, solar, hydro, etc.), which accounted for nearly 48 per cent of the EU’s power mix, the highest ever, while fossil fuels shrank to just 28 per cent, marking a long-awaited turning point in energy economics.
Yet when we look at the bottom-line costs per MWh, renewables still hold a clear edge. Across Q1–Q3 2024, the levelized cost of wind- and solar-generated electricity ranged between EUR 40-46 per MWh, while hydro clocked in at about EUR 41 per MWh, all cheaper than brown coal (EUR 52 per MWh) or natural gas (EUR 93 per MWh).
In the first half of 2024, renewables didn’t just dominate generation — they started to dominate pricing dynamics, too. Wind and solar together surged to 30 per cent of total EU electricity, surpassing fossil fuels, which dropped to 27 per cent, even as overall demand ticked up. On the wholesale front, this shift helped trigger a rise in negative-price episodes: 15 per cent of hours in H1 recorded zero or negative prices, moments when renewables flooded the grid and outcompeted fossil-fired units.
That isn’t just a fun headline! It bolds and highlights how renewables are increasingly not just cleaner, but often cheaper than traditional energy in the spot market context.
Other silent cost drivers
If electricity is the loud villain, Europe’s aluminium also suffers from a supporting cast of subtler, equally costly antagonists.
- Raw materials: Europe imports most of its bauxite and now increasingly its alumina. That means shipping, insurance, and freight volatility. Every hiccup in the Red Sea or West Africa shows up on the invoice in Düsseldorf.
- Scale: Since 2021, Europe has mothballed roughly half its smelting capacity during the energy crisis. That left fixed costs spread across fewer tonnes, inflating unit costs. You don’t get “economies of scale” when your scale is shrinking.
- Compliance: Between ETS, CBAM, and national levies, Europe’s aluminium industry pays for being clean — and for others being dirty. Compare that to the US, where the Inflation Reduction Act is basically writing cheques to aluminium plants, or China, where provincial governments underwrite cheap power deals.
- Logistics and geopolitics: Sanctions on Russian aluminium, shifts in global trade, and CBAM’s looming teeth all tighten supply and jack up premia in Europe. Clean supply chains are admirable, but they’re not cheap.
- Labour premium: If electricity is the loud villain of Europe’s aluminium story, labour is the quieter accomplice. Globally, labour makes up 10–15 per cent of the smelting cost stack. In China or India, that slice stays at the low end thanks to relatively cheap wages. In Europe, however, wages, social security contributions, and stricter workplace standards push labour costs toward the upper end. Eurostat data show average hourly labour costs in manufacturing at around €30–35 in 2024, compared with roughly USD 5–6 in China and under USD 3 in India.
The Nordic exception — and why it proves the rule
Take Iceland and Norway. They run almost exclusively on hydro and geothermal, often under long-term fixed contracts. Their smelters churn out aluminium with among the world’s lowest carbon footprints and, crucially, lower costs. But here’s the catch: they’re exceptions because they’re blessed with unique natural resources. Europe’s continental smelters can’t all relocate to Reykjavik. And even in the Nordics, exposure to EU markets and policy frameworks means costs creep higher than pure “hydro logic” would suggest.
Europe’s aluminium sector has effectively been given two conflicting missions:
- Decarbonise faster than the rest of the world.
- Stay globally competitive on price.
Right now, it’s acing Mission One, failing Mission Two.
Think tanks like Bruegel argue that structural fixes are possible: redesigning electricity markets to reduce gas marginality, slashing taxes and levies on industrial power bills, accelerating grid build-out, and lowering financing costs for renewables. Without that, Europe risks becoming the world’s greenest aluminium importer — outsourcing production but importing tonnes at higher premia.
Though Europe has achieved the paradox of building the cleanest aluminium sector in the world, only to watch it shrink and surrender market share. Unless the stakeholder and national + international policy builders crack the code on competitive green power, European aluminium risks becoming a boutique product: low-carbon, high-cost, and ultimately marginalised in a global market that still rewards cheapness first.












_md.webp)