Over 100 mining licences were cancelled in Guinea, where big names like EGA have made headlines. But how many China-owned firms have been the target of Guinea’s ‘mine here, refine here regime’? The answer is a big-n-bold ZERO. The only report that deep search found when AL Circle was investigating the matter was of the single active operation affected by this crackdown of a joint venture in the Boffa-Fria corridor that included the Chinese-backed company SD Mining SA, which held a 42 per cent stake.
Naturally, the question arises as to why Guinea has been cooperating with China when it comes to mining (we are mainly concerned about bauxite). For over 30 years, China has actively supported Guinea in various aspects. But why? As we dig deep, it seems to be clearing layer by layer.
Early foundation of the cohort
The robust economic relationship between China and Guinea, particularly in the bauxite sector, is not a recent development but rather the culmination of a political and diplomatic alliance forged over more than six decades. The People’s Republic of China and the Republic of Guinea established diplomatic relations on October 4, 1959, making Guinea the first sub-Saharan African nation to do so. This early commitment was strategically significant, as it occurred during a period of intense global Cold War tensions and the Sino-Soviet split, which had left China seeking to expand its international influence and break its diplomatic isolation.
During the 1960s, China actively sought alliances with newly independent African nations. Guinea, under the leadership of Ahmed Sékou Touré, had resisted French colonial control and favoured socialist principles, a standpoint that echoed deeply with China’s own revolutionary ideology.
The shared anti-imperialist and anti-colonial sentiment became the ideological bedrock of the bond. China solidified this solidarity through significant economic and technical assistance, demonstrating its commitment to the development of Third World countries. Early projects included the construction of the People’s Palace and hydropower stations such as Kinkon and Tinkisso. China also began sending medical teams to Guinea in 1968, a practice that has continued to this day, with 30 teams and 725 personnel dispatched over the years.
The secret ingredient to a long-lasting relationship
Guinea’s cooperation with China in the bauxite sector is a direct result of a strategic alignment between China’s vertically integrated, state-backed investment model and Guinea’s national development objectives. The analysis indicates that Guinea is not a passive partner but one with a clear, nationalistic agenda to move up the value chain from raw material exporter to a producer of refined and semi-finished goods. China’s approach has been uniquely tailored to meet this demand.
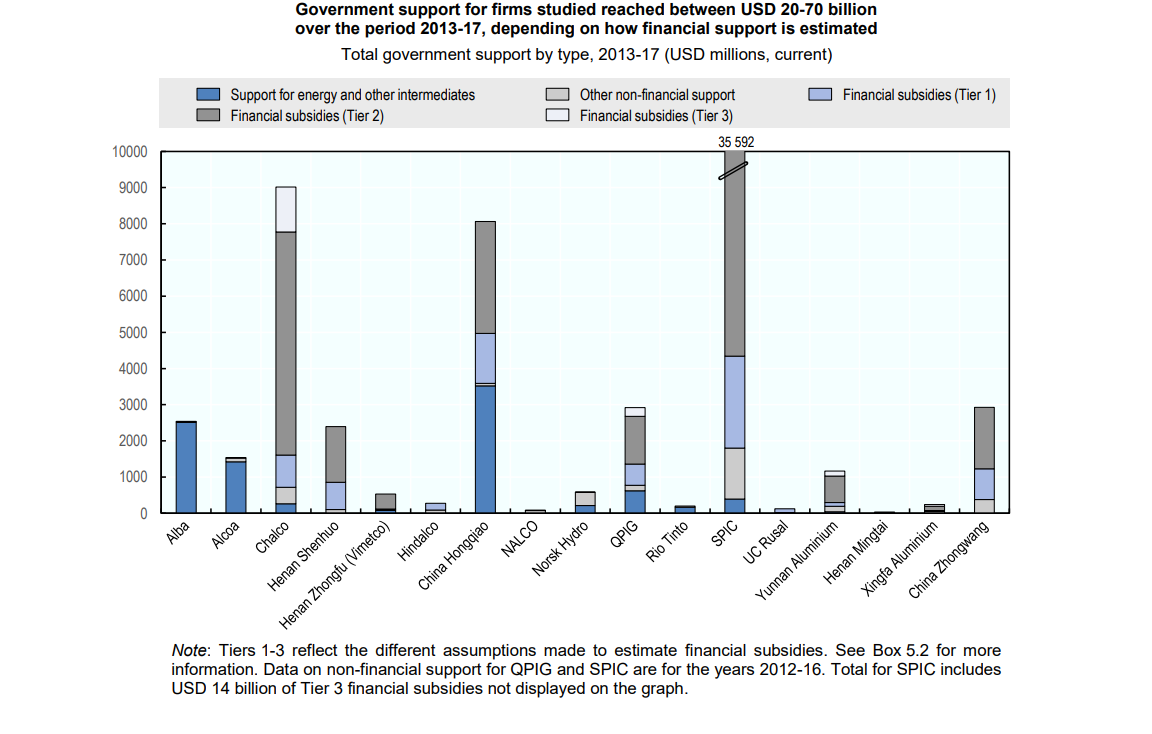
A prime example of this model is the USD 20 billion loan agreement China granted to Guinea over 20 years in September 2017 in exchange for bauxite concessions. This ‘resource-for-infrastructure’ model provides Guinea with desperately needed development funding while guaranteeing China long-term access to a critical resource supporting major, integrated projects by Chinese state-owned enterprises (SOEs).
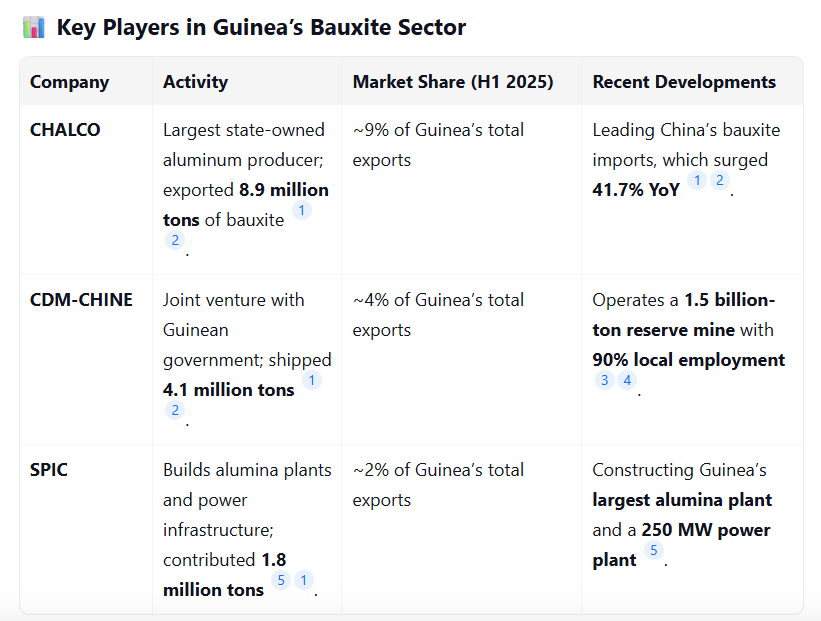
For instance, Chalco received mining licenses for the Boffa bauxite project. Concurrently, China’s State Power Investment Corporation (SPIC) is constructing a large alumina refinery with an expected capacity of 1.2 million tonnes annually, along with a 250 MW power plant, which directly addresses Guinea’s two biggest development challenges: a) a lack of refining capacity and b) persistent power shortages.
According to the data by AInvest, Guinea’s bauxite sector is led by three major Chinese companies, namely CHALCO (Aluminium Corporation of China), CDM-CHINE (a joint venture between a Chinese firm and the Guinean government), and State Power Investment Corp (SPIC).
Historically, Western firms were the first foreign investors in Guinea’s bauxite, with US-based Alcoa and Anglo-Australian Rio Tinto being major players in the Compagnie des bauxites de Guinée (CBG) consortium. Russia’s Rusal is also a significant presence, owning the Kindia Bauxite Company (CBK) and the Friguia alumina refinery.
However, China’s investment has grown at an astonishing rate. From 2016 to 2023, Guinea’s bauxite exports to China surged by an extraordinary 731 per cent. The primary driver for this was Indonesia’s 2023 export ban, which forced China to redirect its annual bauxite procurement to Guinea, increasing its market share from 58 per cent to 82 per cent within a single year.
The rise of an industrial titan (read Chinese aluminium)
To fully comprehend China’s deep-seated interest in Guinea’s bauxite, one must first analyse the meteoric rise and subsequent strategic vulnerabilities of its domestic aluminium industry. China has transformed itself into a global industrial titan, accounting for nearly 60 of the world’s primary aluminium smelter capacity in 2024, a monumental increase from just 11 per cent in 2000. This explosive growth was initially fuelled by a historic, decades-long construction boom that drove insatiable demand for aluminium in buildings, infrastructure, and consumer goods.
More recently, the industry has pivoted to serve strategic, high-value sectors such as electric vehicles (EVs), high-speed rail, aerospace, and consumer electronics.
This rapid expansion has not always been the hunky dory that it seems to be! While China has developed a massive, state-of-the-art aluminium industry, its domestic bauxite reserves are of low quality, averaging just 30-35 per cent aluminium oxide content. This quality differential means that the Chinese industry cannot function efficiently or competitively without a steady supply of high-grade, imported raw materials. Thus comes in the role of the high-grade bauxite reserve owning nation — Guinea.
What about the financials?
Simultaneously, when it comes to funding, investing or rather than relying on traditional market-based loans or the sporadic investments of private firms, China employs a state-backed, strategic model.
The primary mechanism is the “resource-for-infrastructure” model, as seen in the USD 20 billion loan to Guinea in exchange for bauxite concessions. This model, also used in countries like Angola for oil, bypasses conventional financing channels and provides a direct, low-bureaucracy solution to a host country’s development needs.
Funding is provided by specialised state-backed financial institutions, which act as agents of China’s national strategy. These include policy banks such as the China Export-Import Bank (EximBank) and the China Development Bank (CDB).
EximBank, for example, is the sole lending bank for Chinese Government Concessional Loans and provides low-rate loans to facilitate large-scale infrastructure projects that serve a “dual Chinese and African interest”.
Similarly, the China-Africa Development Fund (CAD Fund), a government guidance fund, provides equity investment and support for Chinese enterprises operating in Africa, helping to de-risk projects and share investment burdens.
While Western lending is often tied to stringent political or economic conditions, and private firms are hesitant to absorb political risk in unstable regions, China’s model offers a comprehensive “package deal”. The Chinese government, through its policy banks and funds, provides the financing, while its state-owned enterprises build the infrastructure, all with the explicit goal of securing a long-term strategic resource.
Who wins “fair and square”?
The question of who wins “fair and square” is complex and requires a balanced assessment of gains and risks for both nations. The answer is not a simple zero-sum equation, but rather a nuanced picture of strategic interdependence where both sides are successfully pursuing their objectives.
From a Guinean perspective, the partnership is a powerful engine for national development. The mining sector is a central pillar of the economy, accounting for an estimated 18 per cent of GDP, 79 per cent of exports, and 31 per cent of government revenue.
Chinese investment has financed massive, desperately needed infrastructure projects, including new ports and railways, which have more than doubled Guinea’s export capacity and connected mines to the coast. The government has also demonstrated an increasing ability to leverage its position. The introduction of a “reference price” for bauxite in 2022 is expected to generate tens of millions of dollars in additional annual revenue by combating the historical practice of underpricing.
However, these gains come with significant risks. Guinea’s heavy reliance on China for its bauxite exports, with Chinese-controlled firms commanding over 60 per cent of shipments, creates a profound economic dependency and leaves the country vulnerable to fluctuations in Chinese demand. Historically, the paradox of high export volumes yielding only incremental revenue growth was a major problem, though the new “reference price” is a step toward addressing this.
Furthermore, the country’s political instability poses a constant risk to foreign investment, a factor highlighted by the recent disruptions.
For China, the strategic gains are immense. It has secured a dominant, long-term supply of the highest quality bauxite in the world, which is critical for its industrial future. This supply fuels its massive aluminium industry, giving it a key strategic advantage in the global market. The partnership also extends China’s soft power and strategic influence in a resource-rich region, an important component of its Belt and Road Initiative.
The risks for China, however, are also notable. Its deep investment exposes it to Guinea’s political instability and the potential for supply chain disruptions, as seen during the 2023 coup. It must also continually navigate Guinea’s demands for greater value addition and revenue, as demonstrated by the revocation of EGA’s license.













_md.webp)