03 APRIL 2014www.commodityonline.com
Aluminium may witness down and short covering
Edited by : AL CIRCLE
3 min read

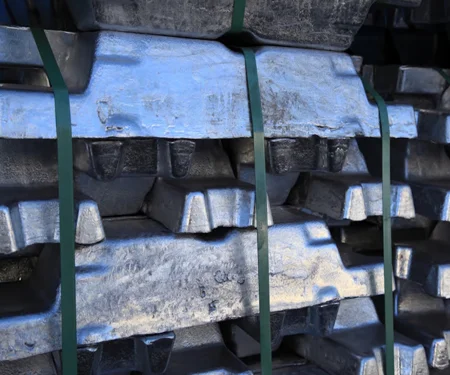
Aluminum edged down after the initial consolidation in the month of March on back of worries about spreading bank-ruptcies in China, after a solar panel-maker defaulted on a bond payment, sending prices to 9 months low. The looming bankruptcy of a Chinese devel-oper owing billions of yuan to domestic banks has raised worries that a softening proper-ty market is heightening risks for the financial system. The counter fell further on concerns about the economy of top consumer China following data showing weak industrial output and retail sales. Adding to fears was Chinese data show-ing growth in investment, retail sales and factory output falling to multiyear lows.
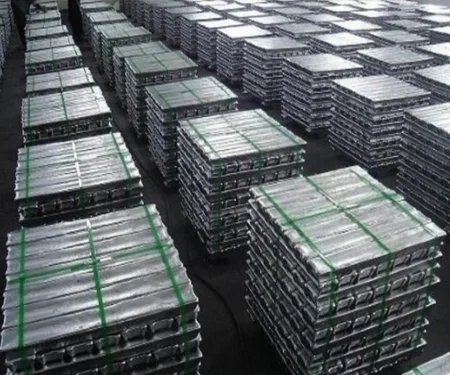
The market was already edgy over slowing Chinese demand and fears that credit upheaval in the world's second-biggest econo-my could unwind financing deals using the metal as collat-eral. Shanghai aluminium futures fell to their lowest since inception in the last week of the month, dogged by oversup-ply and tightening credit that has eroded demand. China's aluminium production this year is expected to outpace even last year's levels, which has driven down prices.
China's aluminium smelters are likely to shut about 2 million tonnes of operating capacity in the coming months as they try to limit losses amid falling prices and dwindling government support, industry sources said. Chinese run-rates also surged by an annualized 1.1 million tonnes in February, hitting a fresh high of 23.9 million tonnes, while China's aluminium production grew 10 per-cent to 22 million tonnes last year.
In the meantime, daily average primary aluminium output excluding China rose to 66,800 tonnes in February, from 66,100 tonnes in Janu-ary, data from the International Aluminium Institute (IAI) showed. Global production for February, excluding China, was 1.869 million tonnes, down from a revised 2.05 mil-lion tonnes recorded in Janu-ary. In China, daily average output rose to 65,500 tonnes in February against 62,500 tonnes in the January. Total Chinese production in Febru-ary was 1.833 million tonnes from 1.938 million tonnes in January, the IAI said. Else-where, world production in every region other than the Middle East Gulf is stagnating or falling as producers shutter higher-cost capacity. Gulf pro-duction, by contrast, is boom-ing, reflecting the ramp-up of the new Ma'aden smelter in Saudi Arabia and of the new expanded capacity at the EM-AL smelter in Abu Dhabi.
Aluminum rebounded sharply after falling for four consecu-tive weeks and testing the support around Rs 101.50 /Kg. The prices saw a steady de-cline from near Rs110/kg lev-els from the beginning of March but selling got abated near Rs101.50/kg levels, where the bulls jumped in and outnumbered the bears. The prices are still trading in a downward sloping channel with its resistance placed around Rs109 - 109.50/Kg region on the weekly charts. Any fresh up move will be seen only in case of a decisive close above the said range, which may result in an up move towards Rs112/Kg levels, on the back of short cov-ering and fresh buying. On the lower side while the counter is expected to hold the support of Rs101 and Rs99/Kg. The strategy for the month will be to buy on dips with a keen eye on the support mark of Rs 98.50/Kg levels.
Previous article
Clarification
Next articleAluminum producers expect Brazil to ration power within a year
Grow with
AL Circle