PV Aluminium frame enterprises see divergent operating rates with leading players holding steady; aluminium prices expected to consolidate on a subdued note amid macro and production resumption expectations
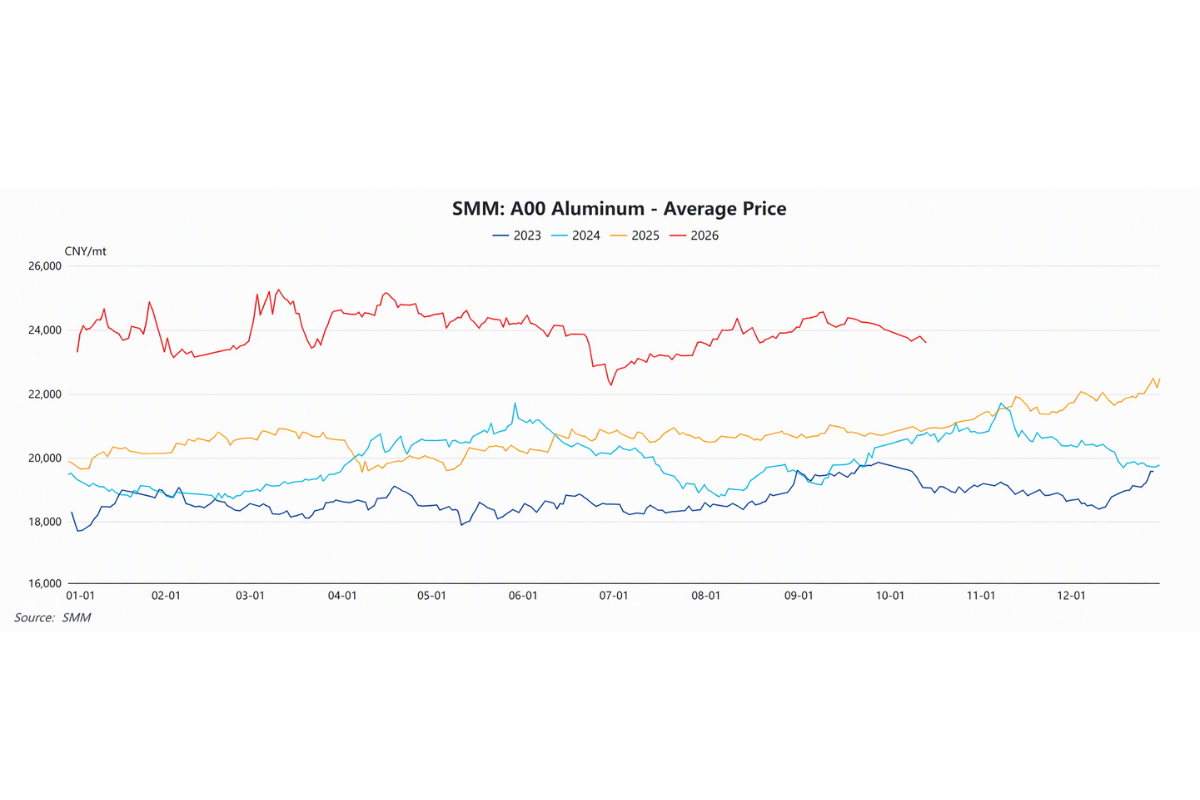
The image used in this article is from SMM
PV aluminium extrusion: This week, operating rates among sampled PV frame enterprises showed divergence. Some top-tier PV frame enterprises in Anhui and Hebei continued to run at relatively full operating rates; some other small and medium-sized integrated industrial extrusion enterprises reported that, for profitability considerations, they have proactively controlled production and reduced PV frame orders after the holiday, but their PV frame orders are limited, having little impact on the overall PV aluminium extrusion operating rate. From the downstream module side, October module scheduled production is expected to edge up from September, but the growth falls short of expectations, with China's scheduled production increasing by only 1-2 GW, providing limited support for PV-related aluminium extrusion demand. Structurally, since September, centralised project tenders in China have regained momentum and project deliveries have increased accordingly, constituting the main support for module production; distributed orders have contracted somewhat. Overall, order deliveries at top-tier players still support operating rates, and PV frame operating rates are expected to remain stable in the short term; however, module scheduled production growth falling short of expectations, combined with contracting distributed demand, leaves PV aluminium frame demand lacking clear upward drivers, with relatively limited upside for operating rates.
Raw material prices: During the period (2026.10.11-2026.10.15), the SMM A00 weekly average price was RMB 23,600 per tonne, down 2.1 per cent from the pre-holiday weekly average price (2026.9.28-2026.9.30). Overall, on the macro front, rising expectations for US Fed interest rate hikes, a strong US dollar, and high US Treasury yields continued to weigh on nonferrous metal valuations; on the fundamental side, production resumptions and new capacity outside China continued to suppress short-term futures sentiment. Aluminium prices are expected to consolidate on a subdued note next week, with the most-traded SHFE aluminium contract trading in the range of RMB 22,500-23,500 per tonne and LME aluminium at USD 2,850-3,050 per tonne.
Note: This article has been shared by SMM and has been published by AL Circle with its original information without any modifications or edits to the core subject/data.
Grow with
AL Circle