Powering progress: ASEAN’s clean energy momentum and aluminium sector’s low-carbon shift
ASEAN’s shift to renewable energy is being slowed not by technology or cost. Although solar PV prices have plunged 80 per cent and battery costs by 70 per cent over the past decade, the region lacks unified policy frameworks like harmonised renewable energy certificates, emissions accounting, and coherent regional regulations.
Southeast Asia is positioned at a critical juncture in its energy transition, with electricity demand across the ASEAN bloc expected to rise by 30 per cent by 2030, driven by urban expansion, higher income levels and accelerating digitalisation. Moreover, the government is underway to demonstrate rapid clean energy deployment, which is significantly possible under promising conditions.
Vietnam & Indonesia’s energy collaboration
Vietnam, in 2020, became the third-largest solar market in the world, where they have successfully installed a capacity of 17GW, which surpassed the target set to be achieved by 2025. This growth was witnessed owing to government subsidies, clear timelines, an open posture toward private capital and supplemented by a coherent feed-in tariff policy.
This region leads the ASEAN region in terms of regulatory readiness and returns on current renewable energy projects, positioning itself as the top investment destination for renewables across Southeast Asia.
Indonesia and Vietnam have secured multibillion-dollar Just Energy Transition Partnerships (JETPs) with G7 countries and multilateral financial institutions. These agreements are designed to fast-track coal phase-out initiatives and enable large-scale renewable energy development through concessional financing and targeted capacity-building support.
Singapore’s energy policy framework
Despite its limitations in land and natural resources, Singapore has strategically established itself as a regional green finance and technology hub. By implementing official taxonomies and disclosure frameworks that define sustainable economic activities, Singapore aims to attract both domestic and international capital into climate-aligned investments across ASEAN.
In 2023, the region secured only USD 32–40 billion in clean energy investments, significantly short of the estimated USD 150-200 billion required annually. Singapore’s evolving leadership in mobilising global financing for ASEAN’s energy transition positions it as a key driver in bridging this investment gap.
In 2022, Singapore commenced renewable energy imports through the Lao PDR–Thailand–Malaysia–Singapore Power Integration Project (LTMS-PIP), marking a regional milestone as clean electricity generated in Laos was transmitted across three national borders and delivered to end users in Singapore for the first time.
While the LTMS-PIP proved technically successful, the supporting policy framework remains underdeveloped. ASEAN continues to face a lack of harmonised regulations for renewable energy certificates, emission factors and carbon accounting.
Global primary aluminium smelting power consumption
According to data from International Aluminium, global primary aluminium smelting power consumption reached 957,084 GWh in 2023. Of this, coal accounted for 478,301 GWh, hydro for 316,900 GWh, natural gas for 94,493 GWh, and other renewables for 56,021 GWh.
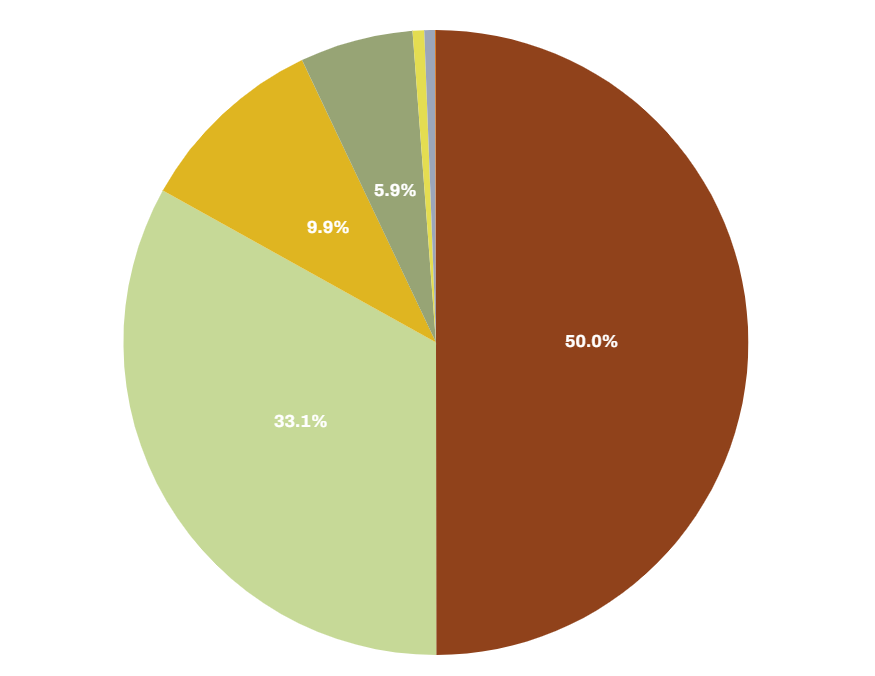
Image source: International Aluminium
Asia’s primary aluminium smelting power consumption
In the same year, primary aluminium smelting power consumption in Asia (excluding China) stood at 55,102 GWh. The energy mix comprised 47,525 GWh from coal, 935 GWh from hydro, 5,177 GWh from other non-renewables, and 1,463 GWh from other renewables.
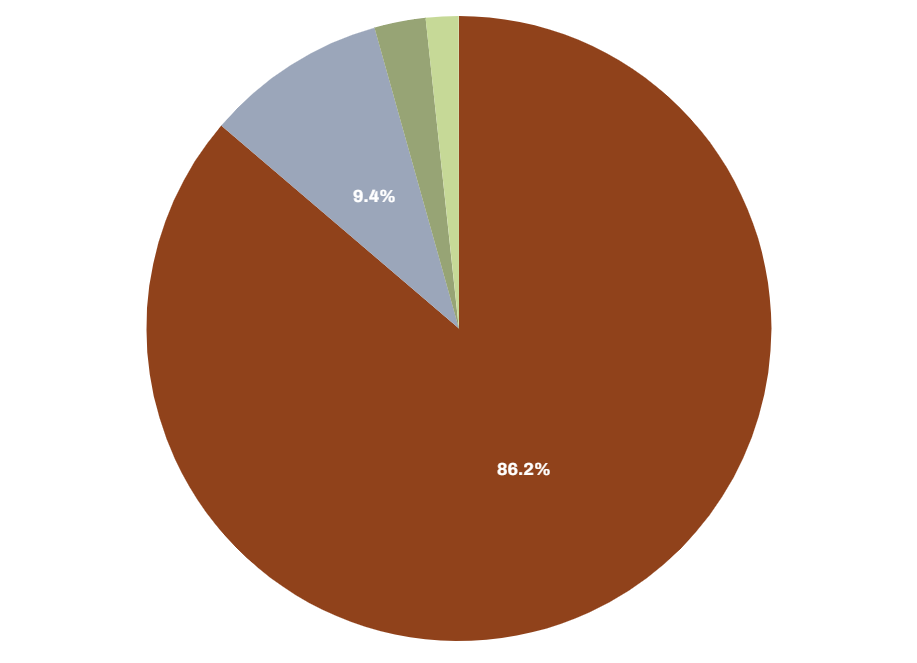
Image source: International Aluminium
Technology point of view for clean energy transition
From a technology standpoint, the tools required for decarbonisation have moved beyond the conceptual stage. Smart microgrids integrating solar power, battery storage and advanced digital control systems are actively being implemented in off-grid areas across Indonesia and Malaysia.
Simultaneously, Singapore-based digital services firm Temus has co-developed an environmental intelligence platform leveraging AI, sensors and data analytics to improve monitoring of carbon stocks, biodiversity and land use. These digital innovations are enabling the valuation of natural capital and facilitating more informed, sustainability-driven investment decisions in resource-rich markets such as Indonesia.
Role of AI in the energy transition
AI-powered energy management systems (EMS) are becoming essential for enhancing grid efficiency, enabling real-time optimisation of electricity supply and demand. Without such adaptive technologies, ASEAN risks facing grid instability, challenges already witnessed in Spain’s 2021 solar surge and California’s 2020 rolling blackouts, where supply-demand mismatches compromised grid reliability.
Emerging technological solutions
In a regional example, Thailand’s Provincial Electricity Authority has piloted EMS solutions that have reportedly achieved peak load reductions of up to 8 per cent, demonstrating the tangible benefits of intelligent grid management.
Modular solar and battery energy storage systems are increasingly demonstrating their effectiveness in archipelagic nations. In the Maldives, an Asian Development Bank-supported initiative has deployed these systems across over 160 islands, significantly reducing reliance on diesel fuel and generating substantial annual savings in fuel expenditure. This model highlights the operational and economic viability of decentralised renewable solutions in geographically dispersed regions.
In addition to being technically proven and commercially viable, the costs of solar PV and battery storage have declined by over 80 per cent and 70 per cent, respectively, over the past decade. What remains critical now is the establishment of robust policy frameworks to accelerate and scale their deployment across the region.
ASEAN power grid at a glance
The ASEAN Power Grid, envisioned as early as 1997, aimed to integrate national grids into a unified regional network to facilitate large-scale cross-border renewable energy trade. A fundamental challenge lies in ASEAN’s consensus-based institutional model, which inherently slows down regulatory alignment and complicates regional integration efforts.
To address regional integration challenges, some countries are embracing “minilateralism”, smaller, interest-aligned partnerships focused on targeted issues. The LTMS-PIP serves as a key example. Initiated pragmatic, narrowly defined scope, outside ASEAN’s formal framework, it began as a bilateral agreement between Singapore and Malaysia, with Thailand and Laos acting as transit partners.
However, even effective strategies like minilateralism face inherent limitations. Geopolitical tensions within the region continue to hinder the broader multilateral collaboration required to scale and replicate such initiatives across ASEAN. Ongoing disputes, ranging from water-sharing conflicts along the Mekong River to overlapping territorial claims in the South China Sea, pose risks to regional trust and may delay the alignment of critical cross-border infrastructure.
Overlapping South China Sea claims impact several ASEAN nations differently. Singapore, though not a claimant, relies heavily on trade routes in the disputed waters, risking economic disruption. Laos, being landlocked, faces indirect effects through regional instability. Vietnam, a key claimant, confronts direct threats to its sovereignty, fishing zones, and energy assets. Indonesia, while largely outside the core dispute, has faced tensions near the Natuna Islands, prompting heightened maritime security.
Domestic challenges are equally significant. Much of ASEAN still relies on ageing grid infrastructure that cannot integrate large-scale solar and wind energy. According to the International Energy Agency, over 3.4 million households in the region remain without electricity access. At the same time, nearly 167 million people continue to lack clean cooking solutions, highlighting the urgent need for modernised energy systems and inclusive energy access.
Beyond technology: Focus on geopolitical & local community tensions
Beyond technology and financing, a successful energy transition also demands broad-based public legitimacy. This is where public affairs becomes essential. As Lim noted during last week’s conference, ASEAN’s clean energy future will be shaped by “connectors, navigators and advocates.” Take solar energy as an example, it earns public trust not just by generating electricity, but by demonstrating clear benefits such as reduced long-term energy costs, lower emissions, and job creation within local communities.
According to the World Economic Forum, a successful green transition in ASEAN holds the potential to boost the region’s collective economy by up to USD 5.3 trillion and generate as many as 66 million new jobs by 2050. The technologies and solutions needed for this transformation are already available. However, realising these benefits will require strong political commitment from ASEAN leaders to align national priorities with a shared, climate-resilient vision for the region.
Renewable energy usage by the global aluminium industry
In the global aluminium industry as a whole, according to the report of the International Energy Agency (IEA), over the past decade, global average direct emissions intensity in aluminium production has seen a moderate annual decline of nearly 2 per cent. However, to align with the Net Zero Emissions by 2050 (NZE) Scenario, this reduction must accelerate to approximately 4 per cent per year through 2030.
While overall energy use in the aluminium sector has risen with increased production, total energy intensity has declined by approximately 15 per cent since 2010. In primary aluminium smelting, global energy efficiency gains have been limited in recent years, as much of the industry had already approached best available technology standards over a decade ago. In contrast, alumina refining has recorded more significant energy intensity reductions since 2010.
As of now, aluminium refining and the primary aluminium production highly relies on the traditional energy due to the stable power supply. To align with the NZE Scenario, transitioning to low-emission alternatives, such as bioenergy, hydrogen or near-zero-emission electricity, is essential, particularly as most energy efficiency gains have already been realised over the past two decades.
Concluding statement
ASEAN’s energy transition is being hindered not by technology or cost, but by fragmented policy frameworks and a lack of regulatory alignment. While clean energy solutions like solar, battery storage and smart grid technologies are already proven and cost-effective, investment remains far below required levels, and ageing infrastructure continues to limit progress.
At the same time, the global aluminium sector is advancing moderately in energy efficiency and emissions reduction. Still, it must accelerate its transition to low-emission power sources to align with NZE targets. A unified policy approach and more substantial political commitment are critical to unlocking ASEAN’s renewable potential and enabling broader decarbonisation across energy-intensive sectors like aluminium.
Unlock full access – sign up for FREE.
Key benefits
Green energy surge in India: Reliance gigafactories to be operational within six quarters
Next articleCapped, committed, and carbon-conscious: China’s aluminium sector’s industrial power unveiled
Grow with
AL Circle












_md.webp)