12 NOVEMBER 2014www.moneycontrol.com
Nalco Q2 profit may jump 62% to Rs 290 cr on strong EBITDA
Edited by : AL CIRCLE
2 min read

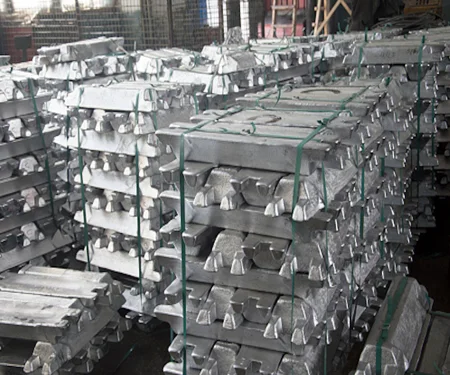
National Aluminium Company (Nalco) is expected to report a whopping 62 percent growth in profit at Rs 290 crore for July-September quarter led by company's strategy to minimise expensive coal imports. Profit in the year-ago period was Rs 179.2 crore.
Revenue is seen going up by 7 percent to Rs 1,868 crore in the second quarter of current financial year 2014-15 from Rs 1,738 crore in corresponding quarter of last fiscal aided by higher aluminum/alumina realisation and slightly higher aluminum volumes, according to the average of estimates of analysts polled by CNBC-TV18.
Operating profit may spike 42 percent on yearly basis to Rs 380 crore and margin may expand 490 basis points to 20.3 percent during the quarter on higher realisation.
Factors
Nalco had made a strategic decision to reduce exposure towards aluminium and focus on alumina. Now the company restricted aluminium production to the extent of domestic coal availability and kept power cost under check.
The company may be benefited from strong aluminum demand growth globally. Alumina has started to inch upward on strength in aluminum market.
Nalco derives around 50 percent of its revenue through alumina sales.
Key issues to watch out for are availability of coal for captive power plant and capacity utilisation of smelter.
Unlock full access – sign up for FREE.
Key benefits
Find exclusive data-driven insights and in-depth analysis
Get our daily newsletter delivered straight to your inbox
Access real-time and historical price trends from global indices
Post and respond to latest business leads
Stay ahead with alerts on learning tools
...and so much more!SIGN UP / LOGIN
Previous article
U.S. aluminum premiums soar as fabricators scramble for metal
Next articleUC RUSAL announces positive results for the three and nine months ended 30 September 2014
Grow with
AL Circle