The Middle Eastern aluminium market is poised for significant growth, with projections indicating a valuation of USD 16.68 billion by 2030, driven by a compound annual growth rate (CAGR) of 5 per cent from 2024. This burgeoning market, according to an elaborate report by NextMSC, is currently valued at USD 11.33 billion and is being fuelled by a confluence of factors, including a growing emphasis on sustainability and the region's position as a major global producer.
Global production landscape
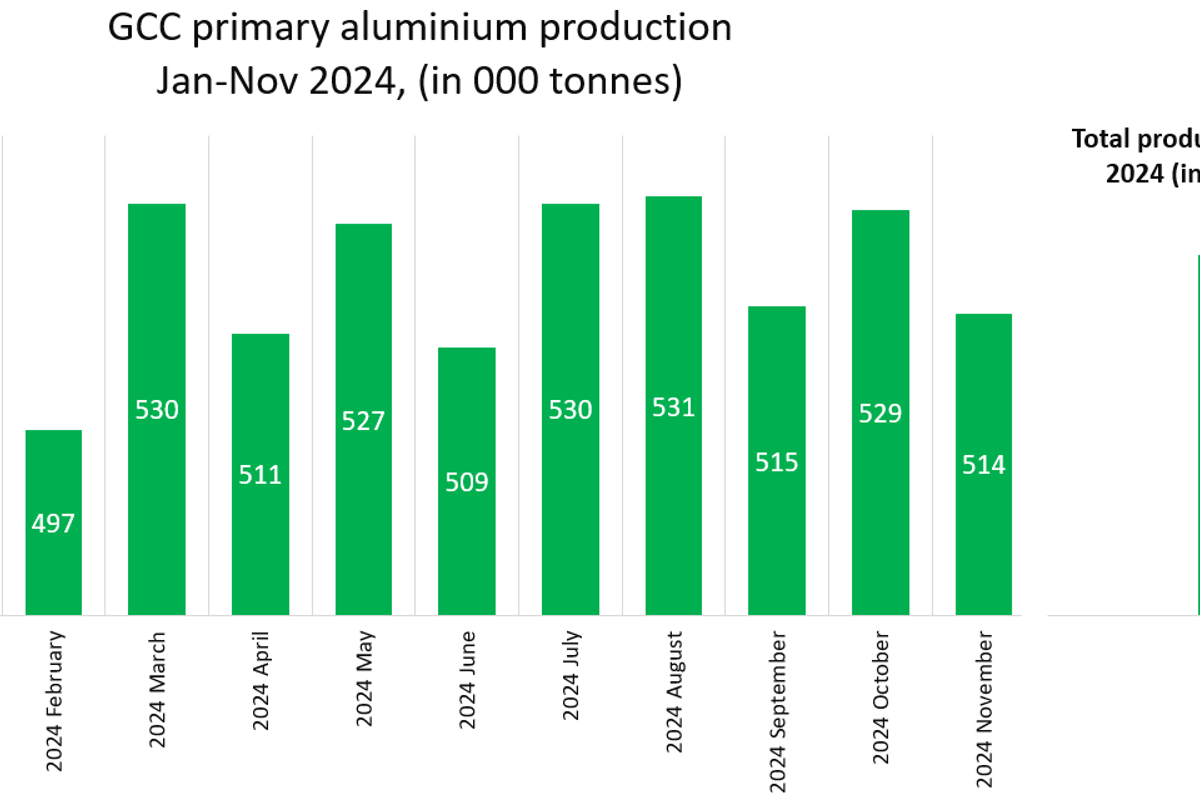
While China continues to dominate global aluminium production, accounting for an estimated 39,653 thousand tonnes in 2024 (January-November), representing nearly 60 per cent of the total output, the Gulf Cooperation Council (GCC), which consorts a massive middle-eastern aluminium trading countries, solidifies its position as the second-largest producer, contributing 5,726 thousand tonnes. Other key contributors include Asia (excluding China) at 4,403 thousand tonnes, North America at 3,646 thousand tonnes, and Russia & Eastern Europe at 3,808 thousand tonnes.
Middle Eastern trade dynamics
Aluminium exports have seen a dramatic increase in Middle Eastern countries between 2017 to September 2024. In Bahrain, exports have risen from approximately 435,000 tonnes in 2017 to a peak of 1,818,000 tonnes in 2022. Conversely, aluminium imports have followed a more volatile trajectory. A substantial decline is observed from 149,000 metric tons in 2017 to a low of 15,000 metric tons in 2021, possibly indicating a successful drive towards self-sufficiency or a change in domestic demand. However, imports rebounded in 2022 and 2023. From January to October 2024, 1.16 million tonnes of aluminium was exported from the country, whereas during the same period, 23.5 thousand tonnes were imported into the country. UAE which accounts for the majority share of the business in the region, Wherin a dynamic picture of the UAE's aluminium trade can be witnessed between 2017 to September 2024. Exports have remained relatively stable, fluctuating around 2.3 million tonnes. However, imports have steadily increased, reaching nearly 292,000 tonnes in 2022, indicating growing domestic demand. The recent decline in both exports and imports in YTD September 2024, accounting for 1.9 million tonnes of exports and over 250 thousand tonnes of imports, can be attributed to various factors, including global economic fluctuations, changing EU and environmental policies, and adjustments in domestic production and consumption patterns.
In a recent interview with Al Circle in their e-magazine titled 'Aluminium Middle East: Focus 2024', Frederic Moreira Pereira, who is the Services Development Manager of Fives' aluminium division, said, "According to CRU, there will be strong growth in Transport, Electrical Equipment and Infrastructure triggered by the energy transition with the electrification of the society. Moreover, the market has experienced a strong push towards low-carbon aluminium, and GCC smelters have started to decarbonise their operations as demand for green aluminium spikes."
Sustainability driving growth
The burgeoning Middle Eastern aluminium market is significantly propelled by a growing focus on sustainability and environmental responsibility. Recycling initiatives are gaining traction, offering substantial benefits such as energy savings, resource conservation, and reduced environmental impact.
On one hand, Emirates Global Aluminium launched the Aluminium Recycling Coalition in January 2023, aiming to significantly enhance recycling rates, particularly for beverage cans. On the other, L'Occitane introduced the 'Gift of Nature' campaign in June 2023, showcasing products made from recycled aluminium, aligning with the region's increasing emphasis on sustainable practices.
GCC's Response to the EU's Carbon Border Adjustment Mechanism (CBAM):
The impending implementation of the EU's CBAM in 2026 is driving GCC nations, major aluminium producers, to accelerate their transition towards sustainable production. With nearly a third of their exports destined for the US and EU, compliance with CBAM is crucial for their continued success.
Emirates Global Aluminium is leading the charge in implementing a digital greenhouse gas emissions tracking system to enhance transparency and accelerate decarbonisation. The company has also collaborated with Masdar to explore joint renewable energy projects, further reducing its carbon footprint.
This growth reflects a strategic initiative by the GCC to diminish its reliance on oil revenue by encouraging investments in non-oil businesses such as infrastructure projects, tourism, and metals and minerals. The non-oil sector is estimated to have grown by 4.3 per cent in 2023, supported by government investments aimed at economic diversification. It is projected that this sector will grow by approximately 3.6 per cent in 2024, while oil sector revenue continues to decline due to capacity cuts and falling prices.
- The Middle East aluminium market is poised for significant growth, driven by a CAGR of 5 per cent from 2024 to 2030.
- Sustainability initiatives, particularly recycling initiatives, are playing a crucial role in driving market growth.
- The GCC, with its focus on sustainable production and technological advancements, is well-positioned to capitalise on the growing global demand for low-carbon aluminium.
- The EU's CBAM is acting as a catalyst for the region to accelerate its transition towards more sustainable and environmentally responsible aluminium production practices.
The global aluminium industry is at the crossroads of innovation, sustainability and growth. As we approach 2025, key trends and market dynamics are shaping the way we produce, consume and trade aluminium. AL Circle's industry-focused report, 'Global Aluminium Industry Outlook 2025', is your guide to understanding these trends, unlocking opportunities and staying ahead of the competition.