Some Japanese aluminium buyers have settled third-quarter premiums at USD 108 per tonne, down sharply from USD 182 per tonne in the second quarter, in a deal that reflects muted domestic demand, rising port inventories, and broader market oversupply, according to sources directly involved in the negotiations.
Image for referential purposes only
The 41 per cent quarter-on-quarter decline is the second consecutive drop and the lowest quarterly premium since early 2024, underscoring Japan’s ongoing demand uncertainty across major end-use segments like transportation, construction, and packaging.
Buyers gain upper hand as spot deals undercut producers’ offers
Negotiations, which concluded last week, saw initial producer offers range between USD122 and USD 145 per tonne. However, Japanese buyers pushed back aggressively, citing low spot deals—some as low as USD 80 per tonne — and elevated inventory levels at domestic ports. This gave buyers the upper hand in price-setting, forcing producers to agree to USD 108 per tonne for July-September shipments.
The premium, which is added on top of the London Metal Exchange (LME) benchmark, is a critical pricing reference not only for Japan but for much of Asia’s aluminium trade.
Domestic weakness reinforced by consumption data
“Despite earlier concerns surrounding the impact of US tariffs, the actual disruption has been marginal so far,” said a source from a Japanese trading house. “The steeper drop in premiums is mainly driven by weak demand and ample supply.”
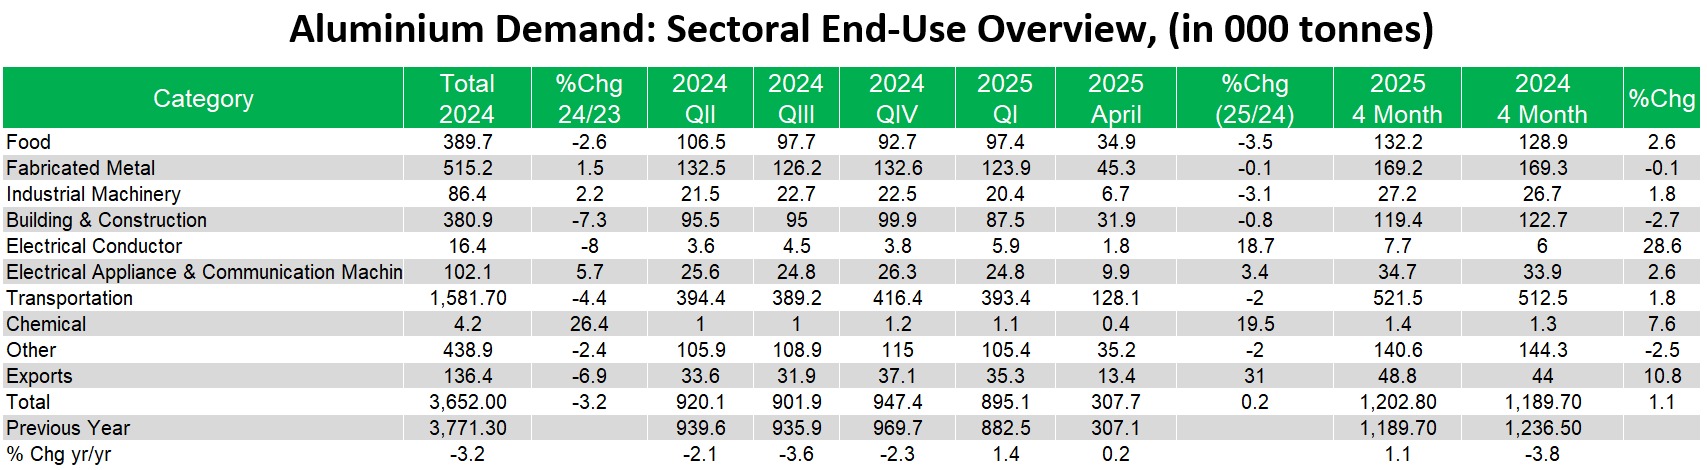
The latest demand data from the Japan Aluminium Association paints a bleak picture. Total aluminium demand in 2024 dropped 3.2 per cent year-on-year to 3.65 million tonnes, with significant contractions in core consumer sectors:
- Transportation, the largest consuming segment, fell 4.4 per cent to 1.58 million tonnes.
- Building & construction declined by 7.3 per cent to 380.9 thousand tonnes.
- Food packaging dipped 2.6 per cent to 389.7 thousand tonnes, suggesting even stable demand bases are softening.
Only a few sectors bucked the trend. Electrical appliances and communication machinery rose 5.7 per cent, while fabricated metal products managed a 1.5 per cent uptick.
Reinforcing the weak demand narrative, aluminium stocks at Japan’s key ports climbed to around 331,000 tonnes by end-May, up 3.3 per cent M-o-M. The buildup suggests low material off-take even as imports continued to flow in. Unless these inventories are drawn down meaningfully in the next quarter, the pressure on premiums may persist well into Q4.
“There was no significant change in local demand, but local spot prices have fallen during negotiations, even to the USD 80 level, forcing producers to abandon their initial offers,” a second source at an end-user said.
Japan's benchmark ripple effects
As Asia’s largest importer and the region’s premium benchmark-setter, Japan’s sharply lower Q3 settlement may influence contract negotiations in South Korea, Taiwan, and Southeast Asia. Producers operating in high-cost environments may now face margin squeezes, while consumers, particularly in price-sensitive sectors like packaging and auto, stand to benefit.
Exporters into Japan may also see increased competition from lower-cost or tariff-diverted material, particularly as Chinese exports remain aggressive and Russian metal continues to find buyers in Asia amid Western sanctions.
2025 starts with tentative recovery, but outlook remains cautious
Early signs from 2025 suggest mild stabilisation. Aluminium consumption in Japan rose 1.1 per cent in the first four months of the year, with electrical conductor demand jumping nearly 29 per cent year-on-year, and exports improving 10.8 per cent. However, gains remain uneven, with industrial machinery and construction sectors still in decline.
Whether Q4 premiums stabilise or fall further may now depend on broader economic recovery, end-market pick-up, and policy clarity around global trade dynamics, including ongoing tariff shifts in the US and China.
The Q3 aluminium premium drop to USD 108 per tonne is not just a pricing event. It’s a mirror to Japan’s sluggish consumption environment. For buyers, it signals temporary cost relief. They can purchase now and utilise later as and when demand recovers. For producers, it’s a red flag on demand sustainability and stock overhang. And for the wider region, Japan’s premium reset could catalyse a broader repricing of risk and opportunity in Asia’s aluminium trade through the second half of 2025.