When the European Union unveiled its Carbon Border Adjustment Mechanism (CBAM), the ambition was clear: to build a fortress against carbon leakage, shield domestic industries from unfair competition, and incentivise global decarbonisation. It was heralded as the world’s most sophisticated climate tariff, with a complex, bold, and precise outline.
Image for referential purposes only
But as the legislation transitions from theory to implementation, a critical vulnerability has emerged. And it’s not in exotic energy systems or abstract accounting tricks. It’s in something far more mundane, yet deceptively potent — aluminium scrap.
As for the current plan, CBAM creates a multi-billion-euro arbitrage opportunity for foreign aluminium producers. And the loophole is alarmingly simple. Both pre-consumer and post-consumer aluminium scrap are excluded from CBAM’s emissions accounting. That oversight could render the EU’s climate fortress porous, not just at the edges, but at the very core of its aluminium trade policy.
Scrap as a strategy, but why?
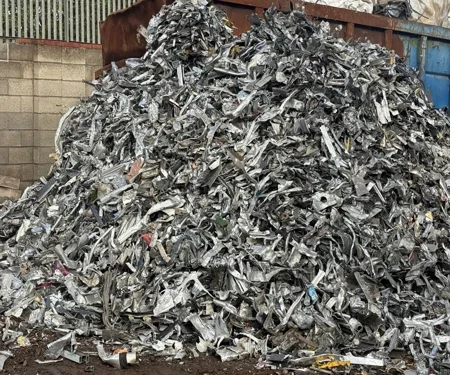
Scrap has always been an integral part of the aluminium value chain. It is an emblem of circularity. Lightweight, durable, and endlessly recyclable, aluminium thrives in a loop. Every offcut in an automotive plant, every can returned to a redemption centre, and every façade removed from a demolition site can find its way back into furnaces around the world. The process, as well established before, saves up to 95 per cent of the energy required to produce virgin aluminium.
That’s the sustainability story. But there’s another side to it, which is a more opportunistic one. Under CBAM’s current accounting framework, aluminium scrap carries no embedded emissions. For importers into the EU, that’s a massive cost-saving lever.
According to a study commissioned by European Aluminium, simply increasing the share of pre-consumer scrap by 20 per cent in extruded profiles could slash CBAM fees by 24 per cent, amounting to EUR 40 per tonne saved, which is a 1.8 per cent discount off the current average LME price of EUR 2,260 per tonne. If both pre- and post-consumer scrap content are bumped to 45 per cent, the CBAM fee drops by EUR 102 per tonne, or roughly 4.5 per cent of base aluminium value.
By 2034, as CBAM scales up to full implementation, this advantage will grow. Importers could save up to EUR 146 per tonne (6.5 per cent of LME price) just by gaming the scrap composition. This is not efficiency. It’s exploitation.
Anatomy of circumvention: Scrap, swaps and shell games
The mechanics of how this loophole operates are well understood. With scrap not counted toward carbon emissions under CBAM, third-country producers can manipulate their declared material flows. Products with high scrap content, real or claimed, are routed to Europe, while high-emission, primary-metal-based products are diverted elsewhere.
This is what’s referred to in the study as ‘resource reshuffling’, a form of emissions laundering that allows exporters to present a lower-carbon façade to the EU while maintaining high-emission operations globally. The problem intensifies when facilities split operations into sub-installations or subproducts, isolating low-carbon lines specifically for European export. Since CBAM doesn’t prevent such internal restructuring, the system becomes a theatre of selective transparency.
China alone, in 2023, generated 7.6 million tonnes of pre-consumer scrap and 6.8 million tonnes of post-consumer scrap. North America added another 7.8 million tonnes. Combined, these volumes surpass Europe’s projected 17.5 million tonnes of aluminium semi-demand by 2030.
The European cost of an uneven playing field
While importers exploit arbitrage, European producers are locked into the ETS system, paying for every tonne of carbon emitted, across every production step. From primary smelting to remelting, from rolling to extrusion, emissions are tracked and priced.
As a result, domestic manufacturers operate with rising costs, thinning margins, and a regulatory framework that does not reflect the competitive pressure from under-declared imports. For producers already grappling with elevated power prices and shrinking free allowances under ETS, this isn’t just an imbalance; it’s a threat to survival.
Worse still, CBAM’s failure to properly account for scrap inflates the European aluminium premium, raising costs across the board. Recyclers pay more for scrap. Downstream users face more expensive semi-fabricated products. Yet, these rising costs do not correspond to genuine decarbonisation incentives, but to structural weaknesses in CBAM design.
National default values — Study’s policy lifeline
So how do we fix it? The study proposes a clear, if politically charged, solution: apply national default carbon values to all aluminium imports, based on the average carbon intensity of each country’s primary production. No more relying on self-reported scrap contents. No more accounting gymnastics.
This approach simplifies compliance, reduces legal grey zones, and prevents circumvention by scrapping the distinction between scrap and primary metal—at least until traceability improves. Scrap, for now, should be treated as if it carries the same emissions as primary aluminium.
Such a move would not only protect Europe’s industrial competitiveness but also realign CBAM with its core purpose: to incentivise global decarbonisation, not just strategic disclosure.
And yes, there are trade-offs. Treating scrap as primary metal risks disincentivising recycling in countries with genuine circularity gains. But this, too, can be solved—with a mass balance approach that incorporates national recycling rates into the default value model, updated periodically to reflect real-world decarbonisation.
The stakes are global, but the clock is European
There is a quiet urgency to this debate. CBAM’s phased implementation is underway, and by 2034, it will be fully operational. That gives exporters nearly a decade to optimise their circumvention playbooks. Europe doesn’t have that luxury.
If the loophole remains, CBAM won’t curb emissions. It will simply redistribute carbon pricing burdens from exporters to domestic producers. It will incentivise data manipulation, not decarbonisation. It will erode confidence in the EU’s climate leadership, at precisely the moment it seeks to set global standards.
As the world’s aluminium flows, adapt to carbon-aware trade, scrap must no longer be treated as invisible. Every tonne carries a history. Every product is an emissions inheritance. And if CBAM is to be more than just another tariff in green wrapping, that inheritance must be counted.












_md.webp)