India’s indirect tax system is on the verge of a major shift with the introduction of GST 2.0 from September 22, 2025. At the centre of this overhaul are two pillars—Integrated GST (IGST) and Cess—that decide how imported goods, inter-state supplies, and luxury products are taxed. IGST has long been used as a balancing tool to treat imports and domestic goods equally, while Cess worked as an extra duty on luxury and demerit products.
Under the upcoming system, these two will be folded into a more straightforward slab arrangement. The intent is to simplify compliance while keeping the overall tax pressure on premium products largely the same.
GST, which replaced a tangle of older indirect levies, comes in three parts. CGST goes to the Centre on sales within a state. SGST is the state’s share on those same local transactions. And IGST is collected by the Centre whenever a deal crosses state borders—or when goods are imported.
How IGST works on imports
The 2017 IGST law treats every import as if it were an inter-state supply. That means IGST is charged in addition to customs duty, and it is assessed under the Customs Tariff Act, 1975 at the time customs duties are imposed under the Customs Act, 1962.
IGST comes on top of Basic Customs Duty (BCD), but it isn’t a separate tax in the sense of adding something extra. It simply mirrors whatever rate applies to the same product inside India. For instance, if aluminium articles are taxed at 18% GST domestically, then the very same 18 per cent IGST is levied when they come in from abroad.
The calculation is as direct as it sounds:
IGST = Sale Price × GST Rate
Take aluminium rods worth INR 1,00,000. At 18 per cent GST, the IGST payable on import is:
IGST = INR 1,00,000 × 18% = INR 18,000
That way, imports and domestic supplies are on equal footing.
When GST first rolled out, the Centre added a new levy: Compensation Cess. It was meant to plug state revenue losses during the transition years. Unlike GST, which touched nearly everything, this cess applied only to a narrow set of goods—mostly high-end cars, large motorbikes, aerated drinks, and coal.
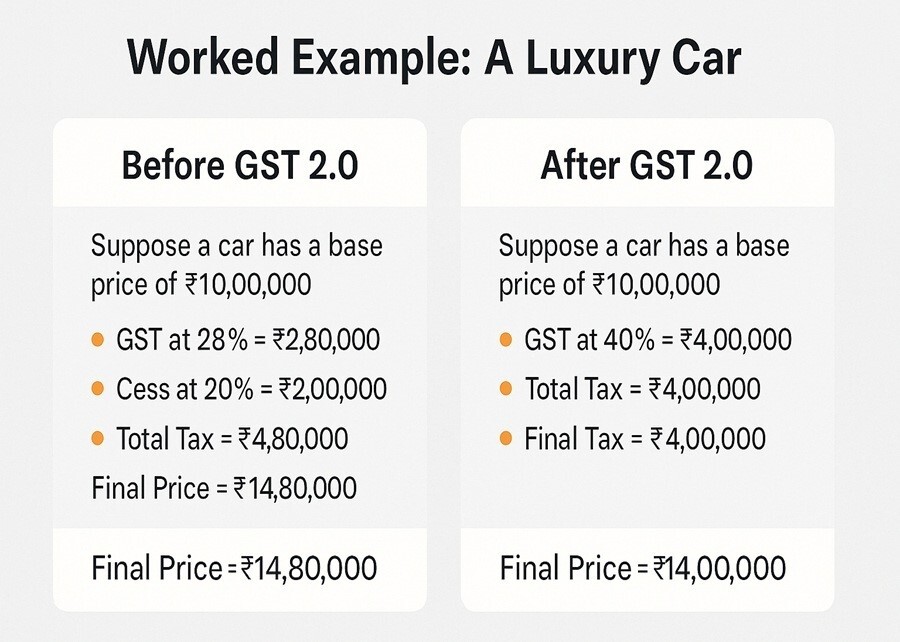
Cess was worked out on the taxable value of goods, which included BCD but not IGST. The proceeds went into a fund, which was then shared with states. The system, however, made compliance messy. A luxury car, for example, already attracted 28 per cent GST, but on top of that came cess anywhere between 15 per cent and 22 per cent, easily pushing the final burden past 40 per cent. Aerated beverages, too, were saddled with high combined rates.
The formula was simple but heavy:
Cess = Taxable Value × Cess Rate
Here, the “taxable value” meant the assessable price before GST, and the cess rate differed across products.
The new regime trims the slab structure. Instead of 5, 12, 18 and 28 per cent, GST will now run on three main slabs: 5, 18 and 40 per cent. The big new entry is the 40 per cent slab, reserved for luxury and demerit goods. This slab folds cess into the main tax, meaning businesses no longer need to calculate two separate components.
So, a luxury car or SUV, earlier taxed at 28 per cent GST plus, say, 20 per cent cess, will now fall directly into the 40 per cent bracket. Motorcycles above 350cc and aerated/energy drinks also land here. The actual incidence of tax stays steep, but the structure becomes far easier to follow.
Impact on businesses (B2B)
For companies, the biggest win is simpler compliance. Invoices, ITC claims and returns are easier now that cess is not a separate entry. Refunds are expected to move faster, and disputes over classifications should drop.
Still, firms face challenges. Input tax credit on big-ticket assets like luxury cars can only be used if the vehicles are part of business operations. This means high amounts of tax may be stuck in credit, creating cash flow pressures. Even so, the clarity of a single 40 per cent rate makes it easier to plan pricing and negotiate contracts. Exporters, in particular, should benefit from smoother refund procedures on premium inputs.
Impact on consumers (B2C)
For buyers, GST 2.0 doesn’t mean cheaper luxury goods—but it does mean clearer bills. Instead of seeing 28 per cent GST plus 15–22 per cent cess, customers now see a flat 40 per cent. The burden is still heavy, but transparency has improved.
Items such as premium cars, powerful motorcycles, yachts and sugary drinks remain costly, reflecting the government’s policy of keeping luxury consumption highly taxed. The higher slab is expected to temper demand from price-sensitive buyers, with some turning toward substitutes or lower-priced models. The sharper divide between essential, standard and premium slabs will also shape how brands position their products in the market.
GST 2.0 is less about cutting rates and more about cleaning up the structure. IGST continues to ensure imports are treated on par with domestic goods, while cess no longer exists as a separate line item. Instead, luxury and demerit products sit squarely under a single 40 per cent slab.
For industries, aluminium and other essential goods remain in the 5 per cent and 18 per cent slabs, keeping their tax load stable. For businesses, compliance becomes easier; for consumers, the tax is clearer even if prices remain high. And for policymakers, the reform achieves its twin goals: simplification of GST and sustained high taxation of luxury consumption.













_md.webp)








