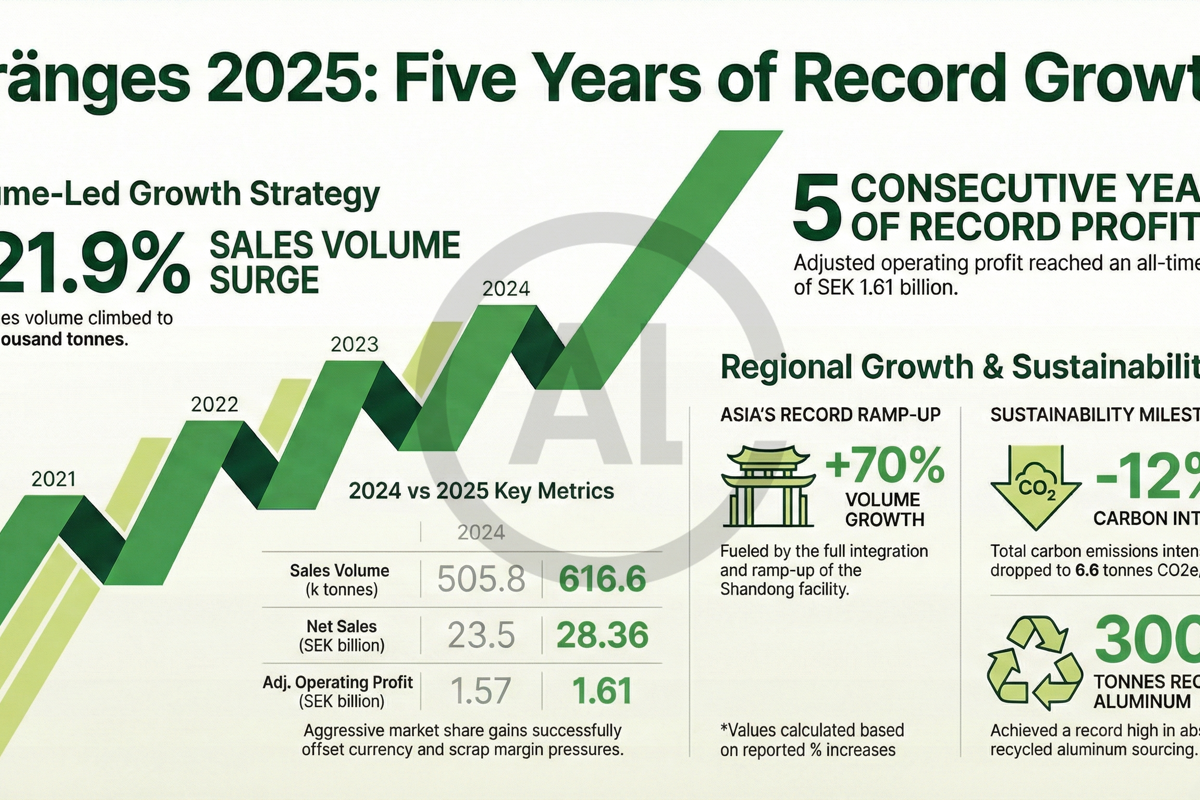
Gränges closed 2025 with its strongest operating performance on record, extending its streak of all-time-high operating profit to a fifth consecutive year, even as currency headwinds, weaker HVAC demand and tighter scrap margins weighed on profitability across regions. The year was defined by aggressive market share gains, capacity ramp-ups in Asia, and volume-led growth rather than margin expansion.
For the full year ended December 2025, overall aluminium sales volume rose 21.9 per cent year-on-year to 616.6 thousand tonnes from 505.8 thousand tonnes in 2024. Net sales increased 20.7 per cent to SEK 28.36 billion (USD 2.73 billion), despite a cumulative negative foreign exchange impact of SEK 1.69 billion (USD 163 million). Adjusted operating profit edged up 2.7 per cent year-on-year to SEK 1.61 billion, while reported operating profit increased 6.0 per cent to the same level. Profit for the period grew 4.7 per cent to SEK 1.06 billion (USD 102 million), translating into diluted earnings per share of SEK 9.54 versus SEK 9.51 a year earlier.
The earnings profile reflects a sharp divergence between volume growth and unit profitability. Adjusted operating profit per tonne declined to SEK 2.6 thousand (USD 250) from SEK 3.1 thousand (USD 298) in 2024, which shows the combined pressure created from lower scrap margins, adverse currency movements and a weaker product mix in certain Asian segments.
For the global aluminium value-chain 2026 outlook, book our exclusive report “Global ALuminium Industry Outlook 2026"
Fourth quarter: Volume surge, margin dilution
In Q4 2025, Gränges reported a 17.0 per cent year-on-year increase in sales volume to 152.4 thousand tonnes, while net sales rose 16.8 per cent to SEK 7.22 billion (USD 694 million). Adjusted operating profit climbed 14.8 per cent to SEK 373 million, and operating profit jumped 34.9 per cent from the prior year quarter, helped by higher volumes and a rescheduled maintenance shutdown that contributed an estimated SEK 20 million to earnings.
Adjusted operating profit per tonne in Q4 stood flat at SEK 2.4 thousand year-on-year. At constant currency, it would have been closer to SEK 2.9 thousand, highlighting the scale of translation losses, which alone reduced quarterly operating profit by approximately SEK 74 million (USD 7.1 million).
Operating cash flow turned positive at SEK 58 million in Q4, compared with a negative SEK 1.05 billion in Q4 2024. However, working capital absorbed roughly SEK 300 million during the quarter, of which around SEK 200 million was directly attributable to higher aluminium prices held on the balance sheet.
Americas: HVAC weakness masked by pricing and share gains
Gränges Americas delivered a mixed but ultimately earnings-positive year. In Q4, total sales volume increased 7.2 per cent year-on-year to 58.4 thousand tonnes, even as HVAC shipments fell 28 per cent due to weak end-market demand and destocking. Automotive volumes rose 19 per cent, speciality packaging volumes increased 28 per cent, and other niche segments expanded 32 per cent.
Adjusted operating profit for the quarter surged 44.3 per cent year-on-year to SEK 278 million (USD 26.7 million), supported by higher fabrication prices, productivity gains and the rescheduling of maintenance downtime. For the full year, operating profit in the Americas reached SEK 1.18 billion (USD 113 million), up 10.0 per cent from 2024, while return on capital employed improved to 20.6 per cent from 19.1 per cent, despite a negative currency translation effect of SEK 43 million in Q4 alone.
Don't miss out- Buyers are looking for your products on our B2B platform
Asia: Volume expansion dominates the earnings story
Asia was the primary growth engine in 2025. Full-year sales volume jumped 70.0 per cent to 205.3 thousand tonnes from 120.8 thousand tonnes in 2024, driven by the full integration and ramp-up of the Shandong facility. Q4 volume rose 32.7 per cent year-on-year to 51.3 thousand tonnes.
Net sales for the year climbed 46.2 per cent to SEK 7.46 billion. Adjusted operating profit increased 22.8 per cent year-on-year to SEK 341 million (USD 32.8 million), although adjusted operating profit per tonne fell to SEK 1.7 thousand from SEK 2.3 thousand, reflecting pricing pressure in lower-value product segments and adverse FX movements. Return on capital employed declined slightly to 9.3 per cent from 10.2 per cent in 2024, signalling that profitability lagged the pace of capacity absorption.
Europe: volume growth without profit follow-through
Europe remained the weakest link in the group’s 2025 performance. Q4 sales volume increased 16.7 per cent year-on-year to 48.0 thousand tonnes, but adjusted operating profit fell 26.4 per cent to SEK 89 million. The year-on-year comparison was distorted by energy cost compensation booked in Q4 2024, while lower scrap margins, wage inflation and currency losses eroded margins in 2025.
For the full year, European adjusted operating profit declined 22.1 per cent to SEK 275 million (USD 26.4 million), despite a 9.3 per cent increase in sales volume. Adjusted operating profit per tonne fell sharply to SEK 1.4 thousand from SEK 2.0 thousand in 2024, and return on capital employed dropped to 4.5 per cent from 6.3 per cent, marking Europe as the most margin-compressed region in the portfolio.
Sustainability metrics improve despite higher production
Gränges reported its strongest sustainability performance to date in 2025. Total carbon emissions intensity (scope 1+2+3) declined 12 per cent year-on-year to 6.6 tonnes CO₂ equivalent per tonne, while sourced recycled aluminium volumes increased 20 per cent to a record 300 thousand tonnes. Recycled content accounted for 45.1 per cent of total sourced aluminium, marginally lower than 2024, due to mix effects following the inclusion of Shandong, but absolute recycled tonnage rose sharply.
Balance sheet and outlook
Financial net debt fell to SEK 4.07 billion at year-end, and leverage improved to 1.6x adjusted EBITDA from 1.8x a year earlier. Capital expenditure declined to SEK 773 million (USD 74.3 million) from SEK 1.33 billion (USD 128 million in 2024, reflecting the completion of major expansion projects.
For the ongoing calendar year, the business’ core management anticipates low-to-mid single-digit volume growth, with continued pressure from currency movements and higher aluminium prices likely to weigh on operating cash flow. The strategic focus has shifted decisively from expansion to utilisation, pricing discipline and productivity optimisation across the group.
Must read: Key industry individuals share their thoughts on the trending topics













_md.webp)








