Europe’s renewable boom has a two-faced economy. On long, bright, windless days, it floods grids with cheap or even negative-priced power; when the weather turns, capture prices, as in the money actually earned by wind and solar assets after weighting by when they produce, recover sharply. That swing is not academic for aluminium. The metal’s primary production is among the industry’s hungriest electricity consumers, and swings in capture and wholesale power prices cut straight to smelters’ margins, investment plans and decarbonisation pathways.
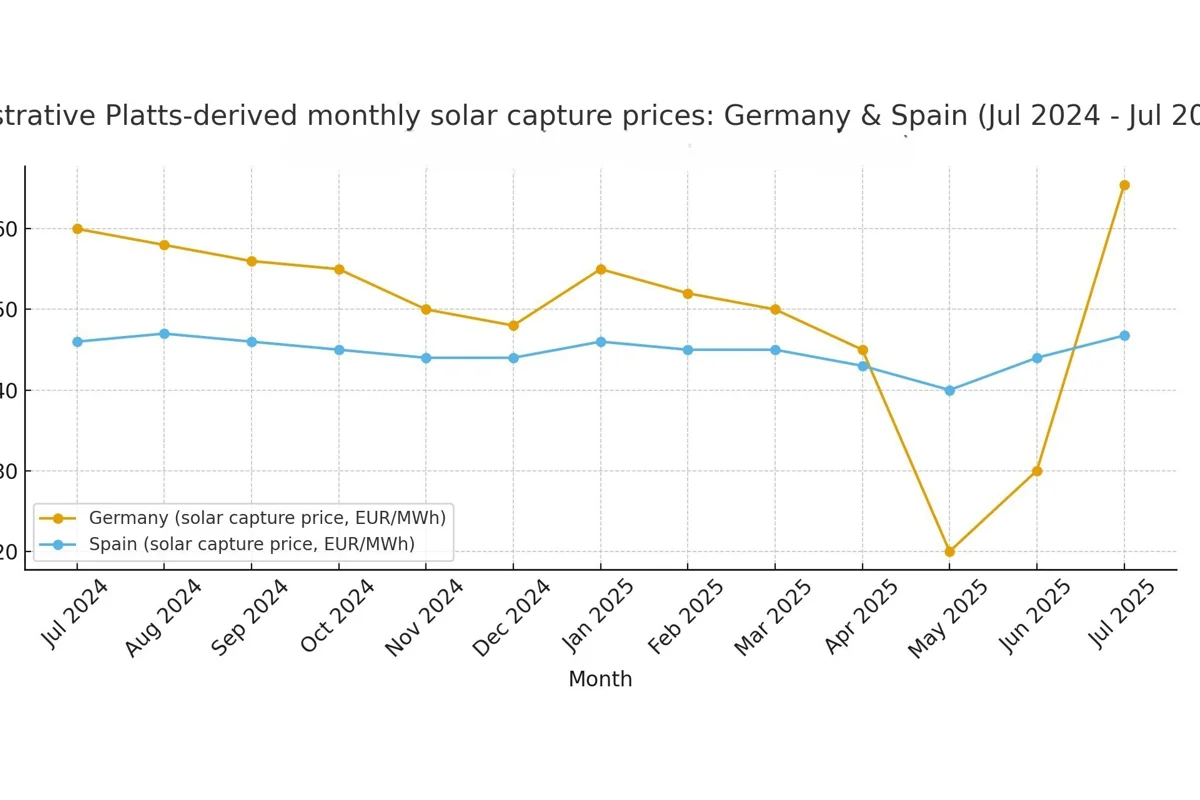
S&P Global’s Platts Renewable Energy Price Explorer shows exactly this dynamic playing out through mid-2025. Solar and wind output across Europe’s five largest markets rose about 10 per cent year-on-year in July, but output eased from June’s record highs and capture prices rebounded. In Germany, solar’s capture rate surged to 75 per cent in July, the highest since February, up sharply from a Q2 average of just 51 per cent. Consequently, German solar capture prices jumped to about EUR 65 per MWh, recovering from five-year lows in May–June.
Spain told a different story! Prices started in July in bullish fashion, but windier, cooler weather in the latter half of the month eased pressure. The country’s solar volume-weighted average settled at EUR 46.76 per MWh, a touch below July 2024 but still well clear of the spring slump.
Platts also reports that a growing feature of high-solar months, which is the number of negative hourly prices, fell sharply in July compared with the second quarter.
From capture prices to smelter balance sheets
Why should aluminium executives care about capture prices? Because producing a tonne of primary aluminium consumes a lot of electricity, recent industry studies and white papers put the ballpark between roughly 14,800-19,000 kWh per tonne of primary metal, depending on technology and cell efficiency. That makes electricity one of the single largest cost items in smelting, in many market settings accounting for a third or more of cash costs, and it also determines the carbon intensity of the metal. In short, variability in power value and availability changes both profit and the credibility of low-carbon claims.
A practical consequence is visible in corporate deals. Long-dated, low-carbon power contracts and captive generation remain the industry’s preferred hedge. Norway’s Hydro, for example, is locking in long-term power and supply agreements and winning billion-euro contracts to supply low-carbon aluminium to European grid projects.
Negative prices are a price of transition. Until they aren’t!
Europe’s surge in solar capacity made negative hourly prices a near-routine event in spring and early summer 2025; Platts counted thousands of negative hours across EU markets in Q2. Negative pricing matters because it both reduces the average revenues received by renewable generators (the “capture price”) and complicates merchant-market hedging for industrial consumers.
Yet the July bounce in capture prices demonstrates the other side of the coin: demand seasonality and weather variability can quickly restore value to renewable output, reducing the frequency of negative settlements. For aluminium producers that buy on the merchant market, this means a high degree of short-term revenue volatility even as long-term PPA markets mature.
For smelters, the policy and market answers are to secure long-dated PPAs, build captive renewables, or vertically integrate into generators. The reality proves to be more complex. In Europe, many smelters already rely heavily on purchased grid power rather than self-generated supply, and securing competitively priced long-term contracts is becoming harder as other large buyers — particularly data centres and AI cloud farms — compete for the same low-cost, long-tenor renewable capacity. Financial press reporting and industry commentary in 2025 note that smelters in the US and Europe are increasingly being out-bid for cheap, long-term power by hyperscalers and tech projects, which undermines industrial relocation efforts and raises the cost of on-shoring capacity.
The undercurrent for decarbonisation commitments
There’s a paradox at the heart of aluminium’s net-zero story. Companies can reduce carbon footprints by sourcing green electrons, but the economics of doing so are intimately tied to how much those electrons are worth when produced. Volume-weighted capture price metrics — to which Platts added daily and monthly products in mid-2025 — help make that value visible to both buyers and sellers.
Mechanisms that reward flexibility, from capacity markets, storage revenues, to industrial demand-response payments, will change the calculus for energy-intensive industries. For aluminium, the prize is twofold: cheaper, lower-carbon power when markets are designed to reward clean baseload and flexibility; and a clearer route to selling ‘green aluminium’ backed by traceable, time-matched renewable supply.
Europe’s aluminium sector is now running on more green electrons than anywhere else in the world. In 2023, 78 per cent of the electricity fuelling primary smelting in Europe came from renewables, up from 67 per cent less than a decade ago, according to European Aluminium’s latest Environmental Profile. That shift has dragged the region’s carbon footprint down to 6.3 kg of CO₂ per kg of metal, almost 60 per cent below the global average. For an industry where power costs can make or break balance sheets, this isn’t just an environmental upgrade — it’s becoming a commercial weapon in markets increasingly dictated by green premiums and carbon border rules.
The global comparison is stark. The World Economic Forum’s Net-Zero Industry Tracker 2024 puts renewable-powered smelting worldwide at just 39 per cent, with the rest still tied to fossil-heavy grids. Recycling covers about 36 per cent of output, but the bulk of the world’s primary aluminium remains coal-powered. Europe’s divergence is therefore not cosmetic; it is carving out a cost–carbon double advantage. Deals like Hydro’s billion-euro contract to supply low-carbon aluminium to NKT for EU grid projects show how renewable-backed smelters are already monetising that gap — leaving regions that lag on renewables, particularly coal-reliant producers, exposed to policy risk and shrinking market share.
Pragmatic strategies for producers and stakeholders
Producers should stop treating power as a passive input and start managing it as a strategic asset. Practically, that means pursuing a mix of actions now:
- Locking in long-term, time-matched PPAs where possible, while structuring them to share capture-price upside and downside with counterparties;
- Investing in captive renewable generation and co-located storage to reduce exposure to merchant price swings;
- Developing flexible smelting practices and engaging in demand-response markets where regulatory frameworks allow; and
- Using volume-weighted capture pricing datasets to quantify and validate low-carbon product premiums in commercial contracts and public ESG claims.
Stakeholders (private or public), meanwhile, must recognise that industrial decarbonisation depends on more than renewables build-out. Stable, affordable access to firm low-carbon energy, either through dispatchable low-emissions generation, storage, or targeted industrial power support, is the missing piece if Europe and other regions expect heavy industry to be both green and globally competitive.













_md.webp)








