What began as a quiet movement of scrap out of Europe has gradually turned into a significant concern for the region’s aluminium recyclers. The volumes leaving the bloc have increased year after year, and the trend is now firmly visible in the export numbers. In 2020, the EU exported USD 1 billion worth of aluminium scrap — about 937.8 thousand tonnes, but year later, that figure nearly doubled to USD 1.9 billion, which accounts for 1.115 million tonnes. Things eased slightly in 2022 to USD 1.88 billion and 992.5 thousand tonnes, but this downturn barely lasted a season. By 2023, exports were back up — 1.16 million tonnes scrap worth USD 2 billion were again exported and in 2024 it pushed even higher to USD 2.34 billion which accounts for 1.25 million tonnes. And before Brussels could finalise any new rules, eight months into 2025 the tally had already reached USD 1.66 billion, equal to 826.14 thousand tonnes of scrap.
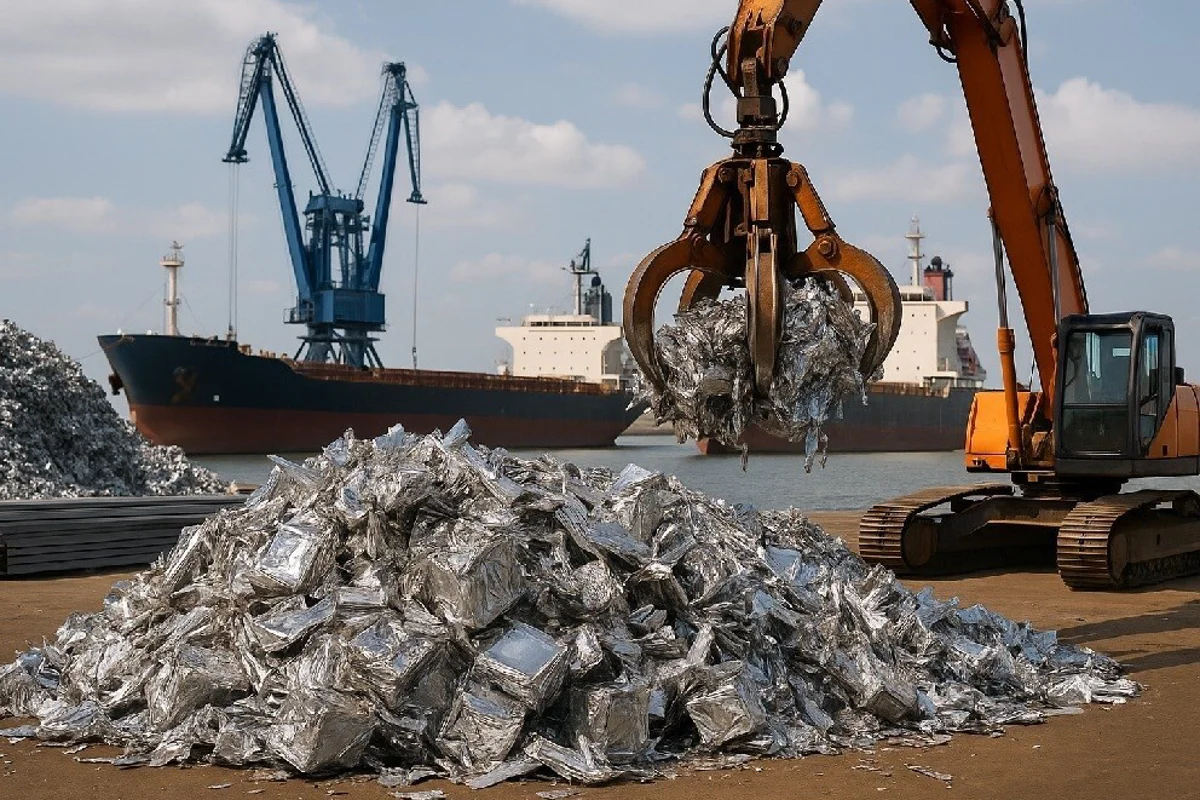
Image for representational purpose
The reason for surge didn’t originate in Europe. It can be traced to the US Section 232 tariffs, which scrambled global aluminium trade flows and opened up arbitrage windows. Scrap came into demand because the tariff was not put to aluminium scrap and these made its demand high. These nudged European scrap eastward or across the Atlantic instead of into local furnaces.
When Donald Trump ramped up aluminium duties from 25 per cent to 50 per cent, the incentive sharpened even more. Scrap became a convenient fallback for US manufacturers trying to dodge costlier primary aluminium. Meanwhile, Europe’s own recyclers were left running plants below potential. Industry bodies has also warned that the erosion in supply threatens nearly EUR 40 billion in annual turnover and puts 25,000 direct jobs — and close to a million more supported across manufacturing — at risk.
What EU is doing to counter this
Eventually, the growing tension forced its way onto Brussels’ agenda. At the European Aluminium summit, commissioner Maroš Šefčovič confirmed that officials are assembling what he called a “balanced measure,” likely to be in place by spring 2026. Calls for action had been coming since early 2024, especially after Trump’s duty hikes sparked fears that US buyers would shift more aggressively into scrap.
The market didn’t wait for the policy to come live. It reacted immediately. Export movements through early 2025 make that very clear. From January to February, volumes jumped 17.82 per cent, then edged up by just 0.67 per cent into March before skidding downward: 6.71 per cent in April, 15.75 per cent in May, and 1.32 per cent in June. July brought a sudden rebound of 12.06 per cent — followed immediately by August’s steep 16.17 per cent drop.
This fluctuation happened because, the of a news that, EU is considering export tariffs of 25 – 30 per cent. Such a tariff would add somewhere between EUR 50 and EUR 150 per tonne for buyers abroad, and Brussels expects the knock-on effect at home to push domestic prices up by another EUR 20–40 per tonne according to Discovery alert.
Where the majority scrap is going?
While Europe kept debating, Asia simply kept buying. In 2024, the EU exported 1.26 million tonnes of scrap to the region — roughly a 50 per cent jump compared with 2019. India, China, Pakistan and Thailand quietly become the biggest magnets, thanks to fast-growing secondary aluminium industries and a clear price advantage. Also, US tariffs tightening American supply only amplified that pull.
As the data from UN Comtrade, in 2023, India imported USD 560 million worth of scrap (318.9 thousand tonnes). Thailand followed with USD 206 million and 113 thousand tonnes. China brought in USD 140 million, equal to 71 thousand tonnes, while Pakistan received USD 105 million and 90 thousand tonnes. All four expanded their intake in 2024. India rose to USD 632 million, which accounts for 345 thousand tonnes; Thailand reached USD 303 million and 157 thousand tonnes; China climbed to USD 148 million and 71.78 thousand tonnes; and Pakistan increased to USD 131 million and 102 thousand tonnes.
The pace of growth told its own story: India gained 12.9 per cent in value and 8.1 per cent in volume, Thailand surged by 47 and 39 per cent, China added 5.7 and 1.1 per cent, while Pakistan rose 24.8 and 13.3 per cent.
Things didn’t slow much in 2025 either. By August, India had already taken USD 512 million, equal to 255 thousand tonnes. Thailand stood at USD 183 million and 91.4 thousand tonnes. China reached USD 155 million and 77 thousand tonnes. Pakistan imported USD 90 million, or 67.7 thousand tonnes. With Asian mills hungry for low-carbon feedstock — and the US tariff wall cutting into their usual supply routes — EU scrap became a prime target.
CBAM adds a complication Europe didn’t need
Europe’s policy dilemma deepens with the full arrival of the Carbon Border Adjustment Mechanism in 2026. The system places a carbon cost on imported aluminium — but assigns a zero-emissions value to aluminium scrap. For foreign recyclers, that means they can ship scrap into the EU without paying the carbon burden that European producers face. Recyclers inside the bloc argue it distorts competition and undermines the environmental logic CBAM is supposed to reinforce.
The contradiction sits at the centre of the problem: CBAM pushes European manufacturers to rely even more on scrap as primary aluminium imports become costlier, yet the EU is losing scrap at a faster pace than ever. With imports tightening and the domestic pool thinning, recycling plants warn of a looming shortage of feedstock precisely when climate rules are about to get stricter. All of this leaves Europe in a race against its own deadlines.
Read our e-magazine for industry leaders' perspectives: ALuminium Industry - Focus Europe