Brussels has stopped watching from the sidelines. As the global metals trade grows more asymmetric and carbon commitments face real-world constraints, the European Commission’s decision to implement surveillance on scrap metal imports and exports has moved far beyond being a regulatory formality to a high-stakes chess move in an escalating global scrap tussle.
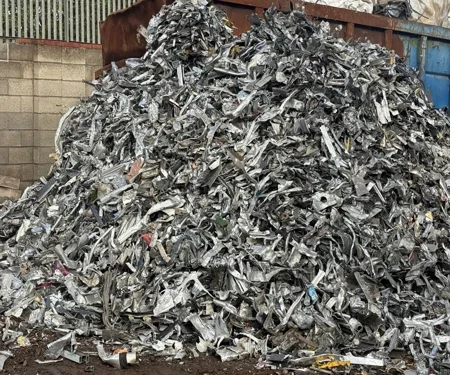
Image for referential purposes only
On July 23, 2025, the European Commission launched an official customs surveillance mechanism to monitor all EU-bound and outbound flows of steel, aluminium, and copper scrap. Though presented as a data-gathering initiative under the Steel and Metals Action Plan (SMAP), this policy shift is anything but passive. It is a direct response to growing export leakages, tightening scrap availability within the bloc, and a deepening risk of industrial hollowing out, especially for energy-intensive, recycling-based producers of aluminium and steel.
At the heart of the issue is the paradox of Europe’s climate strategy, where the EU aspires to lead the world in green metals production, but the raw materials required to deliver that (primarily post-consumer and industrial scrap) are increasingly leaving the continent for higher-paying markets.
A perfect storm of policy failures and market forces
To understand the urgency behind the Commission’s move, one must consider the cumulative pressures on EU metals manufacturers. On the one hand, energy-intensive primary production in Europe has become economically nonviable in the wake of elevated gas and electricity prices, resulting in multiple aluminium smelter shutdowns since 2022. On the other hand, the most cost-efficient option of secondary production is now under threat from raw material scarcity.
This scarcity is not theoretical. According to European Aluminium, EU aluminium scrap exports surged past 1.2 million tonnes in 2024, with Turkey, India, and increasingly the United States absorbing European post-consumer material at a time when domestic demand for green input is climbing. In the case of ferrous scrap, Eurofer has repeatedly warned that excess exports are undercutting the bloc’s ability to decarbonise steelmaking using electric arc furnaces, which rely overwhelmingly on scrap.
Compounding this is the geopolitical wildcard: US Section 232 tariffs, originally introduced under the Trump administration, have been re-weaponised. In early 2025, the United States raised its tariffs on primary aluminium and steel imports to 50 per cent, while leaving scrap untaxed — effectively creating a two-tiered system that encourages scrap imports while punishing producers elsewhere. The EU’s scrap metal outflows to the US spiked dramatically in Q1 2025, with aluminium scrap volumes nearly tripling year-on-year, according to Eurostat customs data cited by Reuters.
In this environment, the Commission’s surveillance move is less about trade transparency and more about buying time. Officials are openly considering the imposition of export authorisation systems or duties if the monthly data confirms sustained export surges. The Commission has promised a policy decision by the end of Q3 (meaning as early as September 2025), with earlier action possible if EU-US trade talks on metal tariff reciprocity collapse.
Circular economy goals collide with global scrap economics
It’s worth reiterating why this matters: the EU’s 2040 climate strategy is anchored in electrified industrial systems powered by low-carbon materials. Recycling scrap consumes up to 95% less energy than primary aluminium production and roughly 80 per cent less than basic oxygen furnace steelmaking. If Europe cannot secure enough domestic scrap, it will be forced to increase imports of primary metals — often produced with higher carbon intensity in jurisdictions with weaker climate rules.
Moreover, letting scrap leak overseas while subsidising downstream decarbonisation technologies within Europe is a policy contradiction.
As noted in the EU’s SMAP strategy paper, the transition to sustainable steel and aluminium “depends on the secure and affordable availability of recycled materials” — yet those materials are precisely what is leaving Europe in bulk. Without correction, the bloc risks sabotaging its own industrial transformation.
This is more than about trade
According to the World Bank’s data, the European Union (EU) imported 606.6 thousand tonnes of aluminium scrap from the world in 2023, which was valued at USD 1.1 million. During the same year, EU exported around 1,161,780 tonnes (valued at USD 2.05 million)
Framing the surveillance system as merely a precursor to potential export restrictions understates its geopolitical and industrial significance. This is Europe acknowledging that it cannot green its metals sector while operating under outdated assumptions of open-market globalism. Unlike traditional safeguard mechanisms, surveillance gives the EU real-time visibility into scrap flows.
One key pillar of this plan is promoting metal circularity, which not only supports the decarbonisation of metal industries but also aligns with the Commission’s proposal to achieve a 90 per cent reduction of net greenhouse gas emissions by 2040, compared to 1990.
The Commission is already consulting stakeholders on whether to introduce more granular product codes to track different scrap types, a move that will benefit sectors like rolled aluminium and foundry castings, which rely on specific alloy recoveries.
Data now, trade measures next?
The speed with which the Commission has moved, less than four months from SMAP adoption to the activation of surveillance, suggests Brussels is bracing for worse to come. If August’s trade data shows continued outflows, expect a swift pivot to defensive action. A plausible scenario would be the reactivation of a 2023 proposal to impose 25 per cent export tariffs on certain grades of steel and aluminium scrap, or an authorisation regime that prioritises intra-EU flows.












_md.webp)