China has been adorned with the title of ‘undisputed heavyweight’ in aluminium production for the past few years. It churns out over 50 per cent of the world’s aluminium and more than half of its alumina. But its towering lead rests on a weak foundation, i.e. imported bauxite. Despite sitting on a billion tonnes of the red rock, China has never truly cracked how to use it owing to its low grade. But it is time that could be about to change. All thanks to an unlikely saviour, a low-profile French tech firm, IB2, says it can turn China’s low-grade ore into high-value alumina, without the environmental or economic pain.
For decades, China’s aluminium industry has thrived by importing better-quality bauxite from overseas. Guinea, Australia, and Indonesia have been the backbone of this strategy. As China’s smelters grew hungrier, imports surged from just 2.8 per cent of supply in 2002 to over 55 per cent by 2023.
Guinea alone now supplies around 70 per cent of China’s imported ore. But that dependence has started to look dangerously brittle. Political upheaval in Guinea, shifting export policies in Indonesia, and frayed trade ties with Australia have all made Beijing nervous. Aluminium is too strategic, and too vulnerable, to leave in foreign hands.
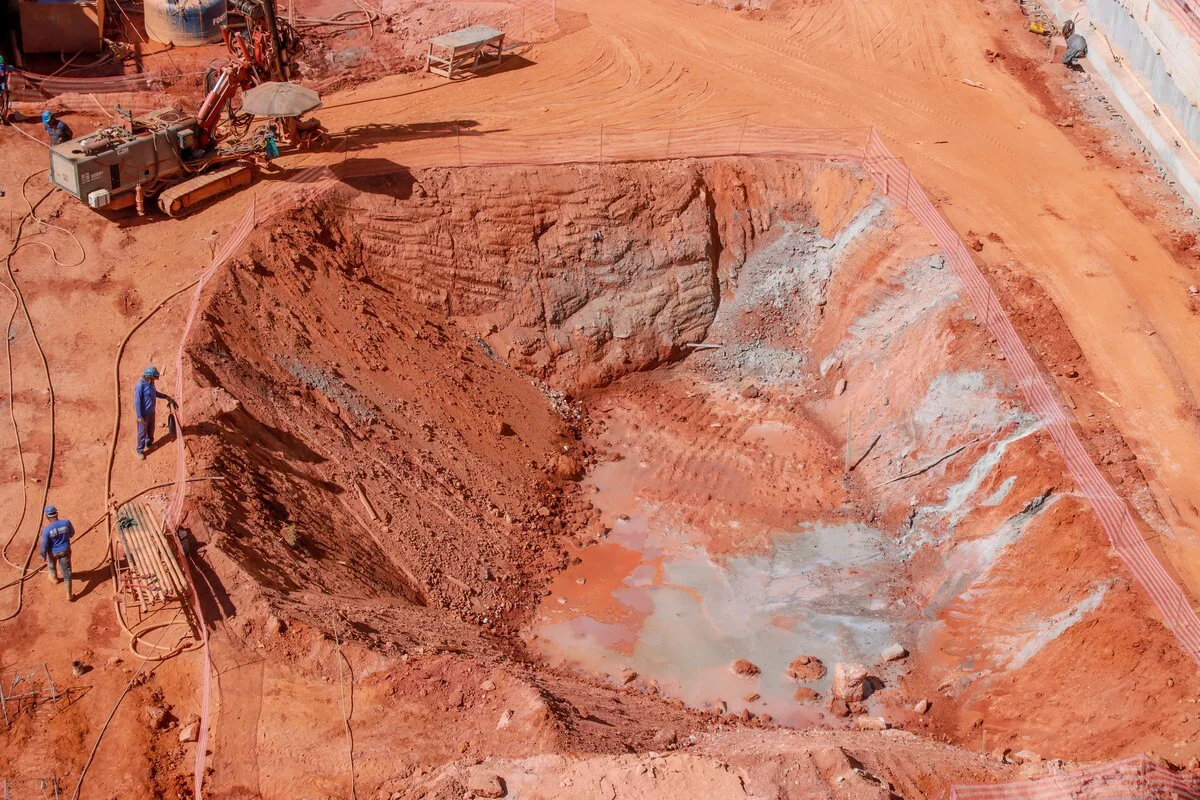
The irony? China has bauxite. A lot of it. Domestic reserves are estimated at between 1 billion and 1.3 billion tonnes. Most of it is located in Shanxi, Henan, and Guangxi provinces. But there’s a catch. More than 99 per cent of China’s bauxite is diasporic—a dense, high-silica variety that’s incredibly tough to refine using the Bayer process, the global standard. Unlike the softer, gibbsite-rich ores from Guinea and Australia, diasporic bauxite requires higher temperatures, harsher chemistry, and much more energy. In short, it’s expensive, dirty, and inefficient.
So, for years, China largely ignored it. Refineries were built on the coast, near ports and not inland near mines. Ore came in by the shipload from half a world away. It was a practical choice, but not a resilient one.
Enter IB2, a French firm that’s quietly been working on this problem for over a decade. Led by chemist Yves Ocello, IB2 has developed a pre-treatment technology explicitly designed for diasporic bauxite. It’s not a revolutionary overhaul of the Bayer process, but rather a clever bolt-on that makes the standard method viable for high-silica ore. It neutralises impurities, particularly silica and sulphur, before digestion. That means refineries can use China’s own bauxite without overhauling their infrastructure and without paying the enormous energy penalty that diasporic ore usually demands.
This July, a refinery in Liulin, Shanxi, will become the first in the world to run a full-scale IB2 unit. Under a 22-year licence agreement with IB2, Liulin Senze Coal & Aluminum will put the French process to the test. Early results have been promising: comparable alumina recovery rates, lower energy consumption, and dramatically improved economics for China’s ‘unusable’ bauxite.
If the Shanxi plant proves the model, this could be the start of something big. China could halve its bauxite import needs in the coming decade. That would be a seismic shift — not just for China’s supply chain, but for the global aluminium market. Countries like Guinea, which rely heavily on Chinese offtake agreements, could face shrinking demand.
“It is a direct enabler of China’s strategy to own its inputs, control its compliance, and operate at scale without external veto points,” says Romain Girbal, chief executive and co-founder of IB2.
Australia, still mending its trading relationship with China, might see its exports wane. And Indonesia’s strategy of forcing foreign firms to invest in downstream refining could backfire if China suddenly doesn’t need its ore at all.
For Beijing, the timing couldn’t be better. In late 2024, it unveiled a new two-year blueprint to make the aluminium industry greener and more self-reliant. IB2’s technology ticks both boxes. It reduces emissions by enabling low-grade ore to be processed at lower temperatures and pressures, meaning less coal-fired power is needed. It also brings China’s raw material base closer to home, shielding the industry from global price shocks and diplomatic curveballs.
There’s also a domestic development angle. Processing bauxite where it’s mined, rather than hauling it thousands of kilometres to coastal refineries, means new jobs, new infrastructure, and a shot in the arm for China’s struggling inland regions. It aligns neatly with Beijing’s “rural revitalisation” narrative, especially in provinces like Shanxi, which have long lagged behind the booming coast.
Still, questions remain. Can the IB2 process scale? Will local governments and state-owned enterprises buy in fast enough? And will the environmental gains hold up if power for these inland refineries still comes from coal? After all, China’s aluminium industry is already under fire globally for its carbon intensity. If domestic bauxite refining simply shifts emissions inland, without changing the energy mix, critics will call it greenwashing.
But for now, the momentum is real. For the first time in decades, China’s domestic bauxite has been taken seriously, not as a geological burden but as a strategic asset. All it took was a little French chemistry, a lot of patient engineering, and a geopolitical climate that made self-reliance a necessity, not a luxury.
Girbal said his company’s technology would help Chinese producers “increase yield, reduce reagent use and comply with domestic environmental, social and governance (ESG) policy”, referring to Beijing’s directive.
Aluminium was always the crown jewel of China’s industrial might. Now, it may also become the test case for a new era of domestic-first resource strategy.
Information credit: South China Morning Pos












_md.webp)
_md.webp)
_md.webp)