Emirate Global Aluminium’s recent announcement of setting up a primary aluminium smelter in Oklahoma, close to the Tulsa Port of Inola, is going to be the first new primary aluminium plant built in the US in 45 years. The USD 4 billion investment by the Middle Eastern business will strengthen domestic aluminium production and support supply chain resilience. But, in the heartland of America, a silent battle is unfolding — wherein at stake is the future of US aluminium smelting, an industry once thriving but now teetering under the weight of soaring electricity costs and the insatiable energy demands of Big Tech’s data centres. Now, the Aluminum Association estimates that a new US smelter would need a minimum 20-year power contract at a price of not more than USD 40 per MWh to be viable at current aluminium prices. Will EGA's plan turn into reality after all the power odds?
The decline of domestic smelting
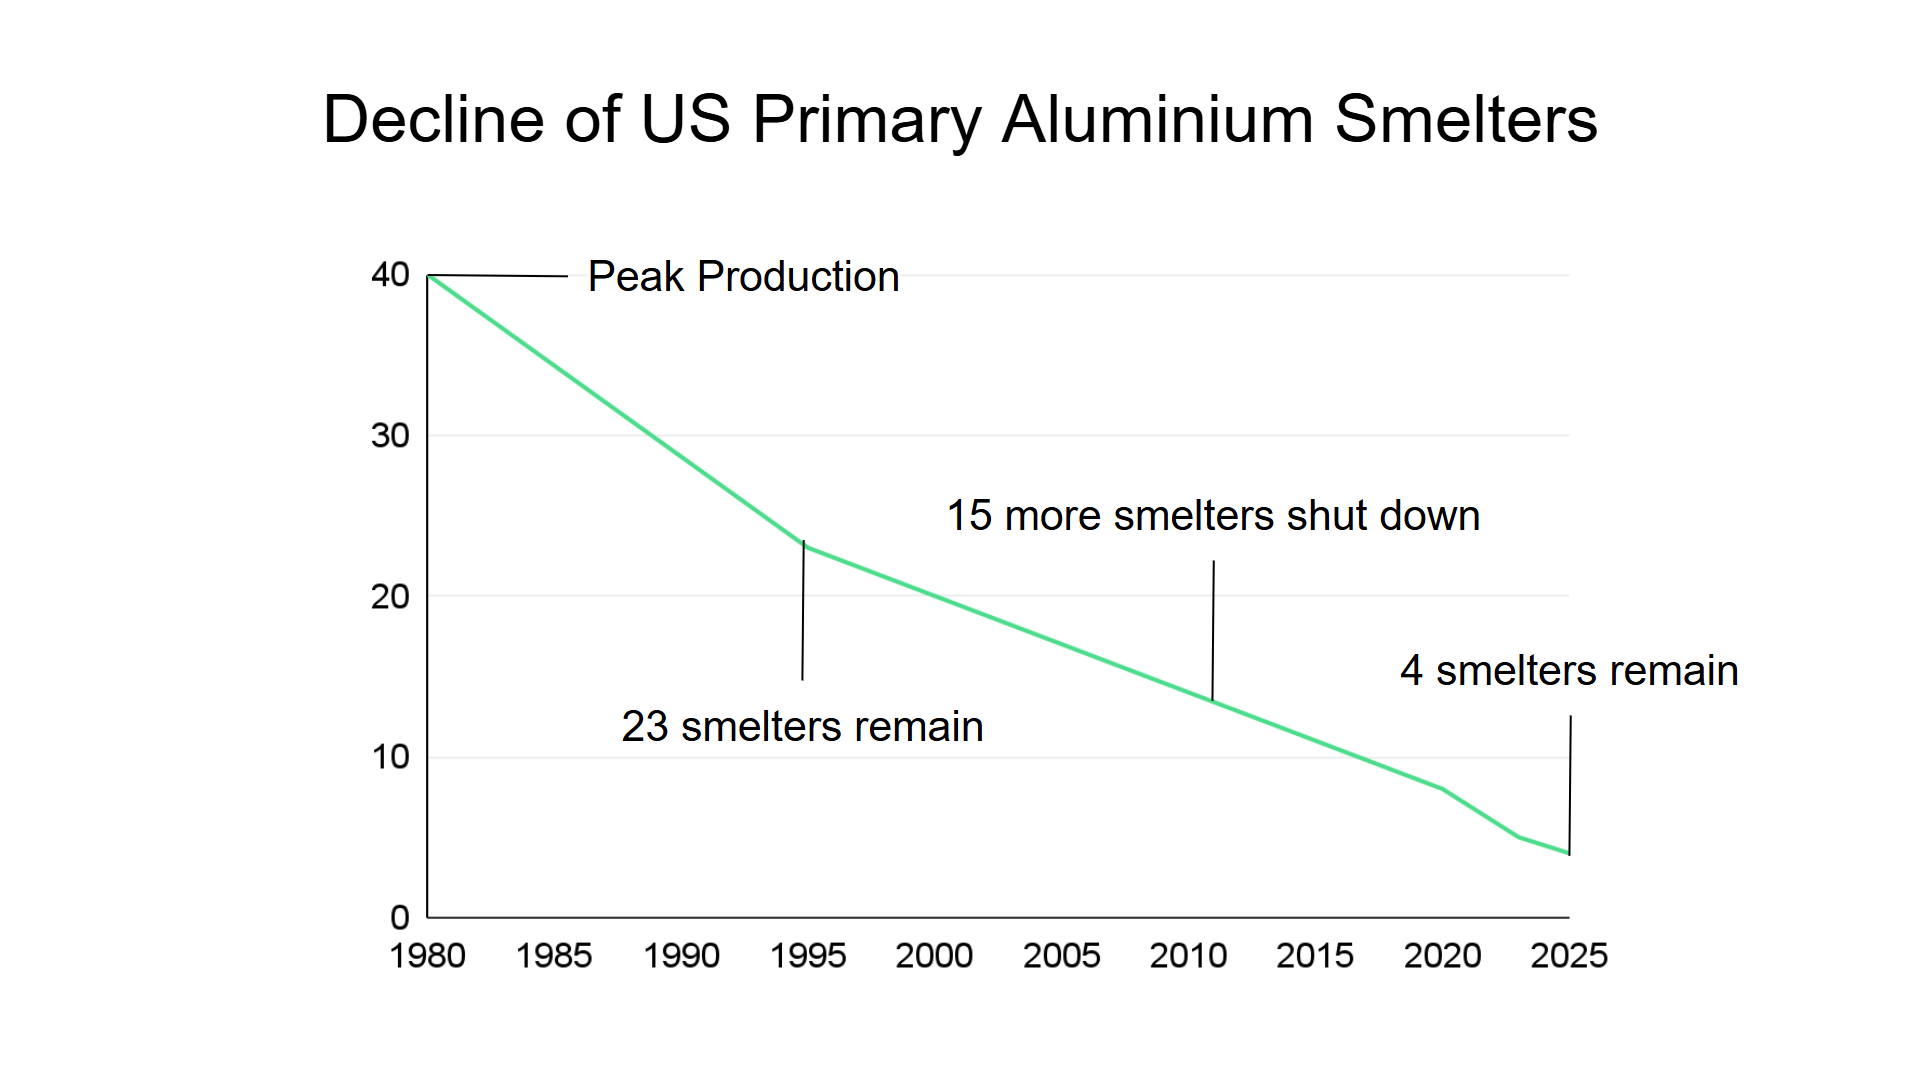
Once a global leader, the US boasted 33 aluminium smelters in 1980. Today, that number has dwindled to six, with only four partially or fully operational. Annual production has plummeted to 700 thousand tonnes, starkly contrasting the nearly 5 million tonnes produced at its peak. High electricity prices have been a primary culprit, rendering many smelters economically unviable. For instance, the New Madrid smelter in Missouri, operated by Magnitude 7 Metals, faced curtailment due to ‘abnormally cold weather’ and persistent profitability challenges, exacerbated by its reliance on high-cost coal power.
In the early 2000s, the US housed 23 primary aluminium smelters operated by 12 companies. However, by the end of 2021, this number had dwindled to six smelters run by just three firms: Alcoa, Century Aluminum, and Magnitude 7 Metals. The closures during this period were primarily due to rising energy costs and increased competition from international producers, particularly China.
In January 2014, Alcoa announced the permanent closure of the remaining two potlines at its Massena East smelter in New York. This decision was part of Alcoa’s strategy to lower its cost base in the commodity business, as the potlines were no longer competitive. The closure reduced Alcoa’s smelting capacity by 84,000 tonnes.
Century Aluminum permanently closed its Ravenswood, West Virginia plant in 2015, citing high energy costs and economic headwinds. The plant had formerly employed 650 workers and was a significant producer of primary aluminium.
In March 2016, Alcoa announced the permanent closure of its Warrick smelter in Evansville, Indiana, due to operational challenges. However, the company restarted three of the five smelting potlines there in 2018, representing approximately 60 per cent of the facility’s production capacity.
In April 2020, Alcoa announced the indefinite curtailment of its Intalco smelting facility in Ferndale, Washington, reducing industry production capacity by 230 thousand tonnes. The decision was driven by the facility’s inability to be competitive in the long term.
Alcoa announced the closure of its Wenatchee Works aluminium smelter in Washington State in December 2021. The smelter had been fully idle since 2015, and the decision to decommission it was based on an analysis that did not support its long-term operation.
In June 2022, Century Aluminum announced the temporary idling of its Hawesville, Kentucky, smelter due to soaring energy prices. The facility, the largest producer of military-grade aluminium in North America, was expected to be idled for approximately nine to twelve months. Over 600 workers were affected by this decision.
In March 2023, Alcoa announced the permanent closure of its Intalco aluminium smelter in Washington State, which had been fully idle since 2020. The company began preparing the site for new economic development opportunities, transferring ownership of approximately 1,600 acres to AltaGas for potential redevelopment aligned with Washington State’s climate ambitions.
In January 2024, the New Madrid smelter in Missouri, operated by Magnitude 7 Metals, was curtailed. This facility had previously been bought out of bankruptcy and restarted after the imposition of 10 per cent duties in 2018. However, tariffs and government spending were insufficient to sustain its operations in the face of high energy costs and global competition.
Big tech’s energy appetite
The rapid expansion of data centres, driven by the growth of artificial intelligence and cloud computing, has intensified competition for electricity. Tech giants are entering long-term power purchase agreements, often willing to pay up to USD 115 per megawatt-hour (MWh) to secure the necessary energy for their operations. In contrast, EGA’s aluminium smelter will require stable electricity rates, ideally under USD 40 per MWh over 20 years, to remain viable.
This disparity places smelters at a significant disadvantage. In Oklahoma, Emirates Global Aluminium’s proposed plant faces challenges in securing competitively priced power despite the state’s abundance of wind and natural gas energy. The intermittent nature of renewable sources like wind further complicates matters for smelters that require a constant power supply.
EGA hasn’t yet signed a power deal for its proposed 600,000-tonne-per-year smelter in Oklahoma. The final go-ahead is contingent on an agreed “power solution framework based on a special rate offer from the Public Service Company of Oklahoma,” according to the Memorandum of Understanding, which opens a new tab signed by state governor Kevin Stitt.
In the meantime, projected searing temperatures across the US and the proliferation of data centres are expected to send electricity consumption to a four-year high this summer, testing the grid and pushing up power prices, the Federal Energy Regulatory Commission said on Thursday.
A shrinking pool of around-the-clock power plants, which are retiring to make way for cleaner energy sources, will further pressure the electrical system, the Federal Energy Regulatory Commission (FERC) said in its annual assessment.
Environmental and Economic Implications — energy import scene
The energy-intensive nature of aluminium production also raises environmental concerns. Most US smelters rely on fossil fuels, contributing to higher carbon emissions. In contrast, Canadian aluminium producers, leveraging hydroelectric power, have the lowest carbon footprint globally. The US imports a significant portion of its aluminium from Canada, highlighting the domestic industry’s struggles.
The United States has imported roughly 21.92 quadrillion Btu of energy in 2024, a modest 1 per cent increase over the previous year. At the heart of this trade balance lie liquid fuels: crude oil and refined petroleum products together account for some 84 per cent of total imports. America’s refineries continue to depend heavily on foreign crude (around 14.5 quads’ worth) while another 3.9 quads of finished fuels such as gasoline and diesel cross borders to meet transportation and industrial demand. Even small shifts in global oil markets, therefore, can have outsized impacts on the nation’s import bill and trade balance.
By contrast, coal imports play a very specialised role. At just 0.44 quads, around 2 per cent of the total, they supply niche markets such as metallurgical coal for steelmaking rather than bulk power generation. Similarly, renewables in the form of imported biomass, wood pellets and biofuels remain peripheral at roughly 0.22 quads (1 per cent). Although these volumes are small today, they hint at potential growth if domestic production and policy incentives align to boost bio-based energy.
Nuclear fuel imports, i.e. uranium and related services, also account for about 0.22 quads or 1 per cent of America’s energy intake. Despite their low share in heat content, these imports underpin critical baseload capacity across the nuclear fleet. Hydrogen, meanwhile, is virtually absent on the import ledger at just 0.04 quads (well under 1 per cent), reflecting its nascent role in US energy and industrial applications. If hydrogen’s promise as a low-carbon fuel materialises, even a small uptick in imports will register as a dramatic percentage growth.
Electricity flowing across the US–Canada border contributes another 0.44 quads (around 2 per cent). Most of it is hydropower from Canada’s resource-rich provinces, used to smooth regional grids during peak demand or when renewables falter. Though modest in volume, these cross-border electrons play a strategic role in balancing supply and keeping emissions down.
Efforts are underway to revitalise the US aluminium sector. Century Aluminium plans to build a new ‘green’ smelter in the Ohio/Mississippi River Basins, aiming to double the country’s primary aluminium capacity. The project, supported by federal funding, seeks to utilise carbon-free energy sources to align with environmental goals.
Primary aluminium production is dominated by a select few companies in the US. One of them is Century Aluminium, which has a nameplate production capacity that exceeds 1 million tonnes. While electricity has never been a meagre cost for smelters in the US, Century seemed to have solved this issue for a while. However, its struggle with local power provider Santee Cooper in South Carolina was public knowledge. In June, Century issued a Worker Adjustment and Retraining Notification (WARN) notice, stating that about 600 workers at the Hawesville smelter in Kentucky are temporarily laid off. Operations are being curtailed entirely for a capacity loss of 250 thousand tonnes.
The recycling alternative
It takes 14,821 kilowatt-hours of electricity to make a tonne of aluminium, according to the US Aluminum Association. A modern-size smelter with an annual capacity of 750 thousand tonnes needs more power than a city the size of Boston.
Given the challenges of primary production, the industry is increasingly turning to recycling. Recycling aluminium requires only 5 per cent of the energy used in primary production, offering a more sustainable and cost-effective alternative. However, low domestic recycling rates and high scrap exports limit this potential. Enhancing scrap recovery and recycling infrastructure could strengthen the supply chain more rapidly and economically than building new smelters.
Even assuming EGA can get a viable long-term power deal, the USD 4 billion project will only pour its first hot metal sometime near the end of the decade.
By this time, 14 new re-melt facilities will have started up, lifting US demand for recyclable scrap aluminium to 6.5 million tonnes, according to the Aluminum Association’s projections. The main constraint on US secondary production growth is a shortage of “scrap”.
The country has an astonishingly low beverage can recycling rate of just 43 per cent and throws away the equivalent of 800 thousand tonnes of aluminium every year.
In a nutshell, the US aluminium industry’s path forward is fraught with challenges. Balancing the energy demands of burgeoning data centres with the needs of traditional industries requires strategic planning and investment. Innovations in energy-efficient smelting technologies, such as inert anode technology developed by Alcoa and Rio Tinto, offer hope for reducing emissions and operational costs.












_md.webp)
_md.webp)
_md.webp)