“2024 was an important year for the apt Group in many respects, characterised by strategic decisions and operational development. Our path toward achieving climate neutrality by the end of 2044 continued,” wrote Manon Gahmann, Director of CSR Compliance. This statement comes amid the European aluminium industry facing a historic pivot of climate legislation and escalating energy prices. It demands circularity that is no longer a choice but an existential factor shaping business models. And Apt Group stands out in this landscape as a regional leader with four production sites across Germany, the Netherlands, and the Czech Republic, pressing 44,393 tonnes of rods and selling 43,392 aluminium profiles for construction, transport, automotive, and industry sectors. In 2024, the company generated EUR 209 million in revenue and employed 757 people.
Image source: https://www.apt-alu-products.com/
Setting science-based targets
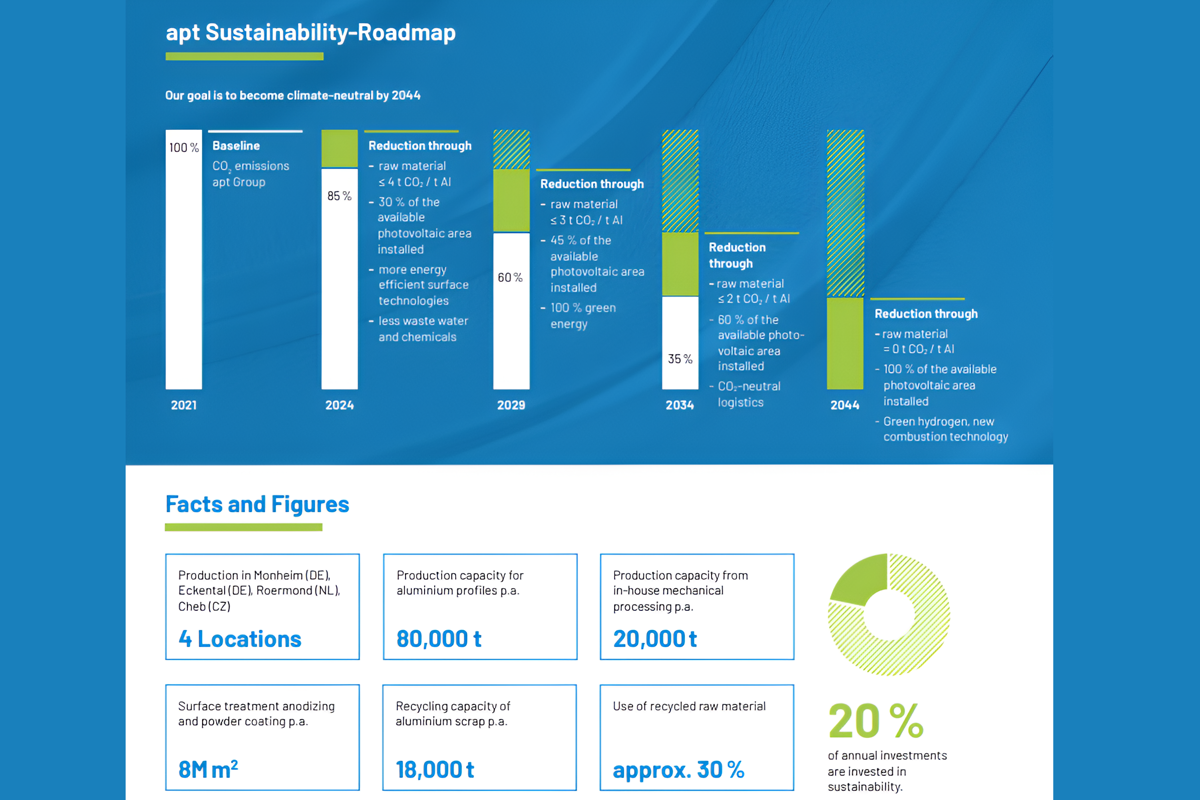
From a climate impact perspective, Apt Group’s strategy is grounded in the Paris Agreement’s 1.5°C roadmap. Their GHG reduction targets are explicit: “Reduce carbon emissions associated with the use of raw materials 4 tonnes of CO₂ per tonne Al by 2024 and 3 tonnes of CO₂ per tonne Al by 2029.” The transition plan sets key milestones: utilising 45 per cent of available land for PV systems by 2029 and switching fully to green electricity by 2030. In 2024, PV installations at the Monheim am Rhein site produced 383,013 kWh, modelling the region’s low-carbon shift.
The company’s gross Scope 1 emissions dropped by 13.21 per cent to 10,705 tonnes, Scope 2 by 15.97 per cent (to 7,623 tonnes of CO₂e), and Scope 3 by 22.07 per cent. Total GHG emissions declined 21.44 per cent to 225,608 tonnes of CO₂e, translating to a GHG intensity of just 4.79 tonnes of CO₂e per profile produced.
For comparison, the European aluminium sector’s average carbon footprint for primary aluminium is now 6.3 kg CO₂ per kg — nearly 60 per cent below the global average, and 78 per cent of European smelters operate with renewable electricity. Europe is expected to see low-carbon power demand by the aluminium industry rise 82 per cent by 2050 as decarbonisation accelerates.
Apt’s approach to recycling economics
The Apt Group’s circular economy integration is not only a strategic focus but an operational reality. Apt’s in-house remelting plant recycles up to 18,000 tonnes of aluminium annually, “allowing process scrap and purchased scrap to be returned to the material cycle again and again with minimal loss of quality.” Despite a dip in recycling volumes in 2024 due to price volatility, “higher purchase prices for recycled aluminium compared to primary aluminium,” the closed-loop partnership with Alu-met remains a keystone. “Thanks to this agreement, apt and Alu-met are both logistically efficient and sustainable — a win-win solution for both companies!” notes Alu-met’s Dr Gerhard Anger.
Globally, aluminium recycling efficiency stands at 76 per cent, rising to 81 per cent in Europe, with 38 million metric tonnes of scrap recycled worldwide in 2024. North America is even higher, with recycled aluminium production now surpassing primary production. From a business perspective, the production cost of recycled aluminium can be as low as USD 0.20-USD 0.50 per kg, compared to USD 2.50–USD 3.50 per kg for primary aluminium, representing dramatic direct cost and energy savings. The CO₂ footprint advantage is even starker: primary production generates 15.1 tonnes of CO₂e per tonne, while recycled is just 0.52 tonnes CO₂e per tonne, a 97 per cent reduction.
Energy efficiency and digital innovation
Significant process upgrades underpinned Apt Group’s performance in 2024. The Monheim am Rhein extrusion line’s new billet furnace delivered “a 15 per cent increase in thermal efficiency, improved product quality, higher metal output due to minimised material loss, lower tool costs and increased productivity.” Meanwhile, Cheb’s new compressed air system enabled “considerable cost savings, lower carbon emissions and increased system reliability”, demonstrating how every incremental efficiency gain can deliver measurable carbon and cost impact.
Apt’s focus on digitalisation and supply chain transparency is equally rigorous. Procurement Manager Mike Vogel explains, “Certified materials, transparent supply chains, resource-conserving processes, and a sense of social responsibility among our suppliers are all important aspects… We focus on long-term partnerships and material substitution and scrutinise every decision from both ecological and commercial perspectives.” Sustainability criteria are increasingly hardwired into purchasing targets, a demand echoed by customers in automotive and construction seeking low-carbon products delivered with ‘recycling rates and certifications’.
Across the sector, such investments are becoming vital, as the aluminium production process remains highly energy-intensive, accounting for over 1.1 Gt CO₂e globally each year. The World Economic Forum and European Aluminium forecast that more than 90 per cent emission reductions can be achieved by 2050, but only with accelerated adoption of renewables and closed-loop recycling.
Supply chains and business resilience in real-time
Apt Group’s risk management is driven by a structured double materiality assessment, pinpointing not only climate and circular economy risks, but also supply chain disruption and labour challenges. “We screen our aluminium suppliers in accordance with OECD Due Diligence Guidance for Responsible Supply Chains… We did not identify any risks in 2024,” the report notes. Supplier audits and sustainability ratings via benchmarks like EcoVadis are standard procedure, as shifting import reliance (now above 51 per cent in Europe) and geopolitical volatility intensify exposure.
The group’s occupational safety programs are robust — ISO 45001-accredited sites, mandatory drills that cut alarm/evacuation times by 30 per cent, and ergonomic improvements are a constant. In 2024, “103 reported work-related accidents and 180 close calls” were documented, with a new training concept targeting 100 per cent staff coverage in 2025. Health, well-being, and skills development are prioritised, not only for compliance but as strategic levers to tackle workforce shortages—now a top risk across European industry.
The bigger picture in 2025
When viewed through the lens of 2025’s market dynamics, Apt Group’s strategy is on trend. The global aluminium market is valued at USD 183.1 billion in 2025, projected to reach USD 331.1 billion by 2035 at a CAGR of 6.1 per cent. Growth is driven by automotive electrification (EVs), green infrastructure, renewables, and lightweight, energy-saving construction. Recycling remains pivotal—businesses increasingly demand recycled aluminium to cut costs and emissions. The narrowing price gap between scrap and primary aluminium further incentivises secondary material use.
Europe’s regulatory momentum is shaping supply and demand. The EU’s Carbon Border Adjustment Mechanism and the Industrial Decarbonisation Accelerator Act are forcing producers, importers, and downstream users to prioritise certified low-carbon aluminium and transparent environmental footprints. Sector leaders are investing in green hydrogen pilots, digital traceability, and supplier screening — all hallmarks of Apt Group’s 2024 report.
Apt Group’s sustainability initiatives that potentially lead to climate neutrality by 2044, including closed-loop recycling partnerships, investments in energy and process efficiency, and supplier transparency, are not isolated projects. As global aluminium demand rises 40 per cent by 2030, cutting carbon and cost through circularity and digitalisation is no longer optional.












_md.webp)
_md.webp)
_md.webp)