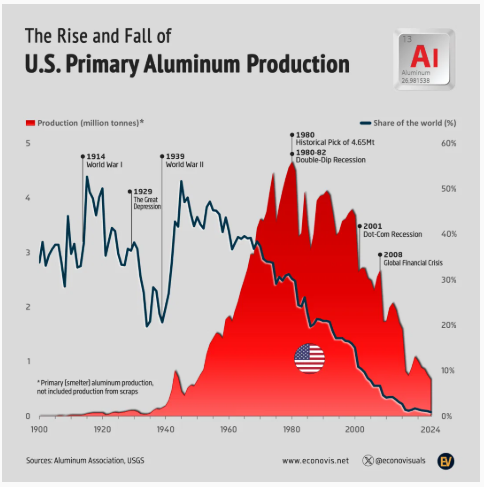
The United States shares a deep, long, and almost personal bond with aluminium as the metal has played a pivotal role in shaping up the nation’s manufacturing base while contributing about USD 228.31 billion to the economy. But at the same time, the industry in the US has weather many highs and lows. The country was once responsible for contributing more than 50 per cent to the world's primary aluminium supply and now it accounts for less than 1 per cent. But has this shift hurt the nation's backbone in the aluminium industry, has it carved out new pathways to sustain its legacy in the sector? Here’s a look at the century-long evolution of America’s aluminium landscape and what's reshaping it.
The journey of aluminium industry in the United States back to World War I (1914-1918) when production was 52,210 tonnes, accounting for more than half of world’s supply. By World War II (1939-1945), the production further grew to 835,000 tonnes. This momentum carried well into the late 20th century, culminating in a peak of 4.65 million tonnes in 1980.
Cut to the late 1990s, aluminium production trend in the US reversed and began to decline, coming in at 3.7 million tonnes between 1998 and 2000. As a consequence, its global share fell to 16 per cent. As the downward trend persisted into the 21st century, the production plummeted to 670,000 tonnes in 2024, representing a mere 0.9 per cent of global output.
So, what happened to the nation which once stood as the world’s power house of primary aluminium production?
The unraveling of an industry
In 1995, the US housed 23 primary aluminium smelters across 14 states. By 2020, 15 facilities shut down and 2 became idle, affecting 45,000 jobs. In 2021, output fell 28 per cent in a single year, pushing the US to ninth position among global primary producers.
In case you wonder why the output volume never revived in the US, here are some of the factors, including high electricity costs. In fact, according to the Aluminum Association, the deregulation of energy prices was the single most important factor that led to the decline in primary aluminium production. The association reported that in 2023, industrial power costs in the states with idled primary aluminium capacity ranged from USD 65.50 per megawatt-hour in Kentucky to USD 82.40 per MWh in Indiana. In contrast, new smelters need a long-term contract at or below USD 40 per MWh to be viable.
Another factor that has caused hindrance to the revival of primary aluminium production in the US includes the influx of low-cost Chinese aluminium into the global market. After China’s entry into the WTO in 2001, global aluminium markets were reshaped by cheap Chinese metal that steadily eroded the competitiveness of US producers.
However, it is important to underpin that even though primary aluminium production collapsed in the domestic market, consumption remained unwavering. In 2024, US consumption of aluminium stood at around 5 million tonnes - more than seven times its domestic primary output. How did they meet the demand? By strengthening its own scrap ecosystem and by leaning heavily on imported metal. In 2024, the nation imported 5.52 million tonnes of aluminium, of which primary aluminium imports were 3.6 million tonnes and semi-finished goods were 1.22 million tonnes, whereas the domestic scrap recovery was 3.47 million tonnes versus 3.31 million tonnes in 2023.
So, if the US can no longer make enough aluminium – it recycles it or buys it.
Explore industry trends and data to drive your business decisions from our 50+ reports across the value chain
Where the investments went: downstream, not upstream
As primary production stagnated, a different aluminium industry quietly strengthened. Over the past decade, investments flowed into extrusions, rolled products, foil, forged suspension components, and recycling. These projects became the true lifelines of the US aluminium sector — even as smelters vanished.
Here’s a glance to the investments and projects from 2015 to 2025:
- Alcoa (now Arconic) completed a USD 300 million expansion of its facility in Tennessee
- Constellium completed a USD 40 million expansion of its automotive structures plant in Van Buren
2016
- Constellium opened a new plant in Bowling Green, KY, as part of a USD150 million joint venture
- Kobelco Aluminum Products & Extrusions Inc. broke ground on USD 47 million aluminum extrusion facility to support the automotive market
2017
- Aleris (now Commonwealth Rolled Products) opened a USD 400 million automotive sheet production facility in Lewisport
- Tri-Arrows Aluminum opened a USD 175 million expansion of its cold rolling and ingot casting facilities at the Logan Aluminum plant in Russellville
- Constellium opened a new plant in White, GA, dedicated to the production of advanced aluminium automotive structural components and crash management systems
- Kobe Aluminum Automotive Products announced a USD 53 million expansion of a facility in Bowling Green, KY, for aluminum forged suspension products
Don't miss out- Buyers are looking for your products on our B2B platform
- Hydro announced a USD 100 million investment to its manufacturing facility in Cressona
- Paramount, CA-based Weber Metals unveiled a USD 180 million investment in a 60,000 tonne forging press
- JW Aluminum announced a USD 255 million expansion of its Goose Creek, SC campus.
- Novelis broke ground on a USD 300 million automotive aluminum sheet manufacturing facility in Guthrie, KY
- Granges announced a USD 26 million investment to restart production of light gauge aluminum foil at its facility in Newport, AR
2019
- Novelis broke ground on a USD 36 million investment to expand and upgrade recycling capacity at its Greensboro, GA facility
- Arconic announced a USD 100 million investment to expand manufacturing capabilities for industrial and automotive aluminum products in its Tennessee Operations facility
2021
- Commonwealth Rolled Products announced a USD 167 million investment to expand and improve its rolling mill in Lewisport
- Hydro announced plans for a new USD 140 million greenfield recycling facility in Cassopolis
- Arconic announced a USD 75 million investment to upgrade its hot mill in Lancaster
- Novelis announced a USD 130 million investment to enhance operations at its plant in Oswego
- Novelis announced a USD 7 million investment at its manufacturing facility in Terre Haute to restart several pieces of idled equipment that produce aluminum foil for household applications
- Matalco announced a USD 53.5 million investment in a new facility in Franklin, KY to produce recycled billet and slab
To know more about the present aluminium industry, read our e-Magazine: American Aluminium Industry: The Path Forward
- Hydro announced a USD 50 million investment in its extrusion plant in Cressona, Pennsylvania, and a USD 15 million investment into its Henderson facility to deliver certified recycled aluminium products
- Aluminum Dynamics announced a USD 2.2 billion investment to build a low-carbon, recycled aluminum flat rolled mill
- Novelis announced a USD 4.1 billion investment to build a fully integrated aluminum manufacturing facility including recycling/casting, hot rolling and finishing for beverage can and automotive markets. It also announced a USD 365 million investment to build a highly advanced recycling center for automotive in North America near its automotive finishing plant in Guthrie, Kentucky.
- Granges announced a USD 52 million investment to expand recycling and casting operations at its plant in Huntingdon, TN.
- Kaiser Aluminum broke ground on a USD 150 million expansion at its facility in Warrick
2023
- Spectro Alloys announced a USD 77 million investment to expand its aluminum recycling facility in Rosemount
2024
- Kentucky Aluminum Processors broke ground on a USD 40 million recycling facility in Russellville
- Hydro announced a USD 85 million investment in a new casting line to strengthen its aluminum recycling plant in Henderson, Kentucky
- Vista Metals announced a USD 60 million facility in Bowling Green, KY to serve the aerospace industry with specialty aluminum products
2025
- Alcoa announced a USD 60 million modernisation of its anode baking furnace at its Massena, NY primary aluminum smelter
- EGA Spectro Alloys announced an expansion of its Rosemount recycled aluminum billet facility that will add about 100 million pounds of annual billet recycling capacity
- Arconic announced a USD 57.5 million expansion of its Davenport, Iowa facility to expand High Purity Aluminum production for defense & aerospace applications
Bolstered by these downstream and recycling projects, the United States has managed to sustain the backbone of its aluminium industry—even as primary smelters shutter across the country. The sector’s economic footprint remains substantial, contributing USD 228.31 billion to the national economy, or 1.02 per cent of GDP. Together, 1,369 firms comprise the manufacturing sector of the US aluminum industry, and these firms employ over 139,778 people. The industry is also responsible for 263,845 supplier jobs. The traditional direct taxes paid by aluminium firms and their employees provide USD 22.74 billion in revenues to the federal, state and local governments.
Tariff – a mistake or a strategic move?
For years, the United States has relied on a steady flow of primary aluminium and semis to meet its domestic needs. So when Washington revived its tariff playbook in 2025, the industry was left asking: why now and why so steep? This time, instead of 10 per cent or 25 per cent duties as were levied in 2018, the tariff is as steep as 50 per cent. Consequences? Primary aluminium imports slumped from 1.85 million tonnes to 1.81 million tonnes in H1 2025 and semi-finished product imports decreased from 631,000 tonnes to 617,000 tonnes. Only scrap imports surged from 328,000 tonnes to 430,000 tonnes, given it is fully exempt from tariffs. The objectives behind this staggering tariff are two-fold – one is to protect the domestic manufacturers from cheap imports and the second is to compel the overseas industries to invest in establishing manufacturing units the US market. Although the second goal looks far-fetched, considering the timeline of 5 to 6 years minimum required for establishing an aluminium smelter, but the exemption of scrap tells a more strategic story. The exemption is well aligned with the the shifting focus to secondary aluminium, with primary smelters closing, unavailability of sufficient energy, and net-zero carbon emissions goals.
A new chapter for American aluminium
The US aluminium story is not one of decline, but of transformation. From a World War-era primary giant to a modern circular-economy player, the nation has repositioned itself around recycled metal, technologically advanced semis, and high-value manufacturing. The industry has simply changed its centre of gravity — from producing metal to re-making it.