15 countries make it to the headline of Global EV sales 2025 with 90% contribution
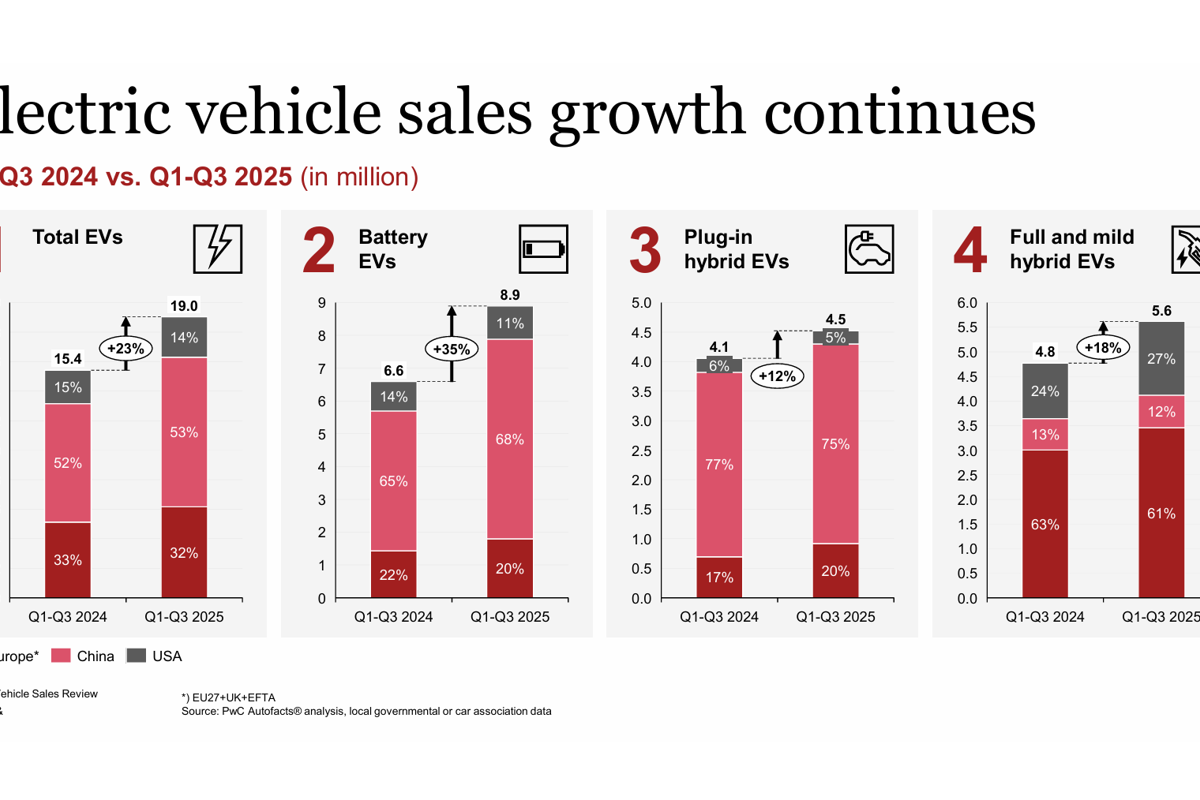
World electric vehicle sales in October stood at 1,783,000 units, growing 10.5 per cent year-on-year. The cumulative sales of electric vehicles from January to October 2025 have been calculated to cross 16.5 million with a 23 per cent rise as compared to YTD 2024 (Jan-Oct). In this, China has remained the leading power with 10.3 million sales for the ten months (up 22 per cent), Europe saw 3.4 million sales with a 32 per cent hike, North America sold 1.6 million units, which was 4 per cent higher than the number for the same period last year. The rest of the world registered 1.3 million sales with over 48 per cent boost as compared to YTD 2024, shared RHO motion.
Image source: https://www.strategyand.pwc.com/
Explore- Most accurate data to drive business decisions with 50+ reports across the value chain
Country-wise sales figures for Jan to Oct 2025 compared to the last year
15 countries, i.e. China, the United States, Germany, the United Kingdom, France, India, Korea, Italy, Sweden, Canada, Brazil, Thailand, Norway, Japan and Finland, have shown promising numbers to lead the EV game forward.
In the final quarter of 2024, China consistently crossed the 1.2–1.3 million mark each month, and although early 2025 opened with a predictable seasonal dip, the country was back above 1.3 million by September and October.
Across the Pacific, the United States of America’s tail end of 2024 showed stable enthusiasm at around 140,000–162,000 units, whereas 2025 quickly turned into a rollercoaster. Sales shot up past 150,000 in March and April, climbed again to nearly 192,000 by September, and then dropped to just 94,000 in October. The sales drop is majorly contributed to the fact that the government-announced tax credit of up to USD 7500 was stripped off since October 1, 2025. Its numbers hover steadily in the 55,000–75,000 band across both years, rising slightly in early 2025 before correcting modestly in the summer.
After ending 2024 with a confident 60,000 units in December, the United Kingdom market sank to just 30,000 in February 2025 before unexpectedly doubling to 116,000 by September. It’s hard not to read these swings as the impact of fleet cycles, quarter-end targets, or regulatory deadlines, factors that push the UK market into sudden bursts rather than sustained climbs.
France, meanwhile, moves with unhurried consistency. Hovering between 30,000 and 48,000 throughout 2025, its EV adoption looks less like a race and more like an organised transition that’s now deeply embedded in household decision-making.
Among emerging markets, India’s story is one of patient but undeniable upward movement. Monthly sales in the 10,000–12,000 range in late 2024 give way to 12,000 (January 2025) - 20,000 (October 2025) through most of 2025. However, when compared to the total vehicle sales number, the share of EV sales still remains on the lower side, as affordability remains a major factor.
South Korea, on the other hand, shows a sharper growth curve, climbing from 13,000 in January to a peak of 29,000 in September before easing back.
The smaller and mid-sized markets contribute their own quiet narratives. Italy and Sweden maintain slow but steady growth, moving in well-defined bands without major surprises.
Canada holds a consistent 9,000-12,000 through the year, while Norway, the early global poster child for EV adoption, now appears to be levelling off, not out of reluctance but simply because there’s little runway left for exponential growth. However, Norway has set a new adoption record, with EVs accounting for 97.2 per cent of all new passenger vehicles registered and delivered in July 2025.
Thailand remains one of the more intriguing climbers, reflecting the country’s increasingly aggressive EV manufacturing strategy, while Japan’s low and stagnant numbers reiterate its ongoing hesitation in embracing battery-electric vehicles despite its automotive might. Finland, modest as ever, stays anchored in the 2,000-4,000 range.
Don't miss out- Buyers are looking for your products on our B2B platform
EV types, mainly BEVs & PHEVs, gulp a major share of the sales trend
Europe, more than any other region, displays a layered but accelerating transition in EV technology type. Across the continent’s major markets, BEVs crossed 1.08 million sales in the first three quarters and growing more than 27 per cent year-on-year, supported heavily by Germany’s remarkable 38 per cent surge and the UK and France’s steady gains.
Smaller northern markets like Denmark reached a 70 per cent BEV share and Norway is sitting near full electrification. Yet far from uniformity, PHEVs have staged an impressive rebound in 2025, with many markets, especially Italy and Spain, more than doubling plug-in hybrid sales, largely due to CO₂-compliance strategies and strong fleet demand.
Hybrids, meanwhile, quietly remain Europe’s largest electrified category with 3.45 million registrations and a 34.8 per cent share, signalling that while the continent is decisively moving toward full electrification, its traditional comfort in hybrid technology still serves as a stabilising backbone.
China tells an almost exclusively BEV-revolving story. Through the first three quarters of 2025, China sold over 6 million battery-electric vehicles (BEV), marking a staggering 43 per cent increase from last year and accounting for more BEV sales than Europe and the United States combined. This overwhelming preference for BEVs has pushed their market share to 31.4 per cent, while PHEVs, once a meaningful stepping stone, have begun to shrink, down 6 per cent year-on-year.
Hybrids remain marginal, barely touching 4 per cent of the market, reflecting a consumer base that has leapfrogged transitional technologies and gone straight to full electrification.
Unlike Europe or China, the US maintains a three-way split with all technologies still competing for relevance. BEVs have grown respectably, touching just over 1 million sales and rising 12 per cent year-on-year; however, their share remains at 8.3 per cent.
PHEVs represent only a sliver of the market at under 2 per cent, though they have inched upward this year. Hybrids, however, have become America’s quiet powerhouse, with 1.5 million sales and more than a 12 per cent share. They serve as the country’s preferred middle path, particularly for buyers still anxious about charging, cold-weather range, or long-distance travel.
In Japan, hybrids reign almost without challenge, accounting for more than 60 per cent of all vehicle sales and rising modestly year-on-year. BEVs and PHEVs remain tiny, with BEV sales at just 27,668 units and a market share of barely 1.4 per cent.
South Korea sits somewhere between Japan’s conservatism and China’s rapid leap. BEV sales have risen sharply (up 57 per cent Y-o-Y), with Q3 alone growing by more than 85 per cent. Yet even with that momentum, hybrids still claim a substantial portion of the market, accounting for more than a third of all registrations. PHEVs, while growing fast in percentage terms, remain small in real volume.
<iframe width="696" height="391" src="https://www.youtube.com/embed/Y8YDIDCMGjY" title="15 Countries Drive 90% of Global EV Sales in 2025 | AL Circle" frameborder="0" allow="accelerometer; autoplay; clipboard-write; encrypted-media; gyroscope; picture-in-picture; web-share" referrerpolicy="strict-origin-when-cross-origin" allowfullscreen></iframe>
India, Indonesia and Turkey collectively represent the emerging-market face of electrification—one defined by enthusiasm tempered by economic and infrastructural realities. India has nearly doubled its BEV sales this year, reaching 120,541 units, while hybrids have carved a stable 8.8 per cent market share. PHEVs are tiny but growing rapidly from a negligible base. Meanwhile, Indonesia’s BEV sales surged nearly 130 per cent year-on-year, and Turkey’s jumped 93 per cent, with both markets also recording steep increases in PHEV and hybrid volumes.
Taken together, the global picture shows three distinct electrification identities. BEVs are now the unambiguous global growth engine, with 9.53 million sales, a 36 per cent surge that screams central role in the industry's future.
Must read: Key industry individuals share their thoughts on the trending topics
Influence of various vehicle models (read Chinese vehicle models) on the sales numbers
The January-October 2025 data reveal a market where Chinese brands are not just dominating volumes but increasingly reshaping the competitive hierarchy itself. Wuling’s Hongguang MINI EV, a longstanding favourite in China’s budget EV segment, more than doubled its year-to-date sales to 368,000 units — a staggering 157 per cent.
Geely’s Xingyuan is the breakout star of the year, exploding from just 16,000 units last year to 388,000 in 2025, recording an extraordinary 2,300 per cent increase.
BYD’s portfolio, meanwhile, continues to demonstrate both depth and diversity. The Dolphin, Seagull, Seal 06, Yuan Up, and the Qin Plus collectively show that BYD’s strategy of saturating multiple price points is paying off — though unevenly. Models like the Dolphin and Yuan Up posted solid double-digit gains, but the Qin Plus and Seagull registered year-on-year declines.
Tesla stands out as the only global brand in this list, but its performance reflects a different phase of its lifecycle. The Model Y, once the world’s best-selling passenger vehicle, fell by 11.5 per cent year-on-year, slipping from 824,000 units in Jan–Oct 2024 to 729,000 this year.
Xiaomi’s entry, the YU7, opens an entirely new narrative, with 81,000 units sold in its first reporting year. It shows how consumer electronics companies entering the EV sector are being welcomed by technology-oriented younger buyers.
For the 10 months of 2025, electric vehicle brands have seen utmost turmoil with on the one hand tariffs and on the other subsidies and credits. Countries like Germany (German Chancellor Friedrich Merz announced a EUR 3 billion agreement by the German Coalition on EV incentives), the United Kingdom (provides a discount of up to GBP 3,750 on new eligible EVs priced under GBP 37,000), India (FAME subsidy), Italy (approved nearly USD 700 million in new subsidies) and many others have offered hefty subsidies and benefits to boost EV purchase.
The success of electric vehicles lies in the easing of finances. In many markets, subsidies softened the blow of rising tariffs on Chinese imports, while in others, incentive sunsets, like the US tax credit expiry, directly reshaped monthly sales trajectories.
Information credit: Marklines, PwC, Rho Motion, The Driven.io and Reuters

Unlock full access – sign up for FREE.
Key benefits
Sustainability and new formats drive a surge in the beverage can market
Next articleAsian automaker taps AEM for aluminium motor tech amidst copper concerns
Grow with
AL Circle













_md.webp)








