The European aluminium industry needs swift action to keep the region competitive in the wake of high energy prices, expensive raw materials and increased global competition, Paul Voss, director general of industry body European Aluminium, told S&P Global Commodity Insights in an interview at the aluminium trade fair in Dusseldorf on October 8, 2024. "There is a need for a serious shift to competitiveness for the European aluminium industry; we won't sit and wait for someone to solve our problems; we must engage," Voss said.
According to International Aluminium Institute (IAI) data, the European aluminium industry has steadily declined across the past decade, with Western and Central European primary aluminium production deflating 25.5 per cent from 2010 (production during this year was 3.8 million tonnes) to 2.83 million tonnes in 2024. Meanwhile, primary aluminium production in Russia and Eastern Europe only fell 5.57 per cent (production during calendar year 2024 was 4.16 million tonnes) from 4.25 million tonnes produced in 2010, IAI data showed.
IAI depicts the primary aluminium production data for several regions across the globe, including Africa, North America, South America, Asia, Western & Central Europe, Russia & Eastern Europe, Oceania, Gulf Cooperation Council, China, and an estimated unreported figure. The cumulative primary aluminium output from January 2024 to December 2024 accounted for 72,758 thousand tonnes. The Y-o-Y growth of production was close to 2.8 per cent, wherein production for the previous calendar year was 70,716 thousand tonnes.
Overall, global primary aluminium production appears to fluctuate throughout the year. While some regions show consistent production levels, others exhibit noticeable variations.
According to the data fetched from the Global Aluminium Trade Monitor (GATM), in 2024, the EU's aluminium trade saw a continuation of trends from prior years, with imports significantly outpacing exports. Through October 2024, the EU imported an estimated 6,615,968 tonnes of aluminium, while exports stood at 1,677,842 tonnes. From a year-on-year perspective, both imports and exports have experienced significant fluctuations. Imports increased by approximately 11.6 per cent in 2020 (7,383,062 tonnes) and 9.1 per cent in 2021 (8,052,236 tonnes), followed by a more elevated rise of 13.3 per cent in 2022 (9,122,648 tonnes). However, in 2023, imports declined by 8.5 per cent to 8,347,217 tonnes. Exports, on the other hand, surged by 34.3 per cent in 2020 (2,254,016 tonnes) but then slowed down to 4.8 per cent in 2021 (2,361,840 tonnes). Subsequent years saw declines of 7.9 per cent in 2022 (2,175,322 tonnes) and 7.6 per cent in 2023 (2,009,162 tonnes).
The United Kingdom's aluminium trade between 2020 and YTD October 2024, as per HMRC data, reveals a consistent trend of imports significantly outpacing exports. In 2020, the UK exported 410,539 tonnes of aluminium while importing 825,864 tonnes. This import-heavy trade balance has continued throughout the period.
In 2021, UK exports saw an increase of 4.05 per cent compared to 2020, reaching 427,052 tonnes. Imports remained relatively stable, increasing marginally by 0.01 per cent. Exports in 2022 declined slightly by 3.29 per cent compared to the previous year, reaching 413,054 tonnes. Imports, however, saw a significant increase of 13.16 per cent, reaching 935,942 tonnes. During 2023, exports experienced a substantial decline of 16.88 per cent, dropping to 343,383 tonnes. Imports also declined by 9.85 per cent, reaching 843,523 tonnes. During YTD October 2024, UK exports and imports saw a shifting trend, reaching 311,628 tonnes and 731,805 tonnes, respectively.
As for Iceland, exports saw a modest increase to 832,983 tonnes 5 years ago in 2021. Imports experienced a substantial increase of 111.54 per cent, reaching 23,240 tonnes. In 2022, overall aluminium exports continued to grow, increasing by 2.62 per cent compared to the previous year, reaching 854,722 tonnes. Imports, however, declined by 19.50 per cent, reaching 18,913 tonnes. Exports and imports went opposite ways in 2023, wherein the first saw a further increase of 1.34 per cent Y-o-Y (866,143 tonnes). Contradictorily, imports declined significantly by 49.72 per cent, reaching 9,401 tonnes. For YTD October 2024, exports dropped to a low at 674,354 tonnes. Imports experienced an increase of 11,253 tonnes within the first 10 months of the year.
In 2024, the US and the UK implemented a ban on the import of metals produced in Russia. The EU has also banned aluminium products, including wire, tube, pipe, and foil, which make up less than 15 per cent of its total imports.
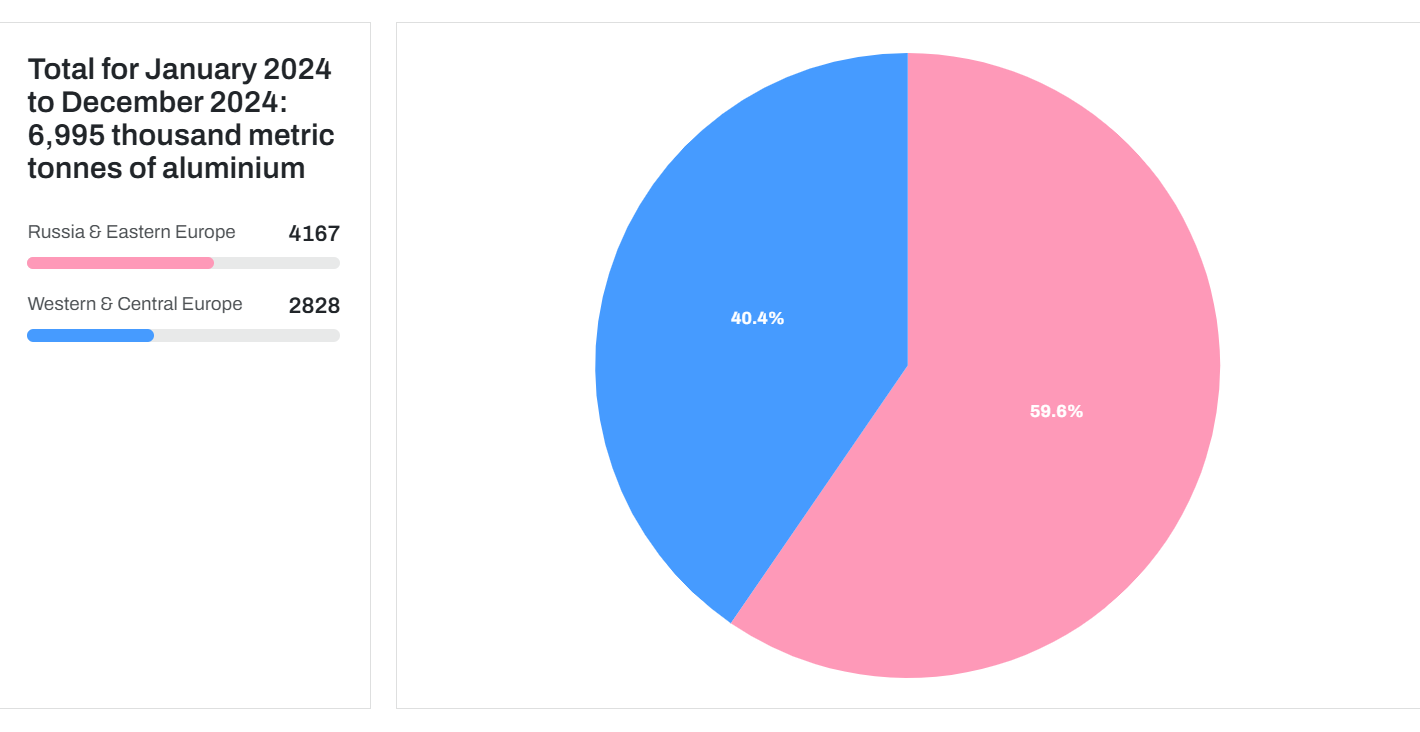 Image Source: International Aluminium Institute
Looking specifically at Europe, we can see that production levels in Western & Central Europe generally hover around the range of 230-240 thousand tonnes. There are some minor fluctuations, but the overall trend seems relatively stable. Overall yearly production total stood at 2.83 million tonnes.
In contrast, Russia & Eastern Europe demonstrate a more pronounced upward trend, with production steadily increasing from around 320 thousand tonnes in January to over 400 thousand tonnes by the end of the year. The calculated annual production was about 4.16 million tonnes in this region during the observed period.
Comparing Europe to other regions, we can observe that:
- China remains the dominant producer, with estimated production consistently exceeding 3 million tonnes throughout the year.
- North America and South America also exhibit relatively stable production levels, with North America producing around 300-350 thousand tonnes and South America around 120-130 thousand tonnes.
- Africa and Oceania show more modest production figures, with Africa generally producing less than 150 thousand metric tons and Oceania around 500-550 thousand tonnes.
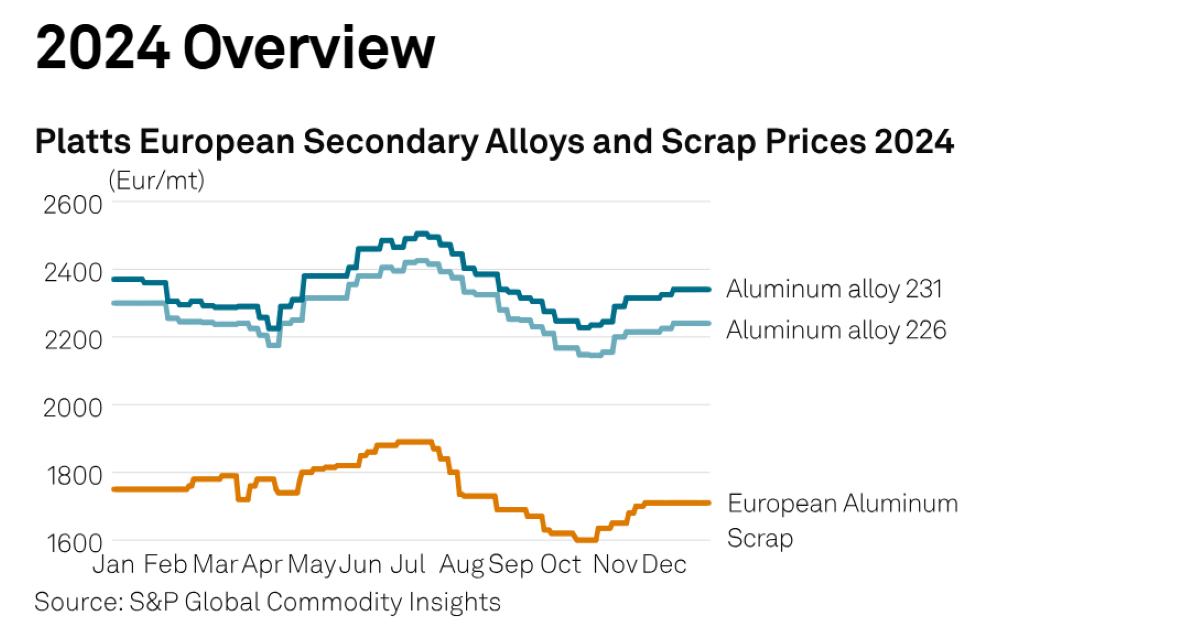 Image Source: S&P Global Commodity Insights
Lacklustre demand and overcapacity in Europe are anticipated to create a challenging environment for the European aluminium secondary alloys market in 2025 amid a weaker overall economic climate. At the same time, global competition for aluminium scrap is expected to keep prices under pressure, with significant volumes being exported to Asia.
The European 226-grade secondary alloy began last year priced between €2,280 and €2,320 per tonne as of January 5 2024, with a midpoint of €2,300 per tonne. Prices remained relatively stable throughout the first quarter but rose during the second quarter and into the summer, reaching a yearly high of €2,380-€2,470 per tonne on July 5, with a midpoint of €2,425 per tonne.
Throughout the year, prices for aluminium secondary alloys were largely influenced by scrap prices. Increased demand from Asia for scrap exerted upward pressure on this material. This trend peaked in the summer, with Platts' daily assessment for high-grade auto shred scrap—meeting ISRI Twitch specifications—hitting an annual high of €1,890 per tonne DDP Germany between June 25 and July 15 2024. Platts is part of S&P Global Commodity Insights.
Following a period of reduced market liquidity over the summer, the market began a downward trend in the second half of 2024. Aluminium scrap prices declined as Asian demand weakened, which eased pressure on Twitch prices in the latter half of the year. Combined with persistently weak demand, this contributed to downward pressure on aluminium secondary alloy prices.
As the new year begins, the market faces a tense economic backdrop. S&P Global Purchasing Managers' Index (PMI) data indicated that the eurozone economy contracted in December for the second consecutive month, reflecting a sharp decline in manufacturing output. Germany's factory output recorded the second-steepest decline, surpassed only by France.
European lion's share of trading is potent to be influenced by CBAM (Carbon Border Adjustment Mechanism), a tax on imported goods that are carbon intensive. Rating agency ICRA (Investment Information and Credit Rating Agency) conveyed in the first half of 2024 that the given carbon tax may have a limited impact on domestic primary aluminium producers.
The CBAM or carbon tax (a kind of import duty) will come into effect from January 1, 2026.
"The Carbon Border Adjustment Mechanism (CBAM) ruling on exports to the European Union (EU) will have a limited impact on the domestic primary aluminium producers. This is because the present notification covers the financial impact w.e.f January 1, 2026, on direct process-related emission only, while excluding the indirect emission, which contributes 80 per cent to the total emissions in the primary aluminium production process," Icra said in a statement.
The indirect emissions arise primarily from the generation of electricity that is subsequently used in the smelting process.
India exported approximately 0.7 million tonnes (24 per cent of exports) of primary aluminium to European countries in FY23. However, unlike steel, the carbon tax is not anticipated to significantly impact the export competitiveness of domestic primary aluminium producers. This is because the taxes incurred under the Carbon Border Adjustment Mechanism (CBAM) are expected to remain between USD 50 and USD 140 per tonne between 2026 and 2034. This translates to a range of 2-6 per cent of the current aluminium prices, according to Jayanta Roy, Senior Vice-President and Group Head, Corporate Sector Ratings, ICRA.
In conclusion, the European aluminium industry is at a critical juncture, facing significant challenges from high energy costs, volatile raw material prices, and increasing global competition. The steady decline in primary aluminium production within Europe, contrasted with growth in other regions such as Russia and China, underscores the need for decisive actions to revitalise the sector's competitiveness. Global market dynamics, including shifts in trade patterns, fluctuating demand, and the rise of environmentally focused regulations such as the Carbon Border Adjustment Mechanism (CBAM), are shaping the aluminium industry's trajectory for 2025 and beyond. While the CBAM's impact on European aluminium imports remains to be fully realised, its influence on export competitiveness for key suppliers like India appears to be moderate in the near term. The secondary alloys market, too, faces headwinds with declining demand and intensifying competition for aluminium scrap. As the sector grapples with a challenging economic environment, stabilising market prices and enhancing supply chain efficiency will be crucial.













_md.webp)








