06 APRIL 2016<a href= http:// www.metalminer.com ' target='_blank'> Metalminer </a>
Chinese production down; Non-Chinese production up
Edited by : AL CIRCLE
2 min read

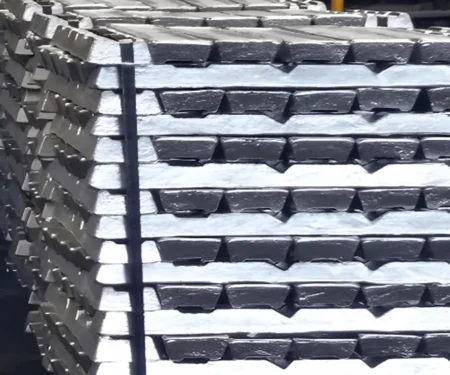
Aluminium in China jumped to its highest price point in about six months. Chinese production seems to have fallen sharply over December and January which would help explain the strength of the local rally in prices.
Meanwhile, according to the International Aluminium Institute (IAI), non-Chinese global output rose by 3.7 per cent in the first two months of 2016, an acceleration from growth of 2.5 per cent in 2015. That’s a surprising outcome for a market burdened by high stocks and with prices hovering near a six-year low. Higher production excluding China has also led to steady aluminium Midwest premiums, which are hovering near $0.09 per pound. Aluminium has also recently moved from backwardation to contango as new supply has come in.
Aluminium prices missing the broad metals rally
Although prices in China rallied, aluminium LME prices finished the month down. While most base metals gained in Q1, aluminium has simply missed the rally.
One of the major challenges for the global aluminium industry has been the rise in Chinese aluminium exports but recent trade numbers are encouraging for global aluminium markets. In February, China’s aluminium exports declined more than 33 per cent year-over-year, the lowest in two years.
What this means for metal buyers?
The long-term outlook for aluminium is still poor. Aluminium will likely need a bull commodity market to make a substantial rally. Prices in the short-term could rise however, following the recent strength in the base metal sector and the fact that bargain hunters might want to lift prices after the slump seen last year.
Meanwhile, according to the International Aluminium Institute (IAI), non-Chinese global output rose by 3.7 per cent in the first two months of 2016, an acceleration from growth of 2.5 per cent in 2015. That’s a surprising outcome for a market burdened by high stocks and with prices hovering near a six-year low. Higher production excluding China has also led to steady aluminium Midwest premiums, which are hovering near $0.09 per pound. Aluminium has also recently moved from backwardation to contango as new supply has come in.
Aluminium prices missing the broad metals rally
Although prices in China rallied, aluminium LME prices finished the month down. While most base metals gained in Q1, aluminium has simply missed the rally.
One of the major challenges for the global aluminium industry has been the rise in Chinese aluminium exports but recent trade numbers are encouraging for global aluminium markets. In February, China’s aluminium exports declined more than 33 per cent year-over-year, the lowest in two years.
What this means for metal buyers?
The long-term outlook for aluminium is still poor. Aluminium will likely need a bull commodity market to make a substantial rally. Prices in the short-term could rise however, following the recent strength in the base metal sector and the fact that bargain hunters might want to lift prices after the slump seen last year.
Unlock full access – sign up for FREE.
Key benefits
Find exclusive data-driven insights and in-depth analysis
Get our daily newsletter delivered straight to your inbox
Access real-time and historical price trends from global indices
Post and respond to latest business leads
Stay ahead with alerts on learning tools
...and so much more!SIGN UP / LOGIN
Previous article
Chinese aluminium smelters to benefit from power reform
Next articleChina ramps up aluminium output as 20% rally allows restarts
Grow with
AL Circle