30 DECEMBER 2013www.financialexpress.com
Underperform rating on Hindalco shares
Edited by : AL CIRCLE
1 min read

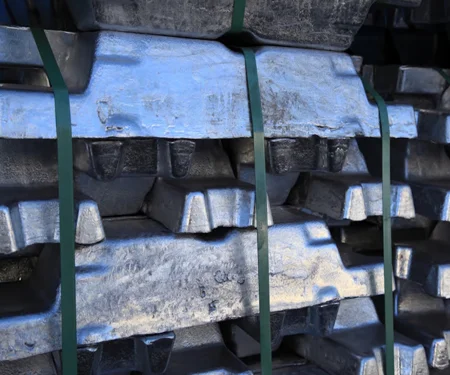
Hindalco Industries Ltd, caught in a weak global aluminium cycle, is facing headwinds in domestic operations. While commissioning of long-awaited Greenfield capacities (Utkal refinery and Mahan smelter) will aid volume growth, lack of captive coal and high capex costs will lead to losses.
We remain cautious on Mahan coal block timelines with downside risk if clearances get delayed further. At Novelis, benefits of volume expansion are back-ended and continued pressure on ‘scrap less LME’ prices will arrest margin expansion. Given weak operating cash flows, balance sheet health is unlikely to improve even as capex intensity starts tapering FY16 onwards. We maintain ‘underperformer’ with a 12-month price target of R89.
While commissioning of Mahan coal block would mitigate the losses, we see meaningful contribution only after FY16. At existing operations, margins will be under pressure due to muted realisation (2% CAGR over FY13-16E) and higher operating costs. We expect subdued aluminium prices as a slew of Chinese capacities against weak demand have led to higher inventories.
Previous article
Aluminium up 0.1% on spot demand, short-covering
Next articleJiaozuo Wanfang to buy 20% interest in China Rare Metals at a 25.2% premium
Grow with
AL Circle