“The Brazilian aluminium industry is closely monitoring developments in Europe, as the tensions in the geopolitical scenario have direct effects on global supply chains, especially on the availability and price of the metal”, Janaina Donas, Executive President of the Brazilian Aluminum Association (ABAL)
- Category
- Interview
- Date
- 04 July 2022
- Source
- AlCircle.com
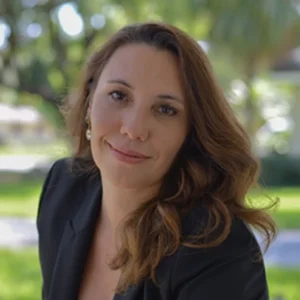
As a corporate affairs executive, Janaina Donas acquired a broad experience in government relations, communications, sustainability, community relations and business development. She graduated in International Relations, with an MBA in Business Administration. Before taking on the role as Executive President of the Brazilian Aluminum Association (ABAL), she served as Regional Director of External Relations and New Business for Latin America at Newmont Corporation, in Peru and Miami. She also worked as Government Relations and Communication Director for Alcoa, 3M and as an associated partner at Patri, a Government Relations and Public Policy Consulting Company in Brazil.
AlCircle: The European aluminium industry is facing critical challenges since the previous year. How has this impacted the Brazilian aluminium industry?
Janaina Donas: Historically, the European Union's share of Brazilian aluminium exports corresponds to around 5% of the total. Brazil, which once ranked 6th in the global production ranking, standing out as a metal exporter, saw its position drops to 15th place as of 2012, as a result of the difficulties faced by the aluminium industry globally, with the strong competition in the international market with Chinese products, drop in commodity prices, added to the systematic increase in energy costs. As in many countries, companies operating in Brazil had to make difficult decisions to cut primary aluminium production.
About 10 years later, the Brazilian industry has shown resilience in the search for alternatives and solutions that allow the recovery of its competitiveness and reversal of the deindustrialization process.
We ended last year with a historic record for domestic consumption, with a growth of 10.9%. This growth in demand is also being accompanied by growth in supply, with significant investments in resuming interrupted production, equivalent to 447 thousand tons.
By 2025, the sector will invest around BRL 30 billion in actions that range from increasing primary aluminium production capacity to modernizing the industrial park, diversifying the energy matrix, new bauxite mines, innovation and environmental management.
In addition, Brazil is also a highlight in aluminium recycling with a scrap recovery rate of 54%, against the world average of 29%.
AlCircle: How does the aluminium production curb in Europe influence Brazil's aluminium sector? Are the exports to Europe increasing?
Janaina Donas: There was an increase of approximately 25% in the export of primary aluminium to Europe, the main product exported to the region.
AlCircle: The LME aluminium price fluctuation, the soaring gas price and geopolitical tension in Europe has put an effect on the aluminium sector. How are you addressing this situation in these times?
Janaina Donas: In addition to the concern with social impacts, the Brazilian aluminium industry is closely monitoring developments in Europe, as the tensions in the geopolitical scenario have direct effects on global supply chains, especially on the availability and price of the metal. On the other hand, it is important to highlight that the recent resumption of aluminium production in the country is primarily aimed at meeting domestic demand for metal and the fact that Brazilian production is entirely based on renewable energy sources (hydroelectric, wind and biomass) is certainly setting up on an opportunity.
In this sense, for the country to be able to realize all its potential, ABAL operates in a series of discussions to promote the improvement of the business environment, regulatory improvement and the reduction of bottlenecks that directly affect the competitiveness of the industry, including tax, logistics and energy issues.
AlCircle: Is the crisis in the European aluminium industry turned into an advantage to the Brazil aluminium industry? If yes, then please detail it.
Janaina Donas: The competitive advantage of the Brazilian industry should not be attributed to the crisis experienced by European industry, but to the resilience and effort undertaken in the search for solutions that would guarantee the maintenance of our operations competitively and sustainably, in the broad sense, from sources clean and economically viable.
In this sense, the alignment of concerns with climate change and the need to meet the targets for reducing carbon emissions provide opportunities for Brazilian aluminium.
In addition to producing from a clean energy matrix, the Brazilian aluminium industry has invested heavily in self-generation, renewable sources, and in the development and adoption of technologies that make the carbon footprint of the Brazilian metal 4.6 times smaller than the world average.
Another competitive differential that corroborates the sustainable performance of the sector is that more than half of the aluminium consumed in the country (54%) comes from recycling, a rate well above the world average (29%). In environmental terms, this is a formidable gain, since recycled aluminium reduces greenhouse gas (GHG) emissions by 95% and consumes only 5% of electrical energy when compared to the primary metal production process.
AlCircle: Which European nations are the biggest importers of aluminium produced in Brazil?
Janaina Donas: Brazilian exports of aluminium and its products to European countries totalled 47 thousand tons in 2021. Of this total, 30 thousand tons were primary aluminium; 10 thousand tons of aluminium alloys; 5.0 thousand tons of castings and 1.3 thousand tons of sheets. The main destinations were Switzerland, Holland, Spain and Italy.
