CRU: Understanding Where Future Aluminium Smelters will Develop
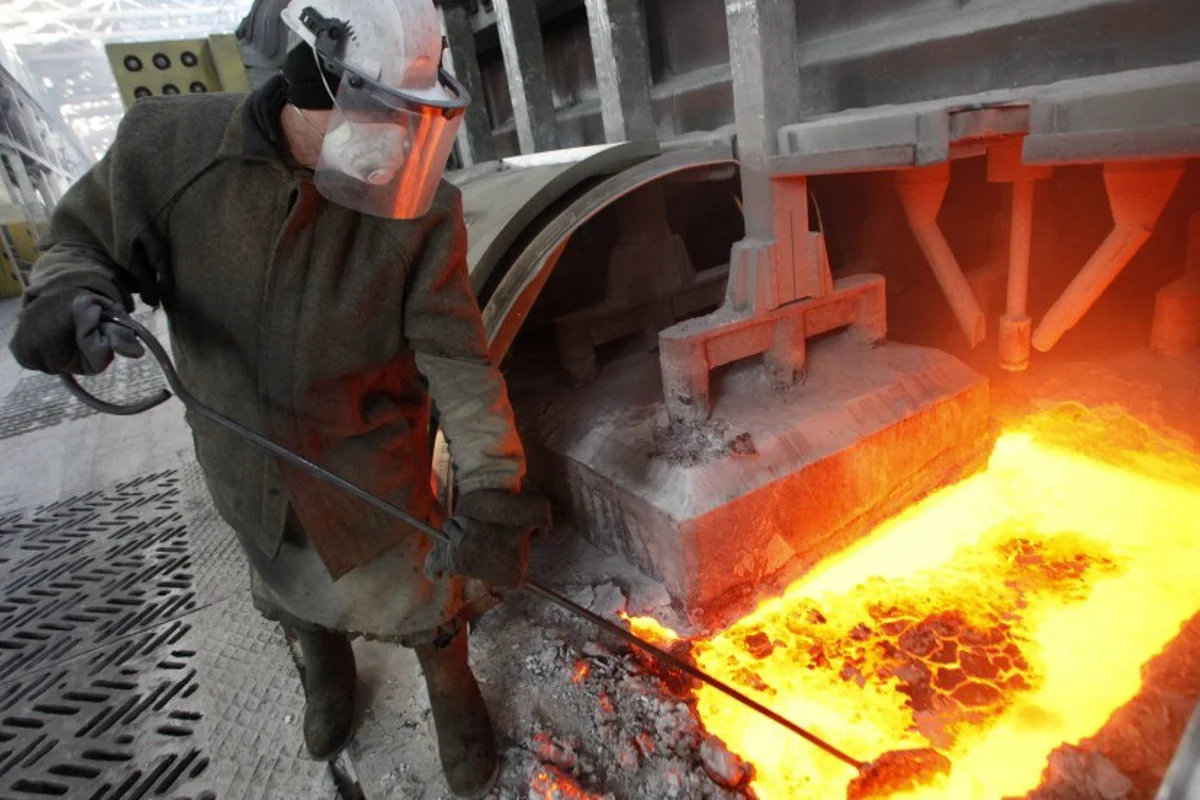
2017 was a year of significant change for the global aluminium market. The Chinese government initiated its aluminium supply-side reform policy, which we expect will limit long run primary capacity growth in China. The year also saw barriers to Chinese exports rise, particularly in the US. Limited production growth in China and low inventory levels outside of China, combined with strong consumption growth means smelters need to be built outside of China. But where will these new smelters be constructed? And who will build them?
Russia to add the largest share of capacity outside China
CRU has incorporated a number of greenfield and brownfield smelter expansions into our long term output forecasts. Although we still expect China to account for majority of the new smelting capacity, a large proportion of this capacity is yet to have started construction. The largest of these projects is Chalco's Fangchenggang greenfield smelter in the Guangxi province. The development will be built in two 1Mtpy phases and start construction in 2020.
Outside of China, we expect Russia will add the most aluminium smelting capacity. The largest project currently under construction globally is UC Rusal's Taishet project in Russia. In May 2017, UC Rusal announced that it has decided to restart construction at the 428,500tpy Taishet greenfield project. The company is also considering a second 555,100tpy line at the project using RA-550 (550kA) pot technology. This would lift overall production capacity at the plant to 983,600tpy.
CRU also expects more capacity to be added in the Middle East. This will be mainly driven by Alba's line 6 brownfield expansion, which will contribute to an increase in Alba's overall production capacity from 960,000tpy to 1.5Mtpy by 2019.
One of the most eye-catching smelting projects incorporated into our long term production forecasts is China Hongqiao Group's 500,000tpy project in Indonesia. China Hongqiao Group is evaluating moving overseas some of the smelting capacity idled as part of the Chinese government's supply-side reform policy. Indonesia appears to be the first choice for the relocation, as Hongqiao has a 1.0Mtpy alumina capacity in the country.
Read the full story: http://bit.ly/Wanted-new-aluminium-smelters
LME aluminium registers small gain supported by falling US dollar; SHFE continues to fall
Next articleVedanta to invest INR 12.4 bn on Jharsuguda smelter to elevate aluminium capacity
Grow with
AL Circle


